
Illustrated portrait of Morgan Hale.

Morgan Hale

Morgan Hale covers global business and company jurisdictions. The focus is on company structures, banking access and the records needed to keep a business running.

Latest

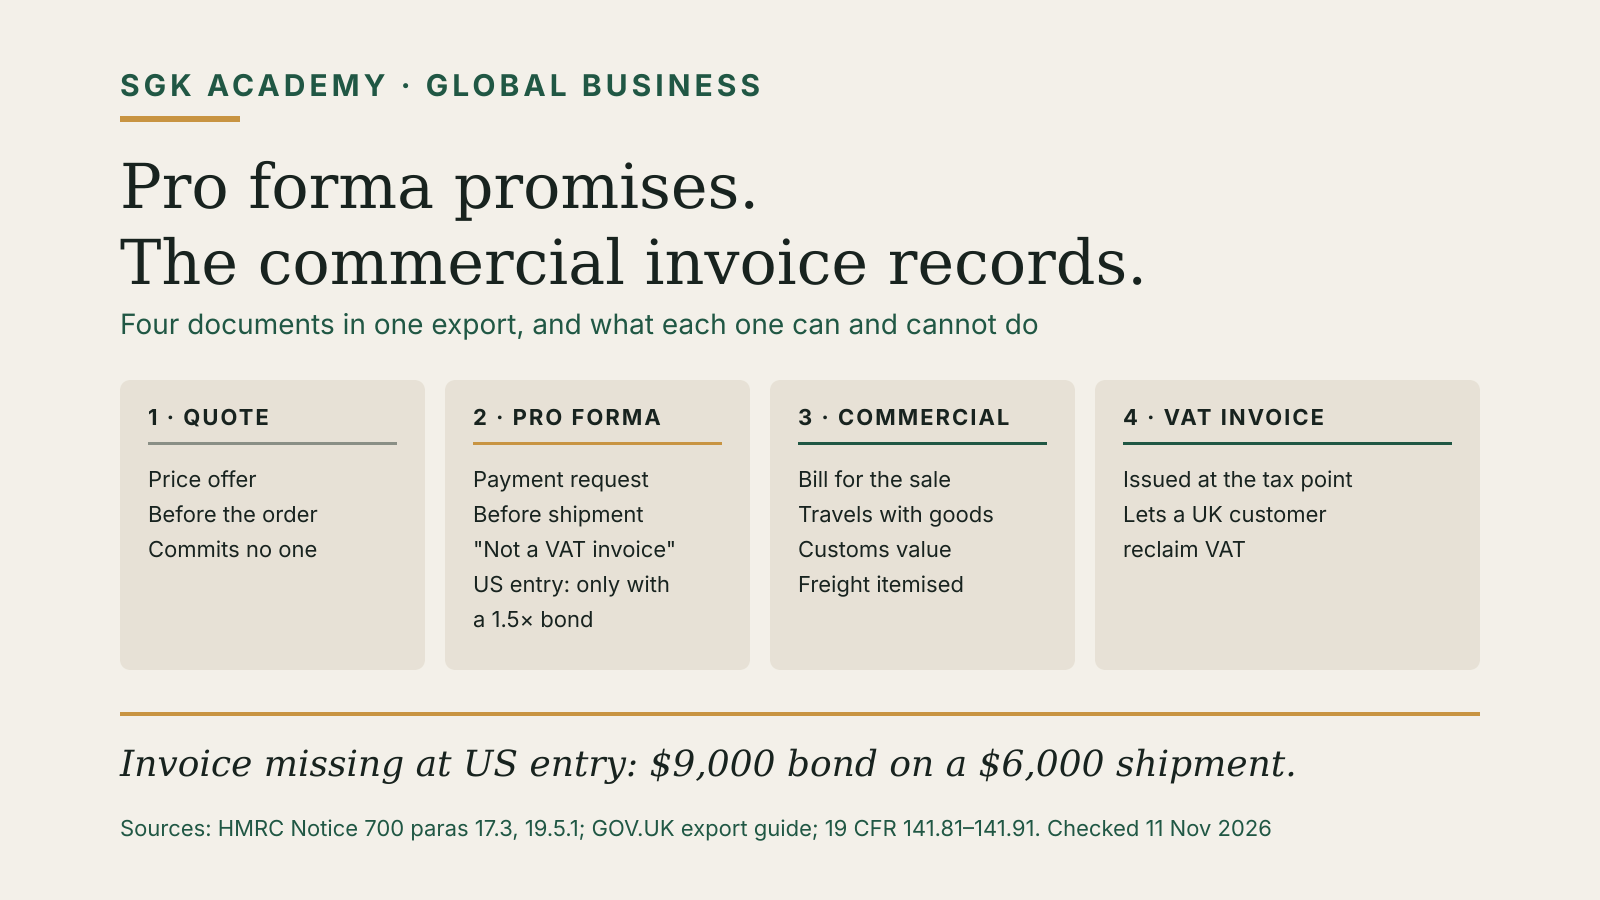
Four export documents compared: a quote is a price offer before the order; a pro forma invoice is a payment request before shipment, marked not a VAT invoice, and accepted at US entry only with a bond of 1.5 times the value; a commercial invoice is the bill for the sale that travels with the goods and sets the customs value with freight itemised; a VAT invoice is issued at the tax point and lets a UK customer reclaim VAT. Example: a missing invoice at US entry means a $9,000 bond on a $6,000 shipment.
invoicing ·

Pro Forma Invoice vs Commercial Invoice: What Each Does

A pro forma asks for payment before shipment; a commercial invoice records the sale and sets the customs value.
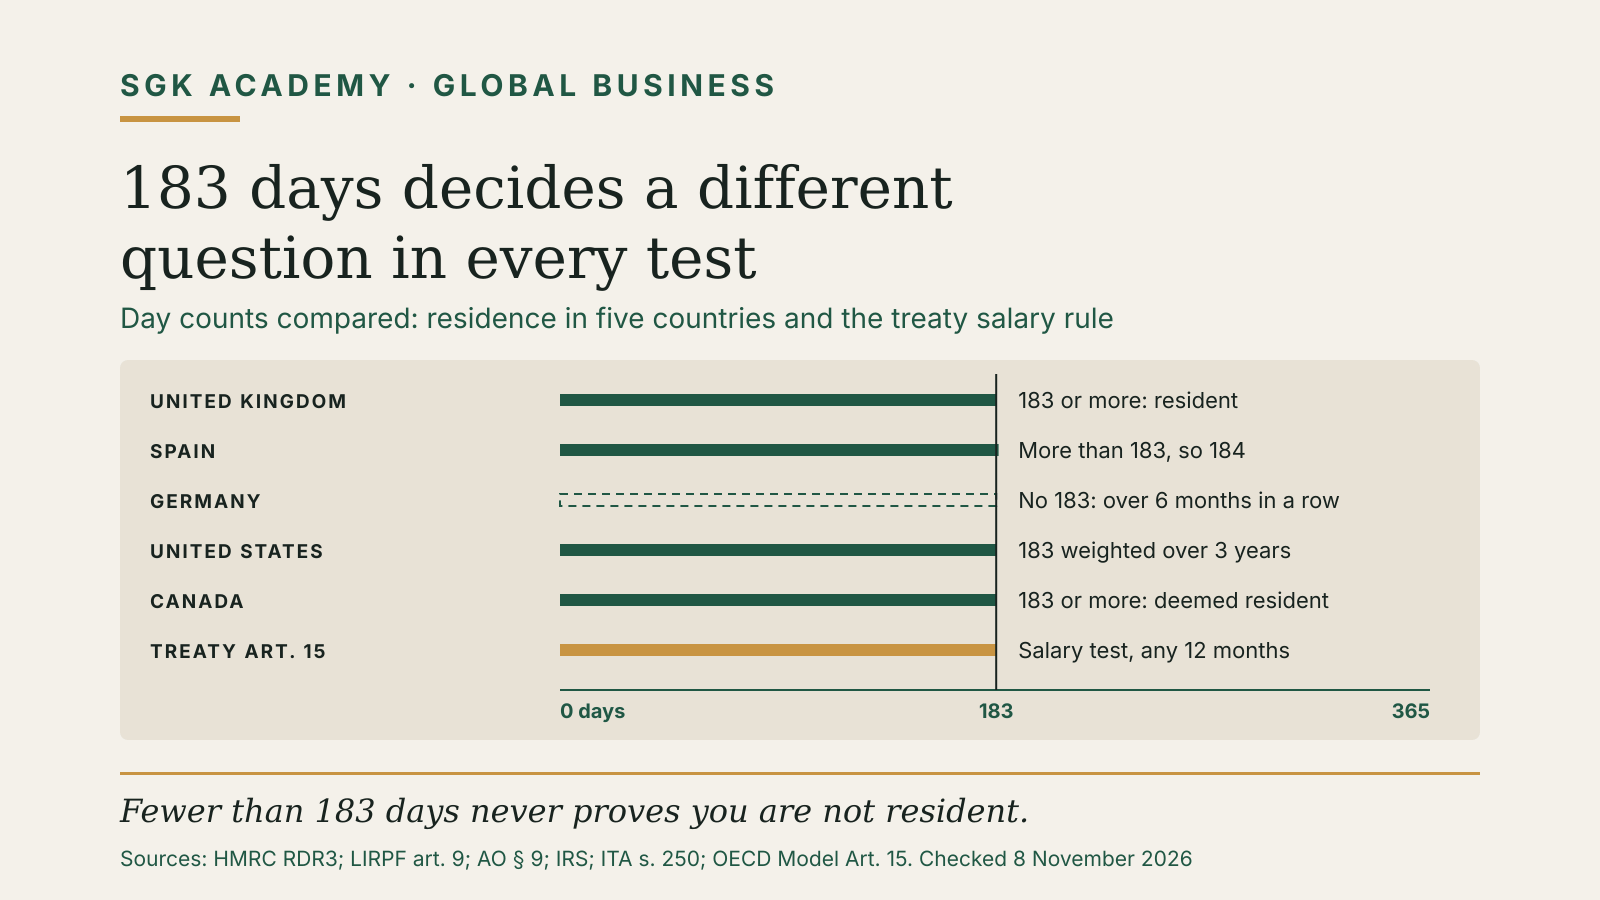
Chart comparing what 183 days means in six tests: in the UK 183 days or more makes you resident; Spain requires more than 183, so 184; Germany has no 183-day rule but treats a stay of over six months in a row as habitual abode; the US counts 183 weighted days over three years; Canada deems a 183-day sojourner resident; under tax treaty Article 15 the 183 days are a salary test over any 12 months.
183-day rule ·

The 183-Day Rule: What It Decides and What It Doesn't

There is no single 183-day rule: how six countries and tax treaties count days, and what each test decides.
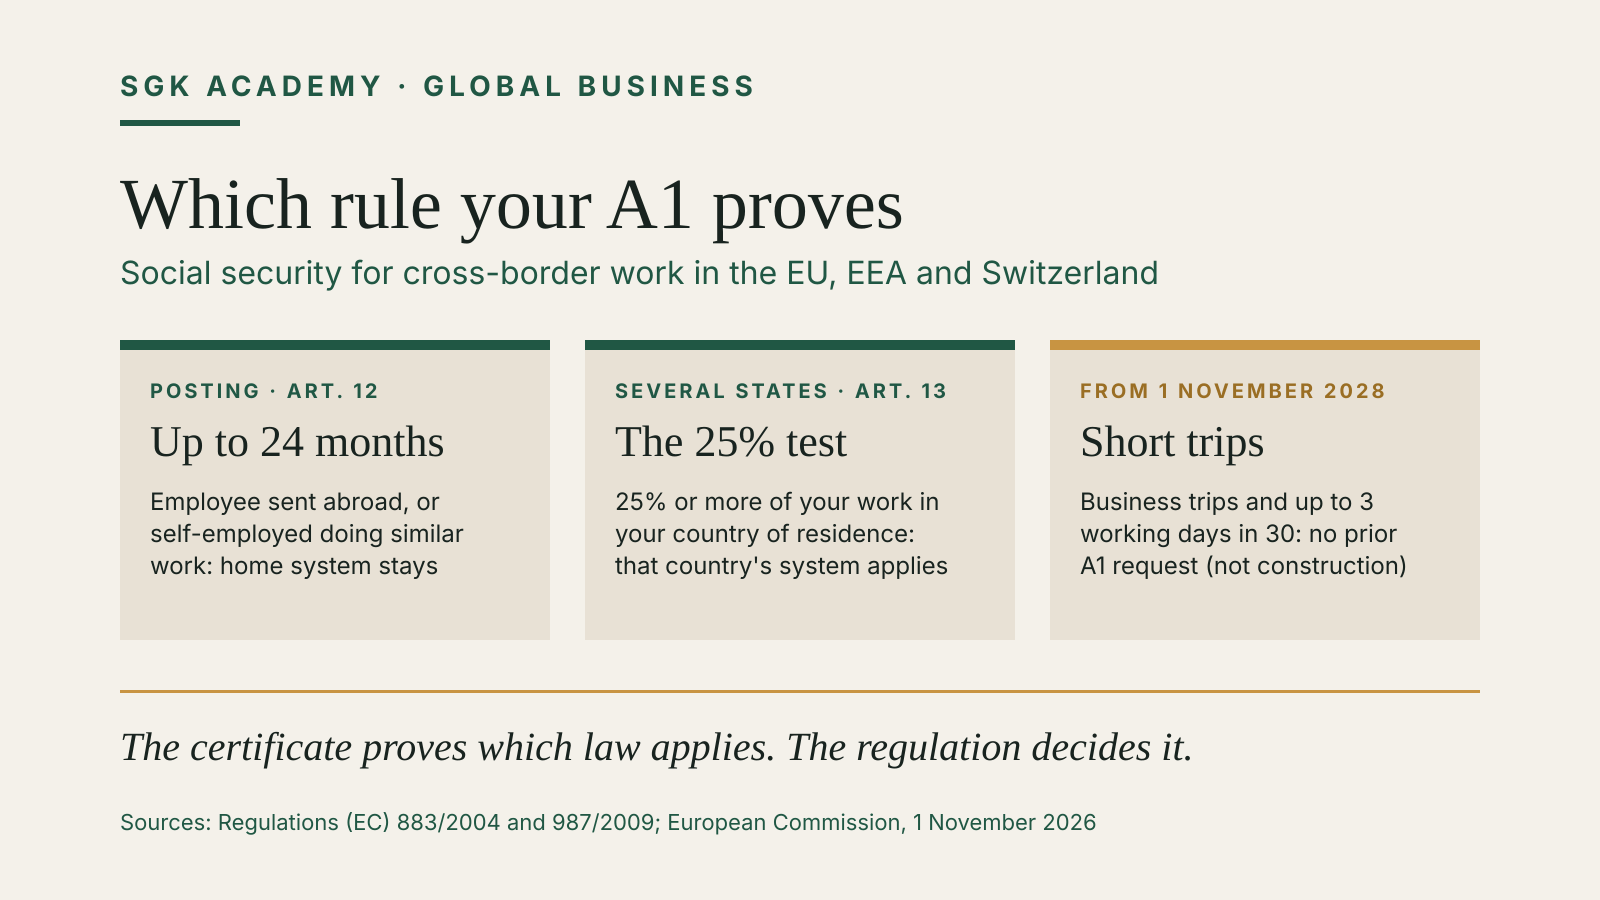
Three rules behind an A1 certificate: posting under Article 12 for up to 24 months keeps the home system; work in several states under Article 13 uses the 25% test in the country of residence; from 1 November 2028 business trips and activities of up to 3 working days in 30 need no prior A1 request, except in construction.
A1 certificate ·

A1 Certificate: Who Needs One and How to Apply

A1 certificate rules: 24-month postings, the 25% test for multi-country work, the 2028 changes and where to apply.
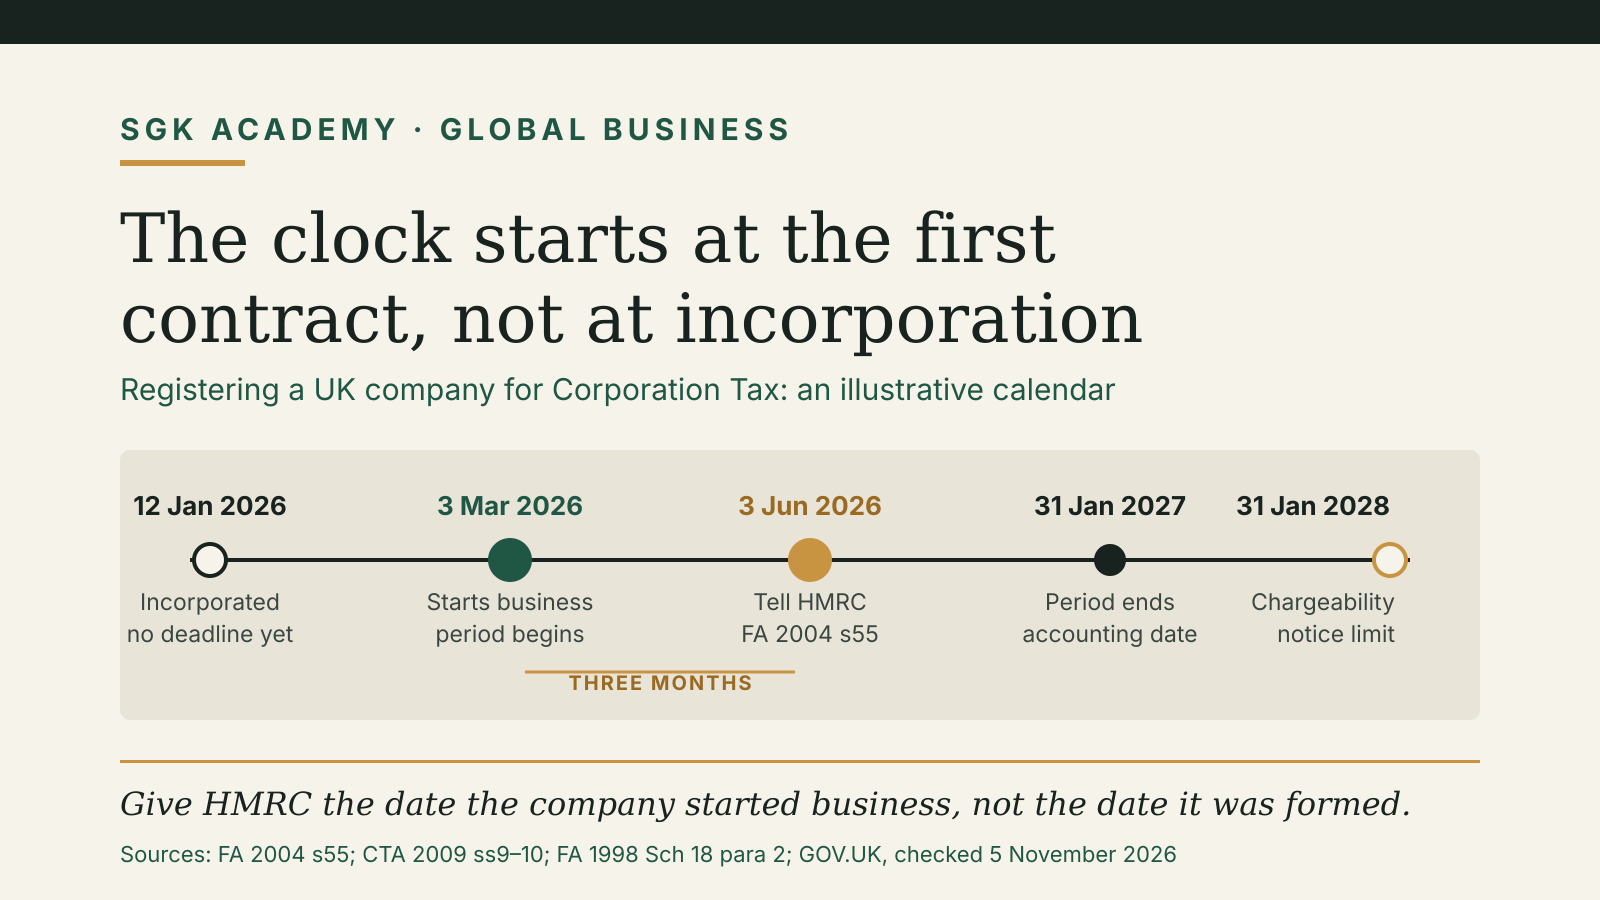
Illustrative Corporation Tax registration calendar for a UK company: incorporated 12 January 2026, starts business 3 March 2026, notice to HMRC due by 3 June 2026 under Finance Act 2004 section 55, first accounting period ends 31 January 2027, chargeability notice limit 31 January 2028.
Corporation Tax ·

Register for Corporation Tax: The Three-Month Notice Explained

The three-month clock runs from the first day of business, not incorporation. Routes for UK and overseas companies.
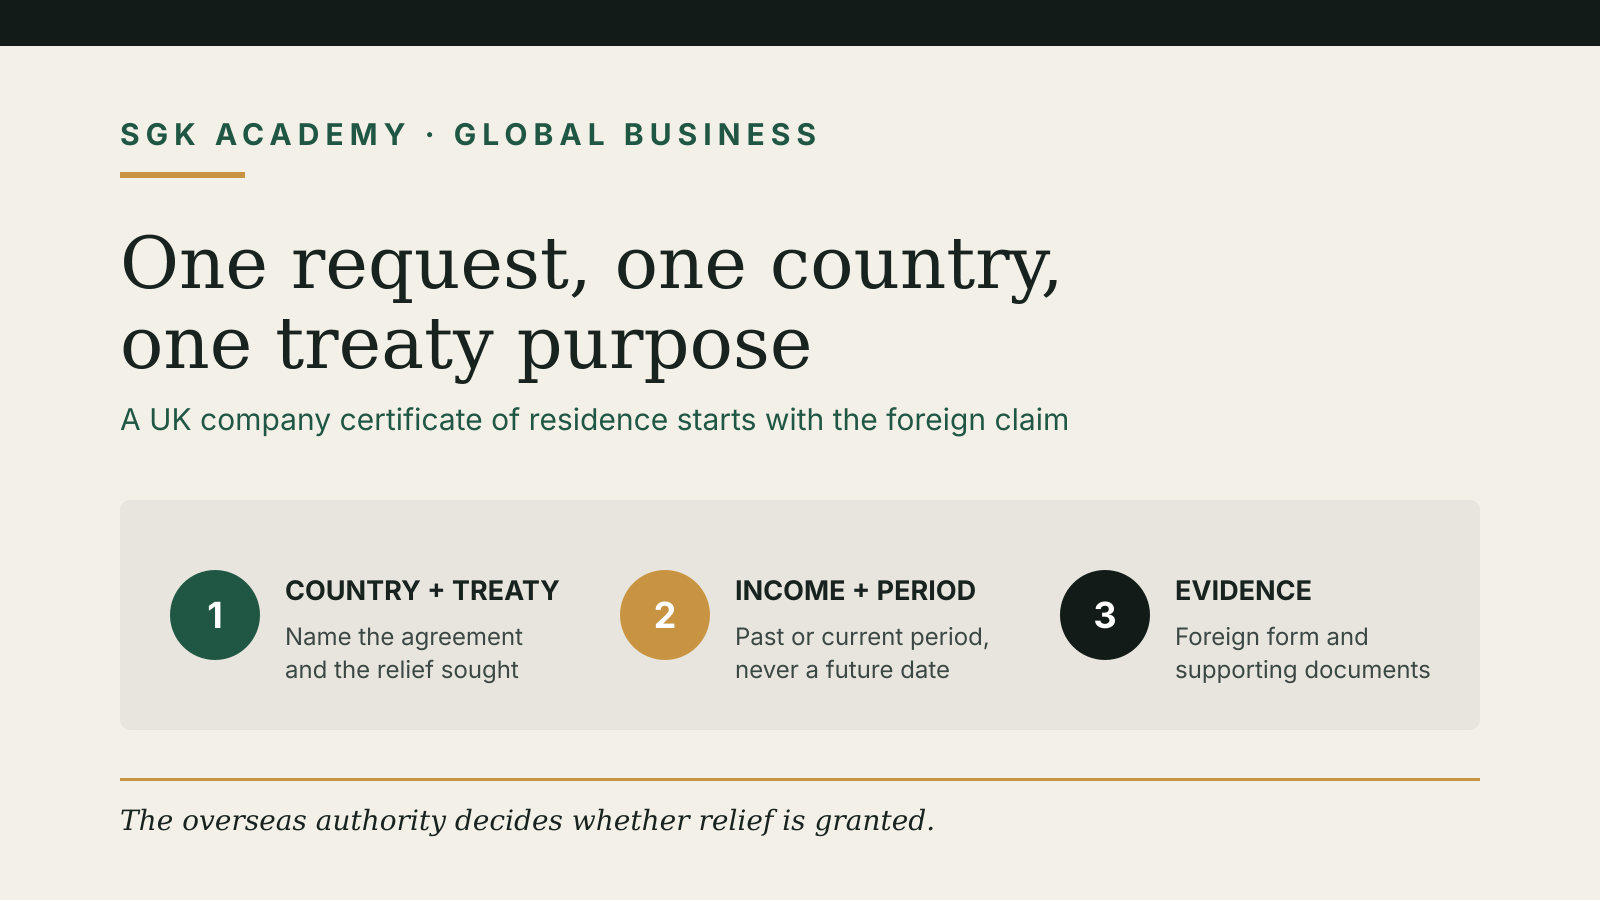
Three-step checklist for a UK company certificate of residence: country and treaty, income and a past or current period, and the foreign form with supporting documents
small business ·

UK Company Certificate of Residence: How to Apply

Prepare a UK company certificate of residence request with the right treaty, income, period and foreign form.
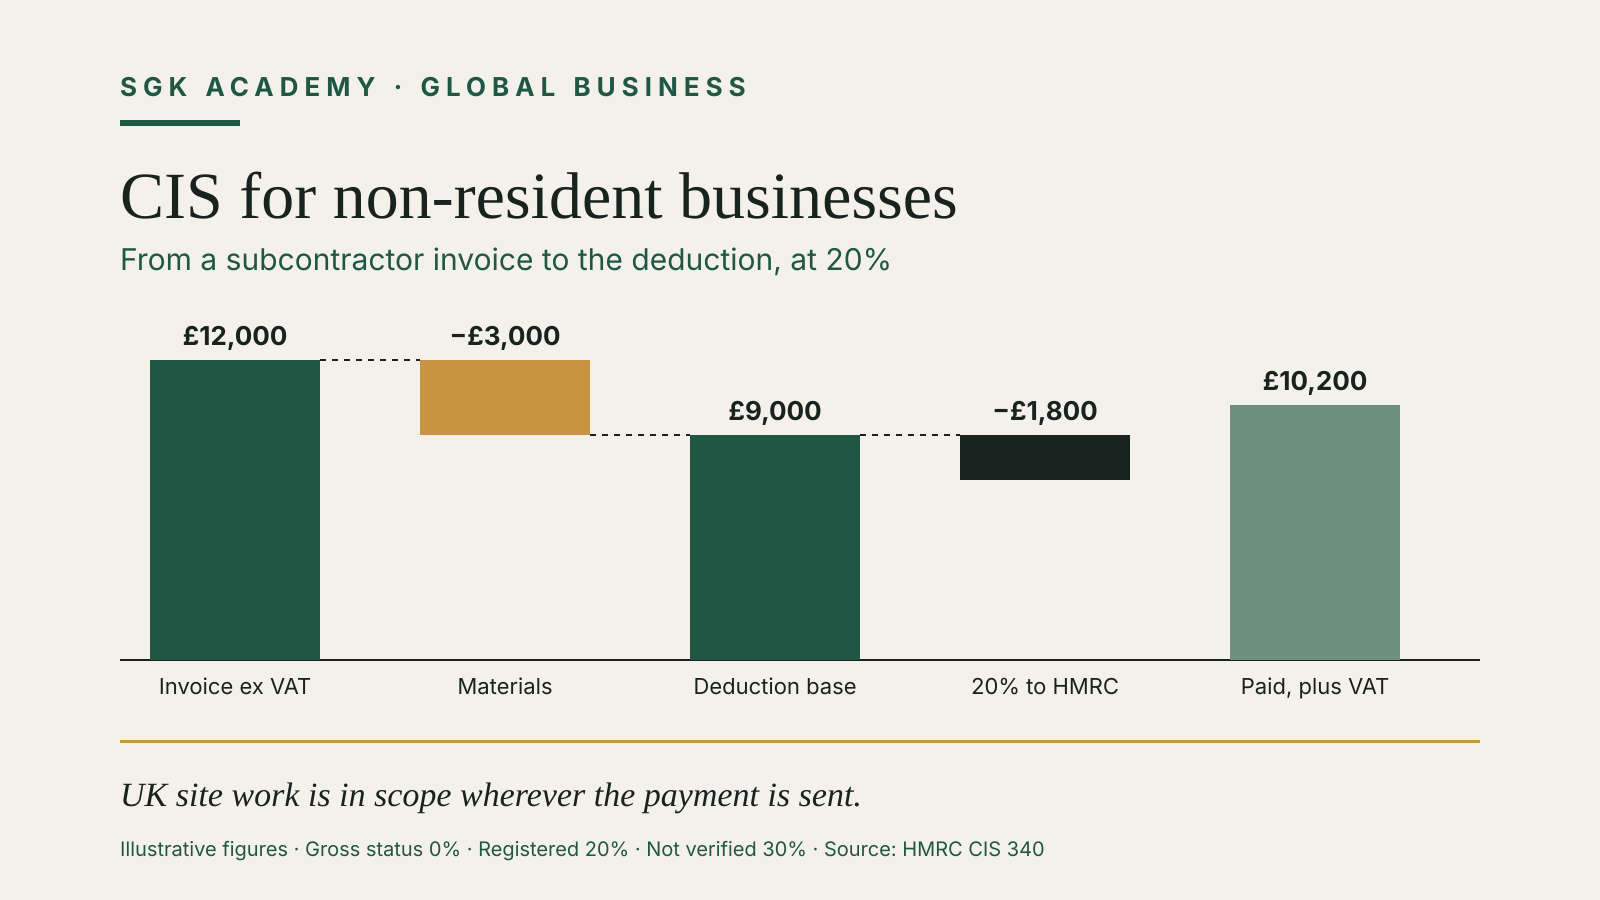
Waterfall chart of a CIS deduction: £12,000 invoice, £3,000 materials removed, £9,000 deduction base, £1,800 deducted at 20%, £10,200 paid plus VAT.
CIS ·

Construction Industry Scheme for Non-Resident Businesses

CIS for overseas businesses doing UK construction work: registration, verification, deductions and returns.
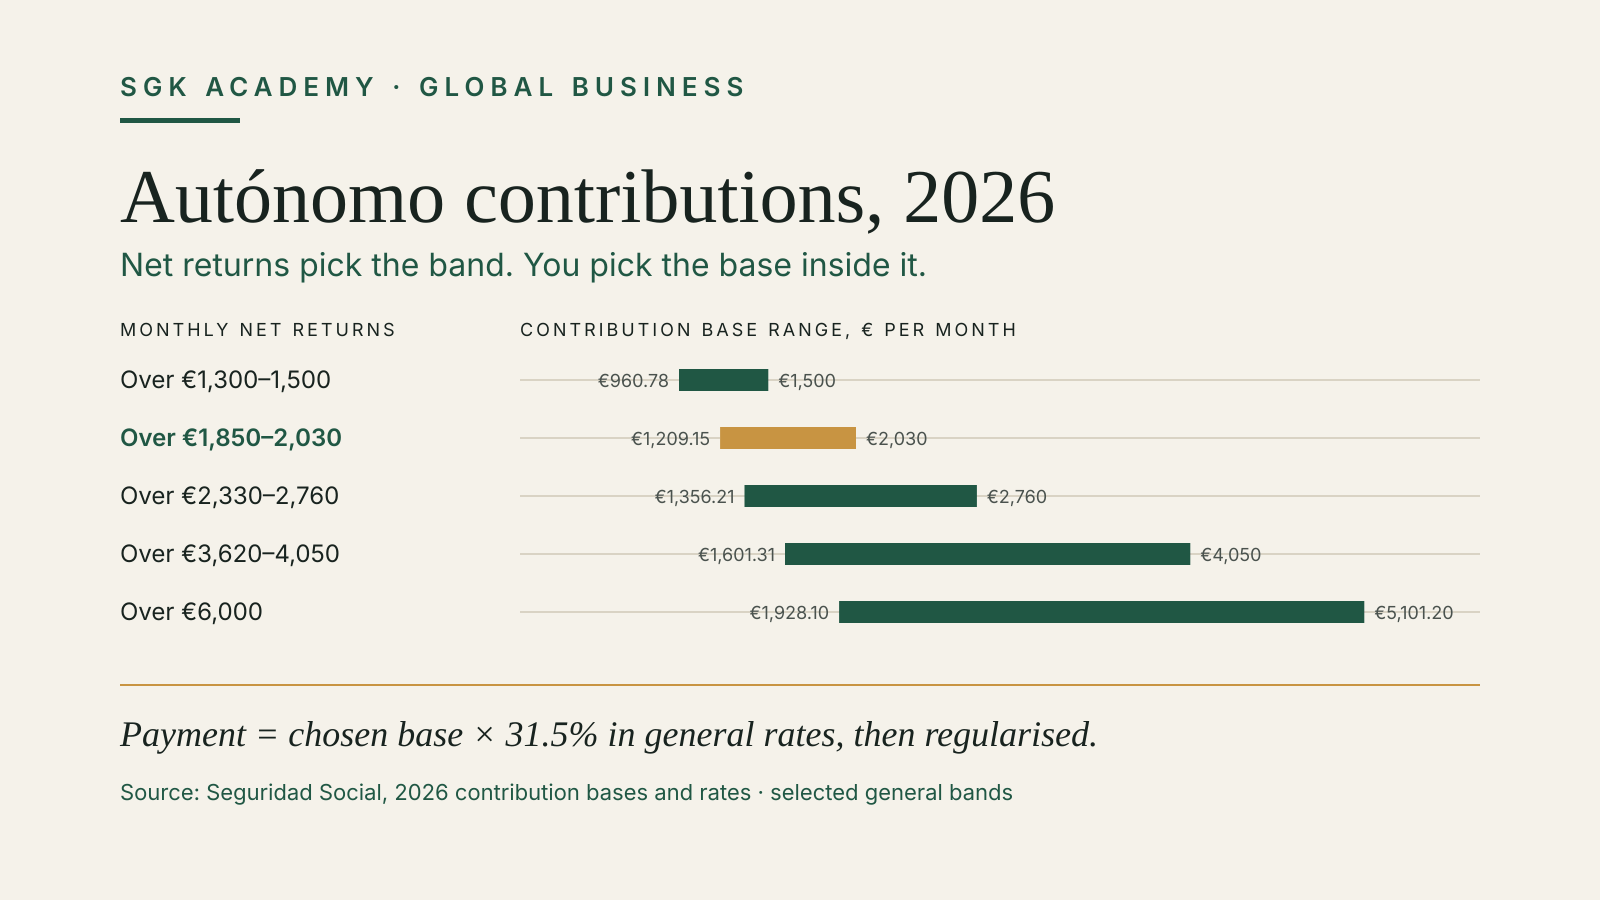
Chart of selected 2026 Spanish autónomo net-return bands with their minimum and maximum monthly contribution bases, from €960.78–€1,500 up to €1,928.10–€5,101.20.
Spain ·

Autonomo Social Security Contributions: Spain 2026 Guide

Read Spain’s 2026 autónomo income bands, contribution-base ranges and regularisation steps.
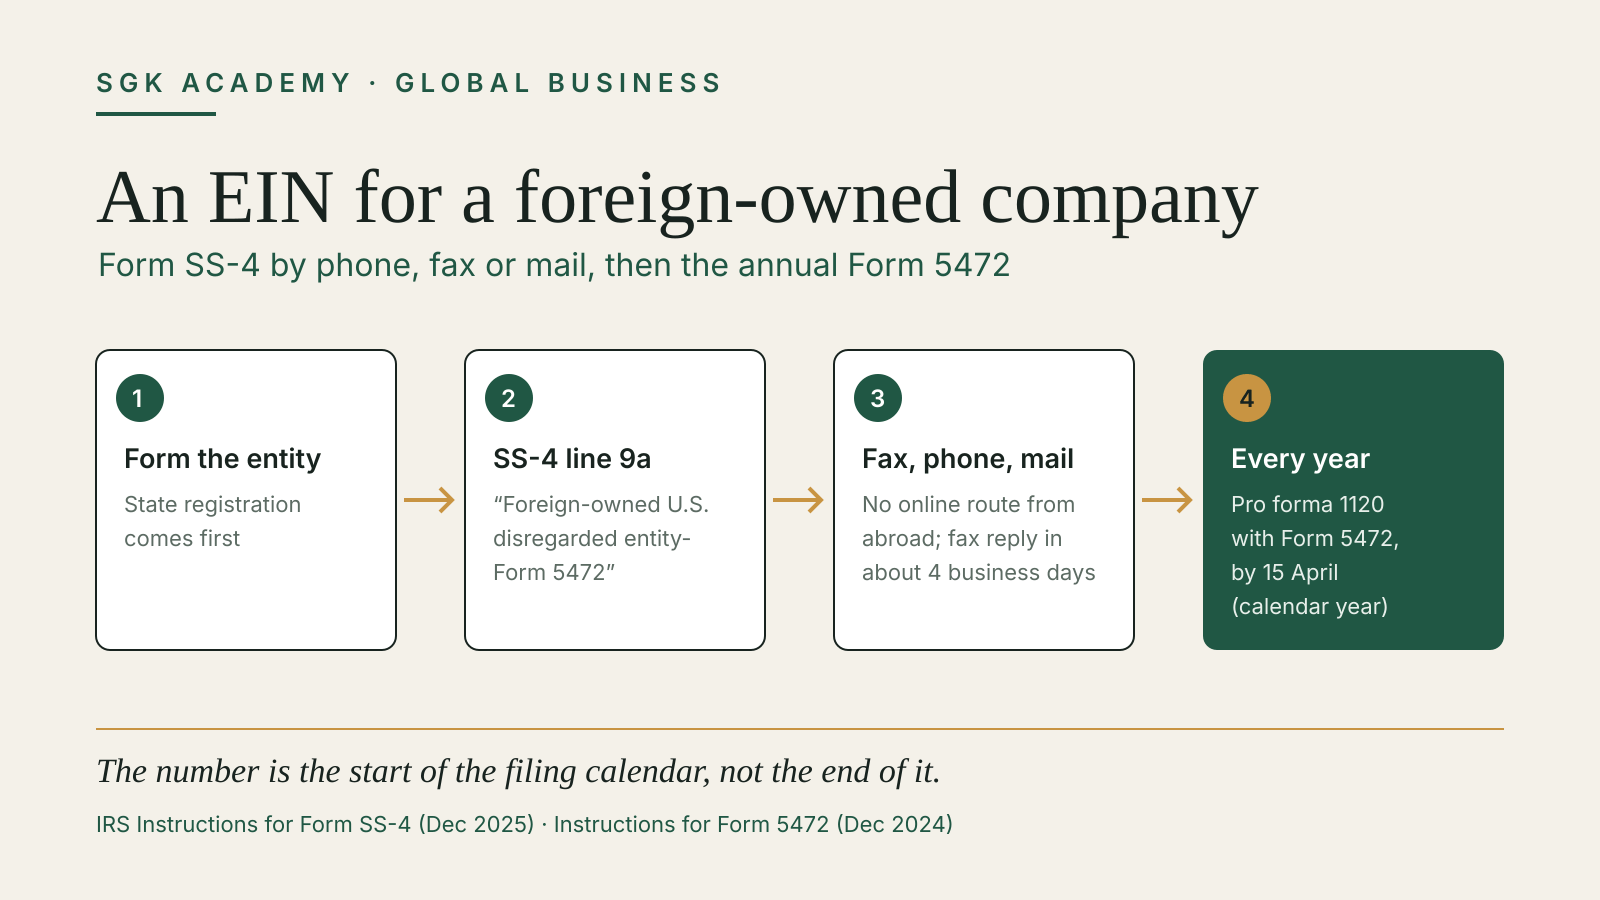
Four steps for a foreign-owned company's EIN: form the entity, complete Form SS-4 line 9a, apply by fax, phone or mail, then file a pro forma Form 1120 with Form 5472 each year
EIN ·

EIN for Non-Residents: How Foreign Owners Apply

How a foreign-owned LLC or corporation gets an EIN with Form SS-4, and what it must file afterwards.
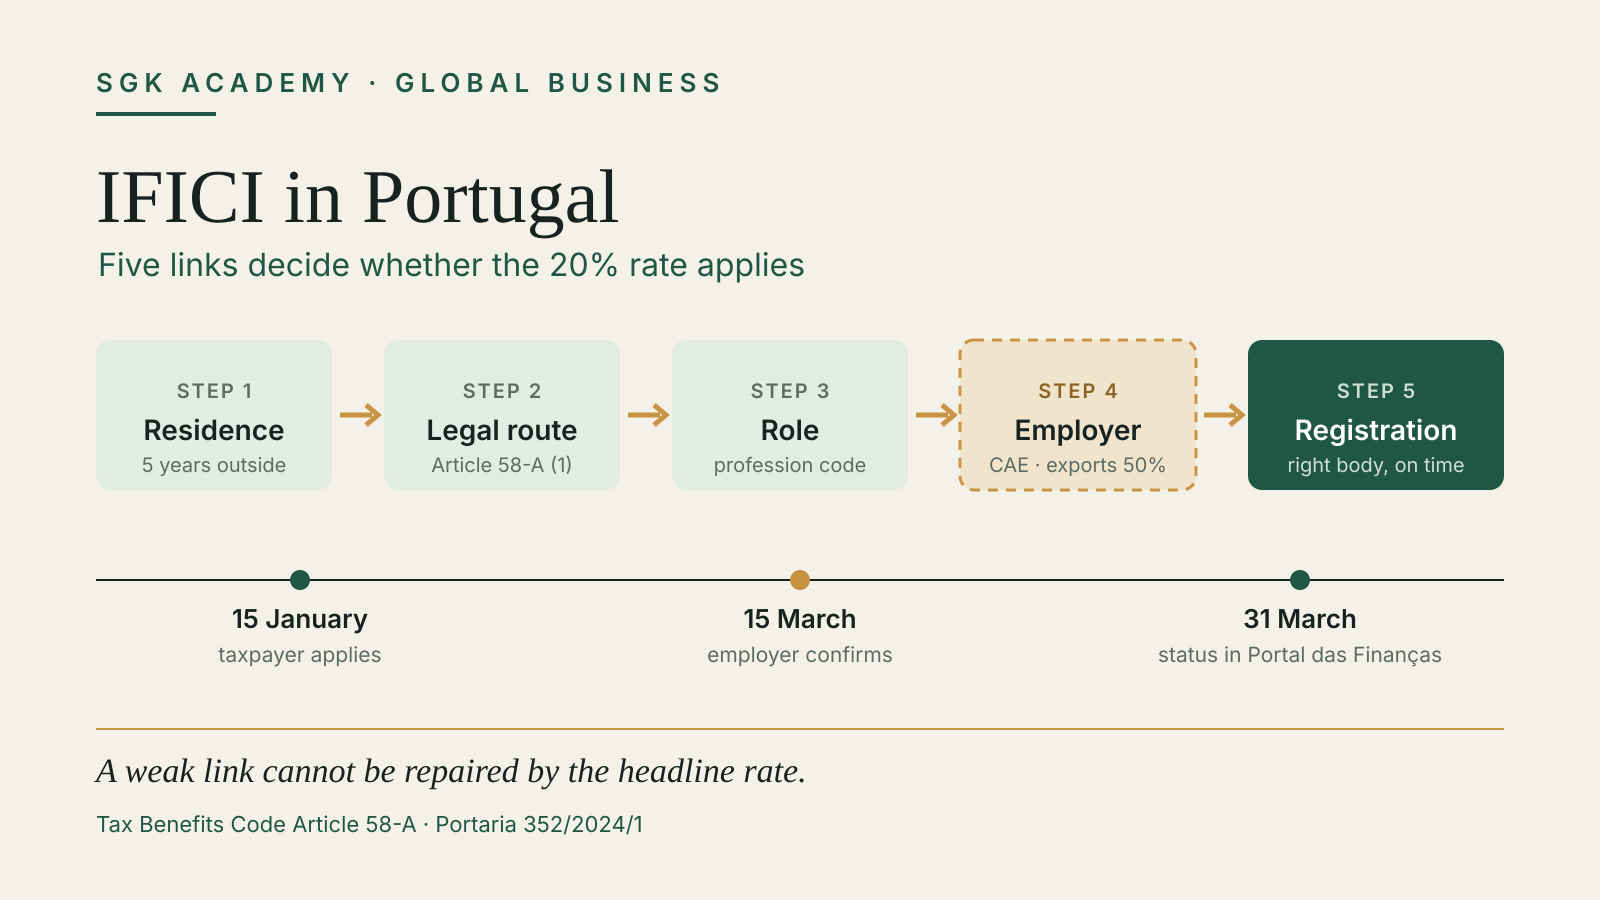
IFICI Portugal checklist: residence, legal route, role, employer and registration, with the 15 January, 15 March and 31 March dates
IFICI ·

IFICI Portugal: Eligibility, Deadlines and Documents

IFICI Portugal: check eligibility, qualifying roles, deadlines and documents before relying on the 20% rate.
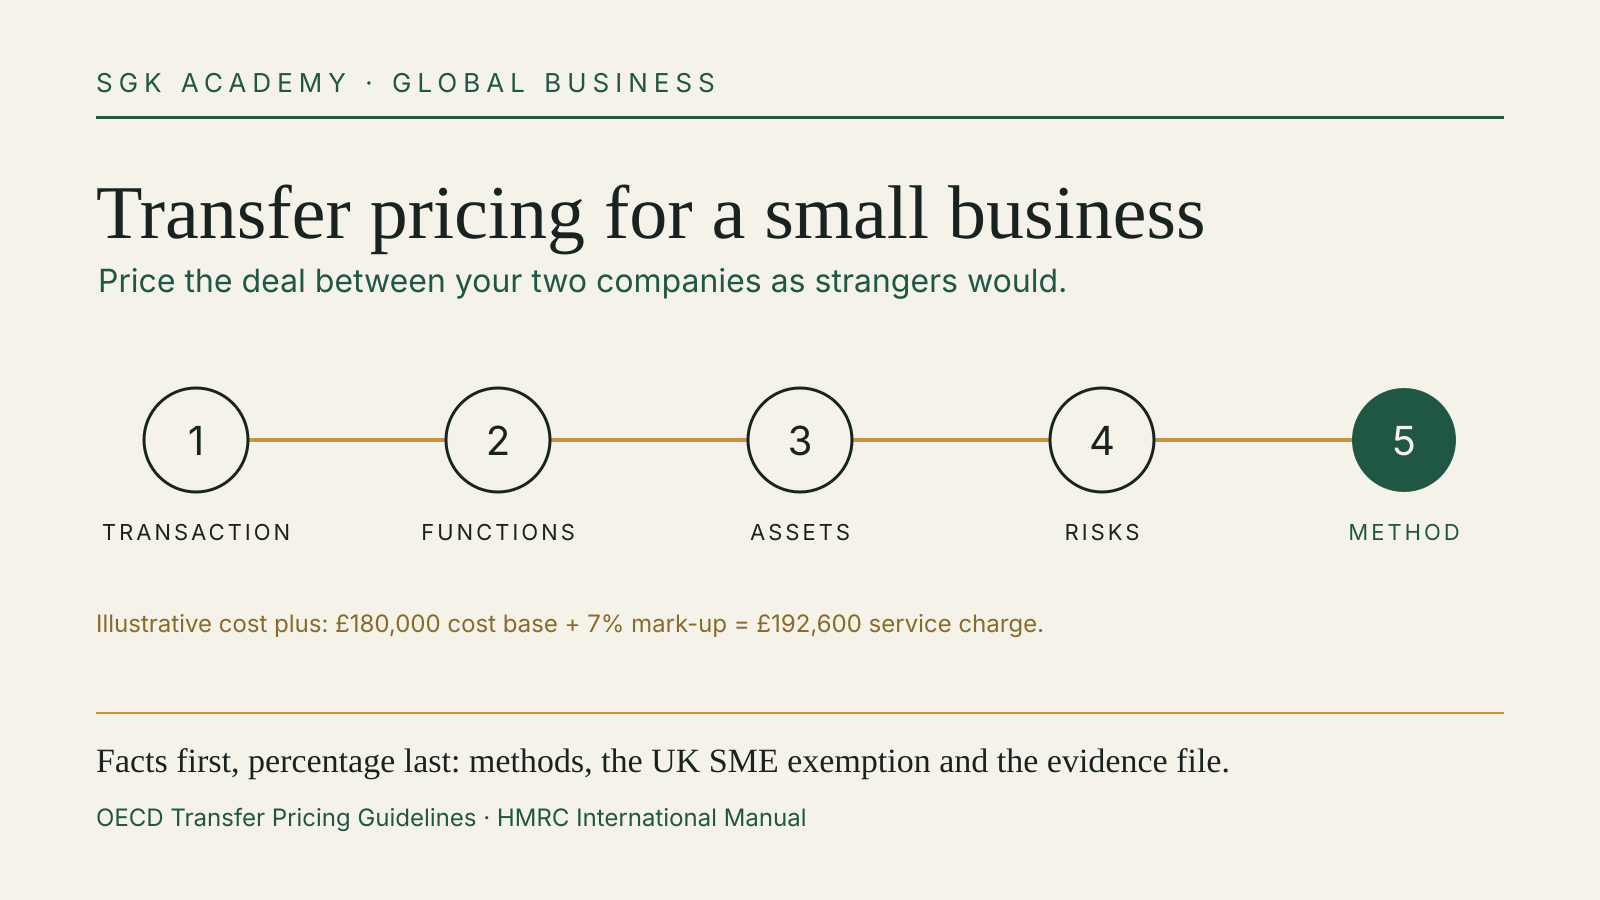
Five-step transfer pricing analysis for a small business: transaction, functions, assets, risks, then pricing method, with an illustrative £180,000 cost base plus 7% giving a £192,600 charge.
transfer pricing ·

Transfer Pricing for a Small Business: A Founder's Guide

A practical founder guide to arm's-length pricing, methods, exemptions and records when two related companies trade.
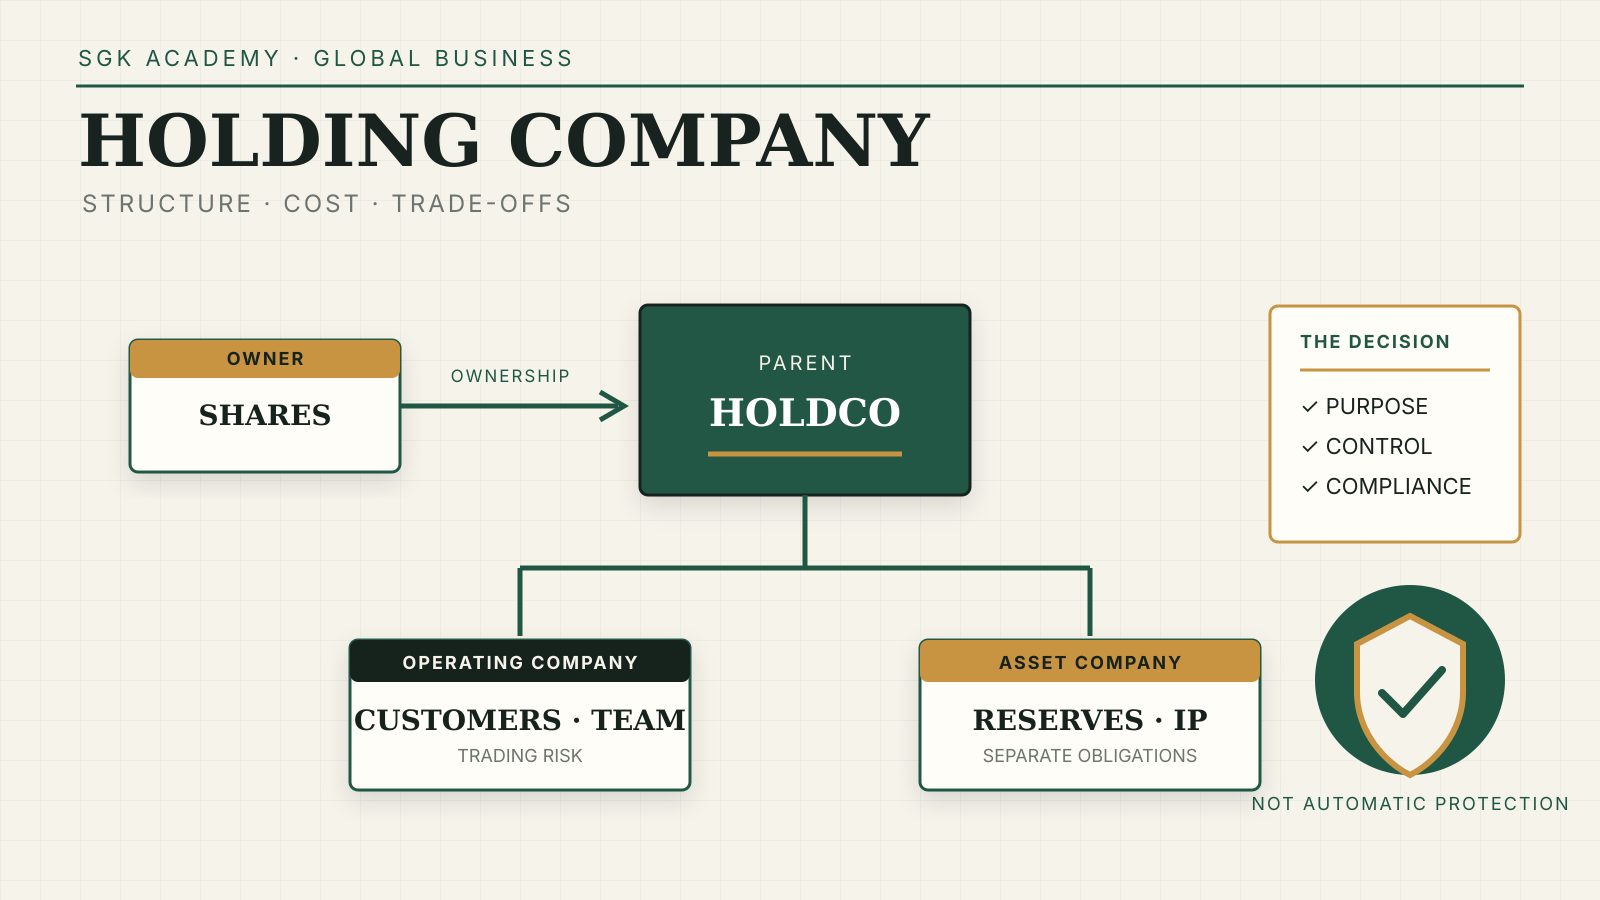
Holding company structure: the owner holds shares in a parent HoldCo, which owns an operating company with customers, team and trading risk, and a separate company holding reserves or IP; protection is not automatic.
Holding companies ·

Holding Company for a Small Business: UK Guide

When a UK small-business holding company helps, what it costs, and what to check before you restructure.
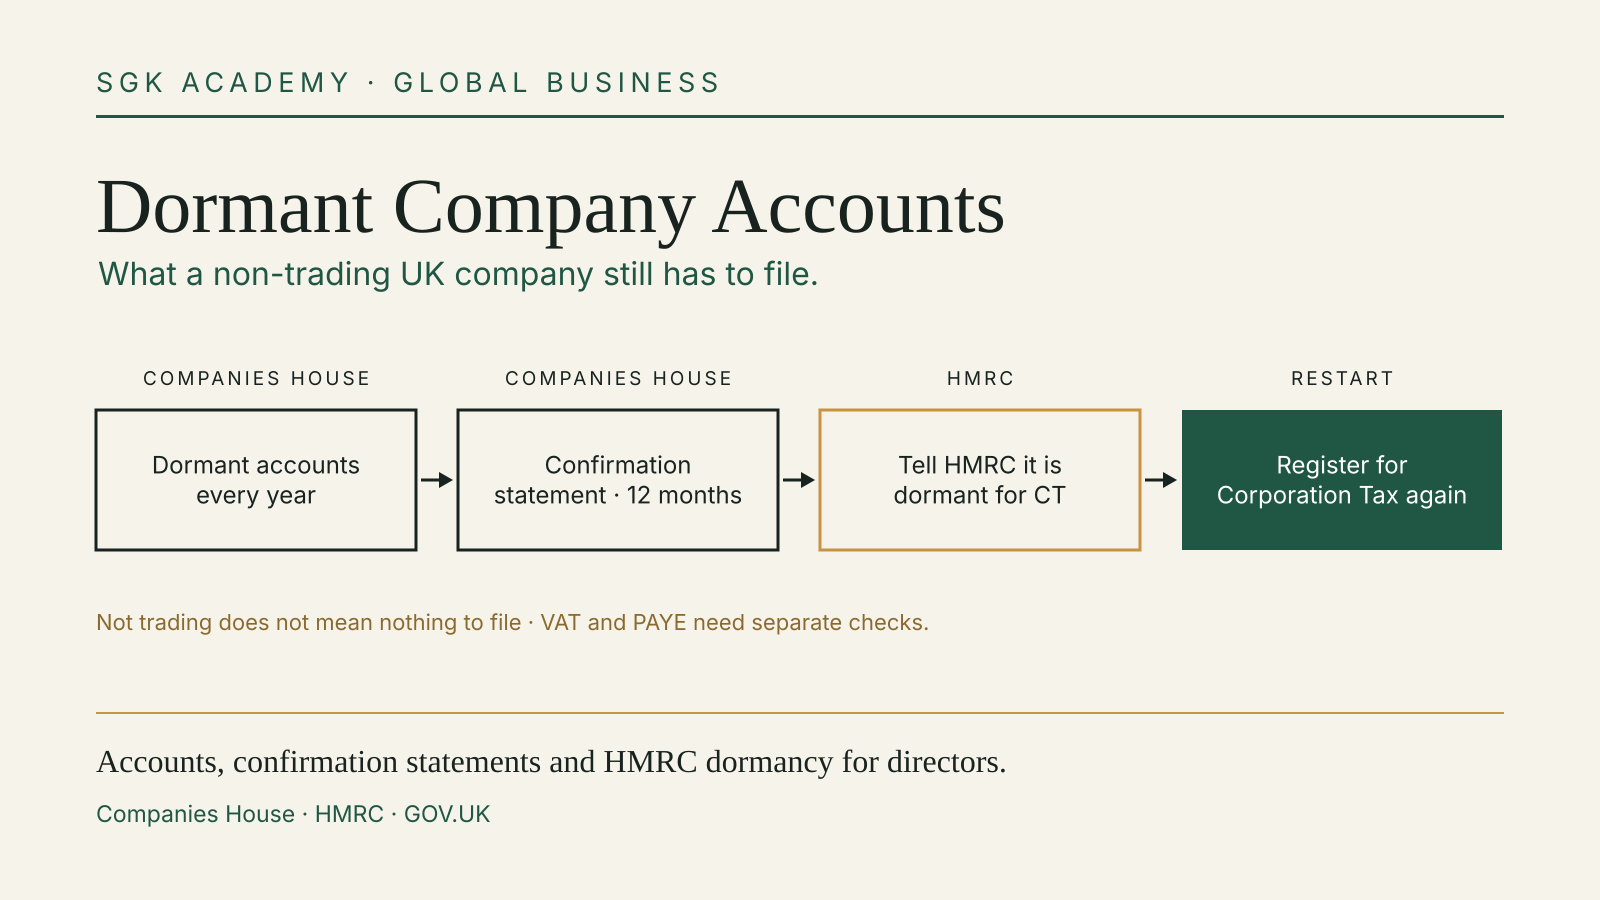
Dormant company filing steps: dormant accounts every year and a confirmation statement every 12 months at Companies House, telling HMRC the company is dormant for Corporation Tax, and registering again when trading restarts.
Companies House ·

Dormant Company Accounts: A Director’s Checklist

What UK directors still need to file when a company is dormant, from annual accounts to the confirmation statement.
A company register folder branching toward voluntary strike-off and formal liquidation documents
Company closure ·

How to Strike Off a Company: UK Closure Guide

How to close a UK limited company, when DS01 works and when formal liquidation is the safer route.
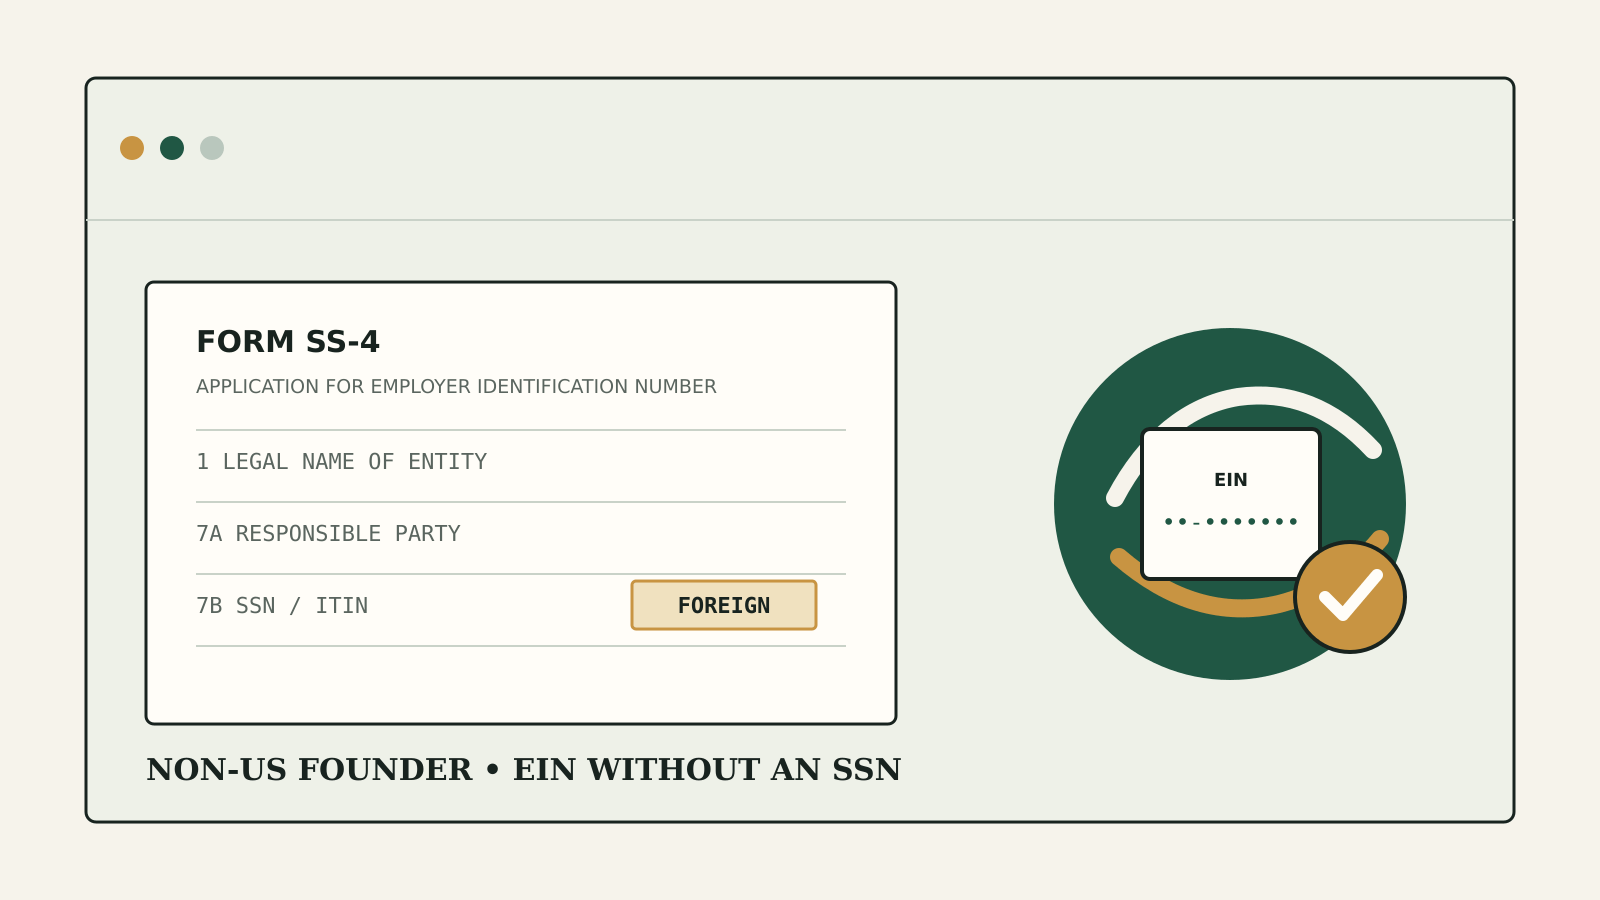
IRS Form SS-4 with a Foreign entry on line 7b and an EIN confirmation card
EIN ·

EIN Without an SSN: How Non-US Founders Apply

A current IRS guide to Form SS-4, line 7b and EIN routes for international founders.
tax residence ·

Certificate of Tax Residence: A Practical Cross-Border Guide

How to document tax residence, claim treaty relief and avoid withholding delays.
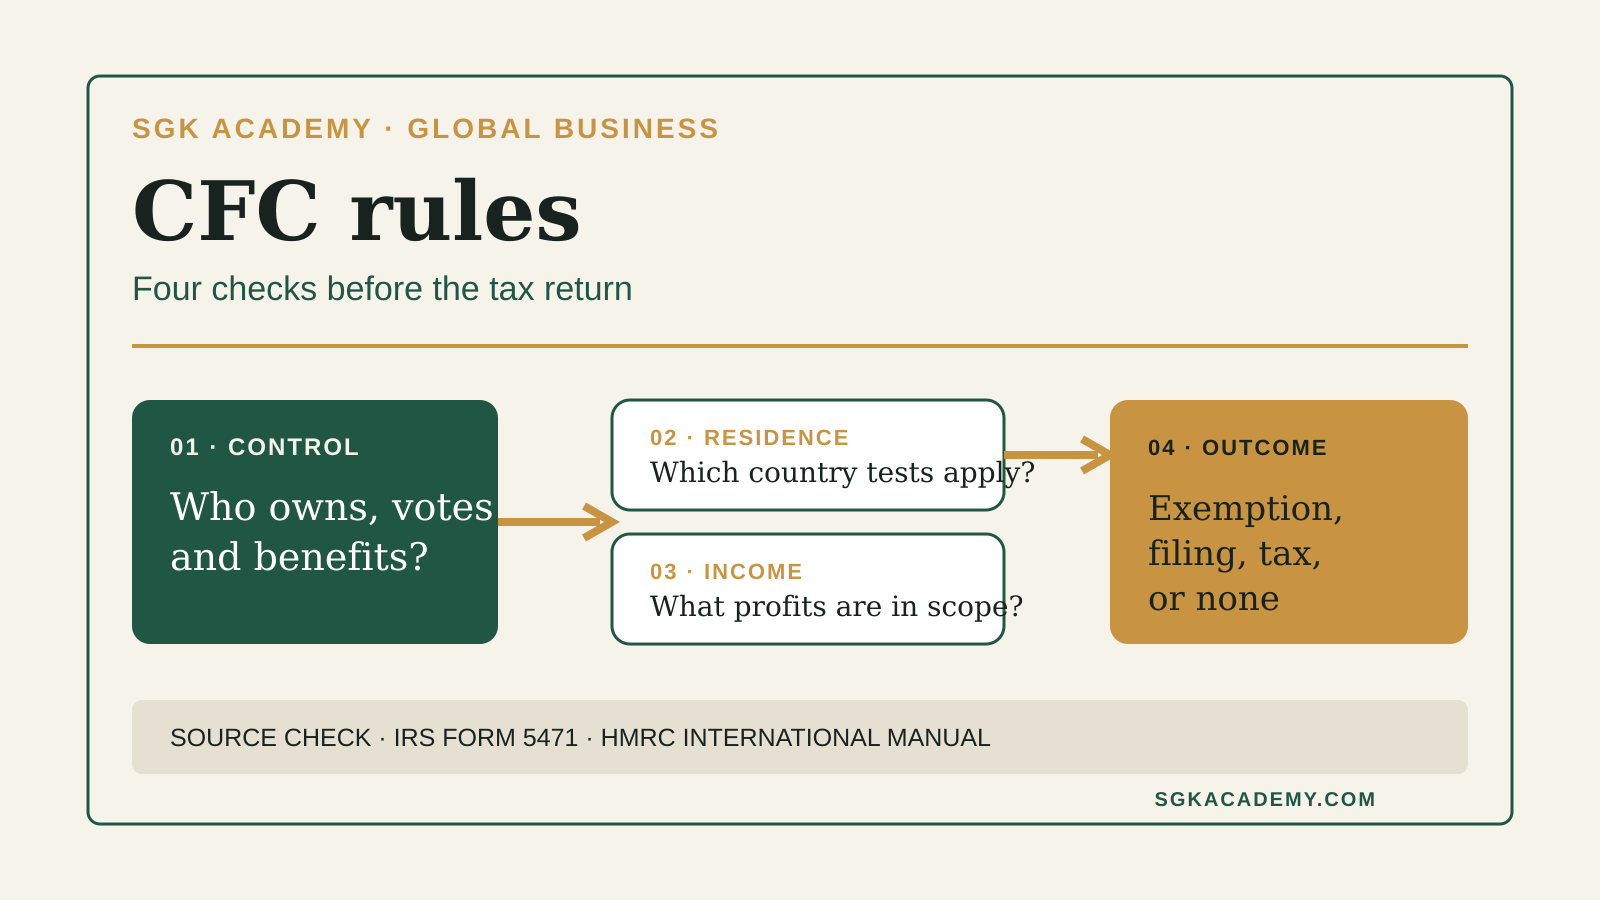
CFC rules ·

CFC Rules: A Screening Guide for Foreign Company Owners

A practical CFC rules check for ownership, residence, income, exemptions and filing duties.
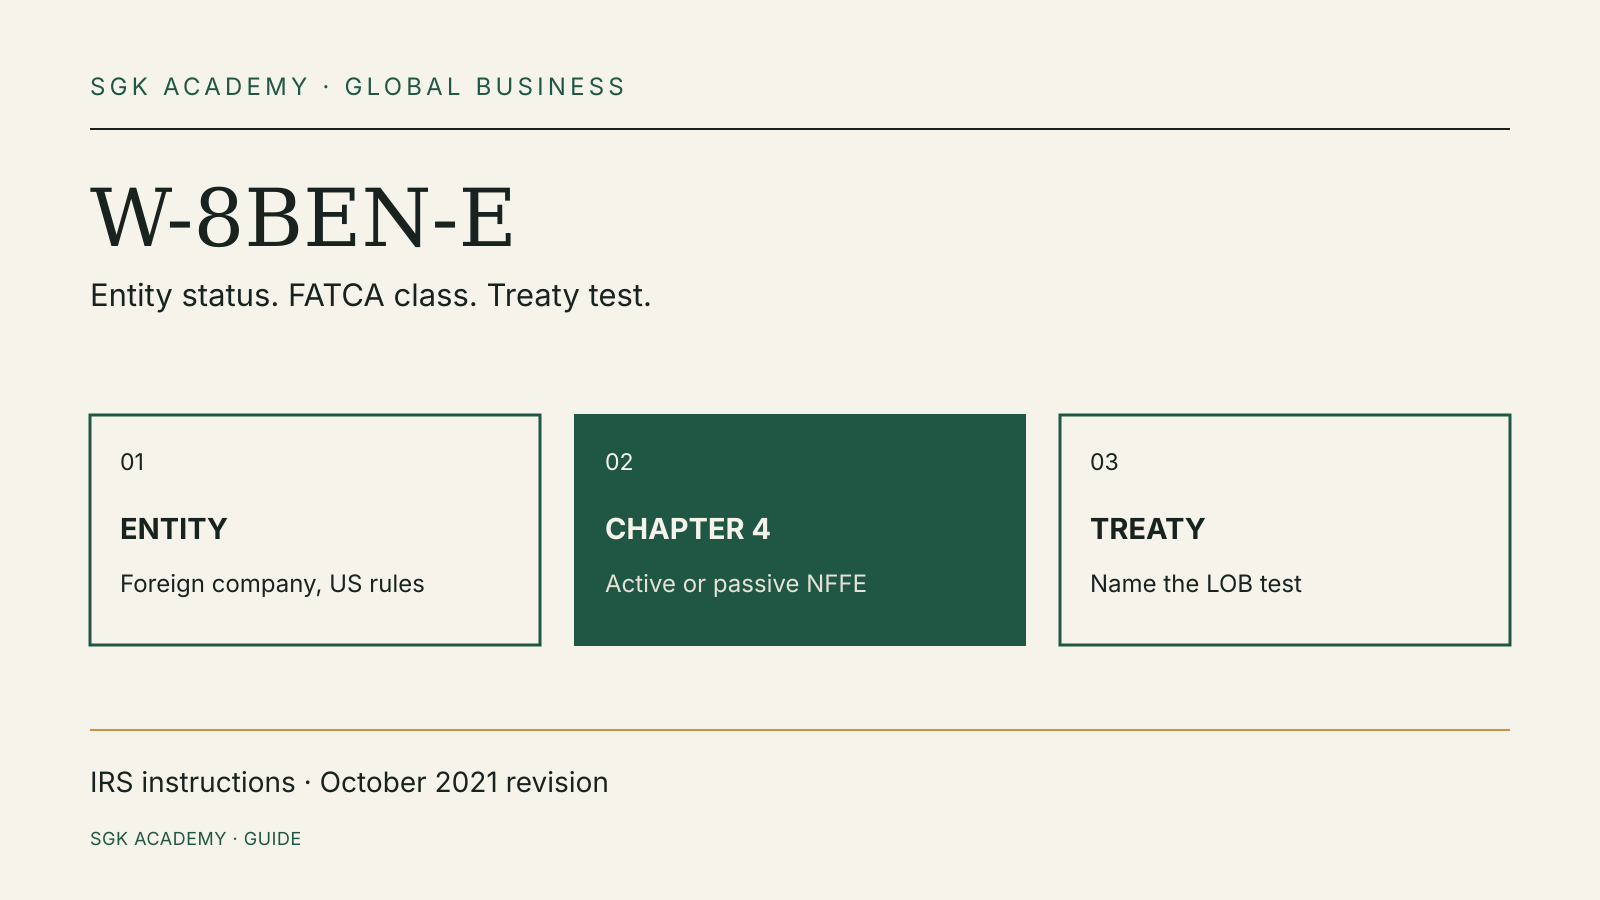
W-8BEN-E checklist: foreign entity under US rules, chapter 4 status as active or passive NFFE, and the limitation-on-benefits test for a treaty claim.
Tax forms ·

W-8BEN-E for Non-US Companies: Status, Treaty Claims, Expiry

Which companies use W-8BEN-E, how to pick the FATCA status, what a treaty claim needs and how long the form lasts.
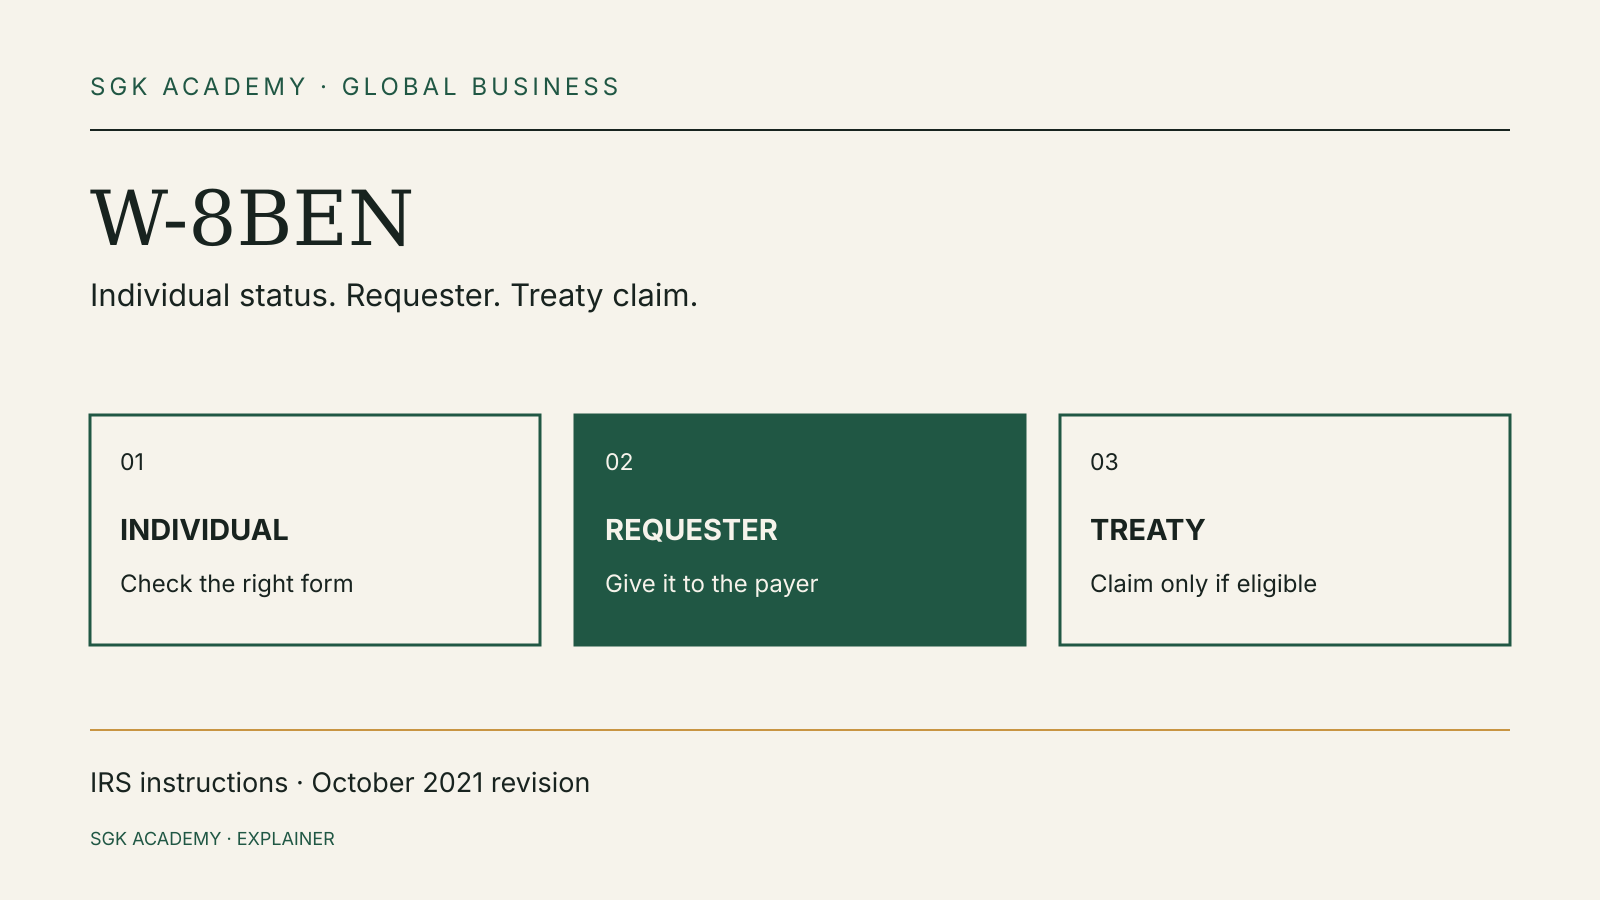
W-8BEN checklist: individual eligibility, submission to the requester and applicable treaty claims.
Tax forms ·

W-8BEN for Individuals: Status, Claims and Expiry

Understand who uses W-8BEN, where it goes, how treaty claims differ and when a replacement is needed.
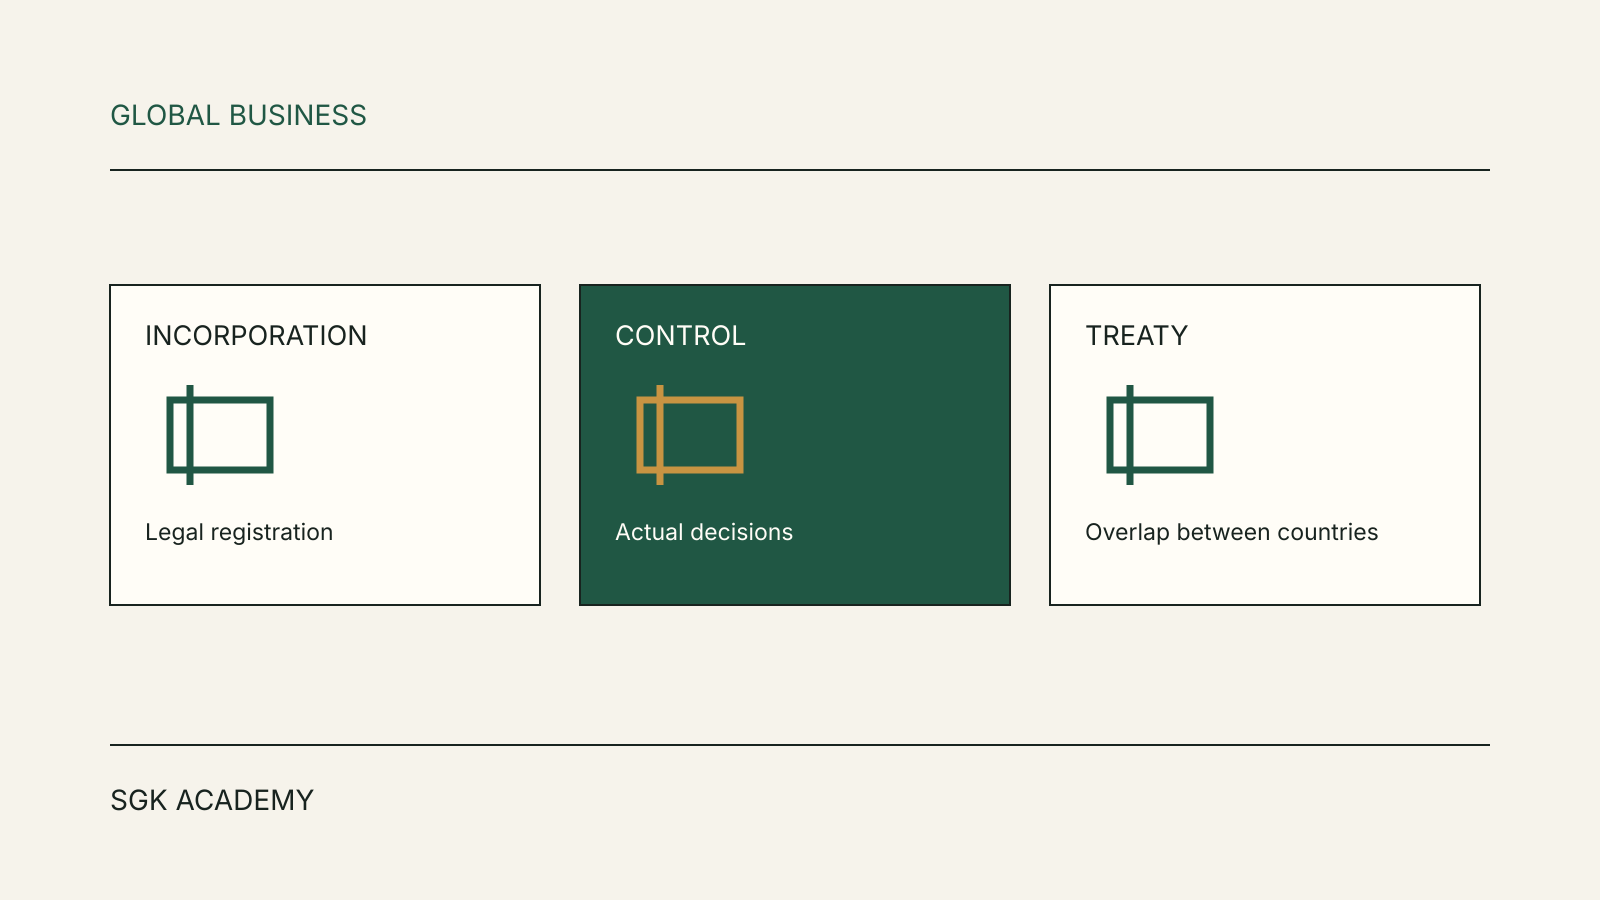
Three separate company residence questions: incorporation, real management and the applicable treaty
Global Business ·

Company Tax Residence: Incorporation, Control and Treaties

Company registration, real management and treaty residence can point to different countries. Check each separately.
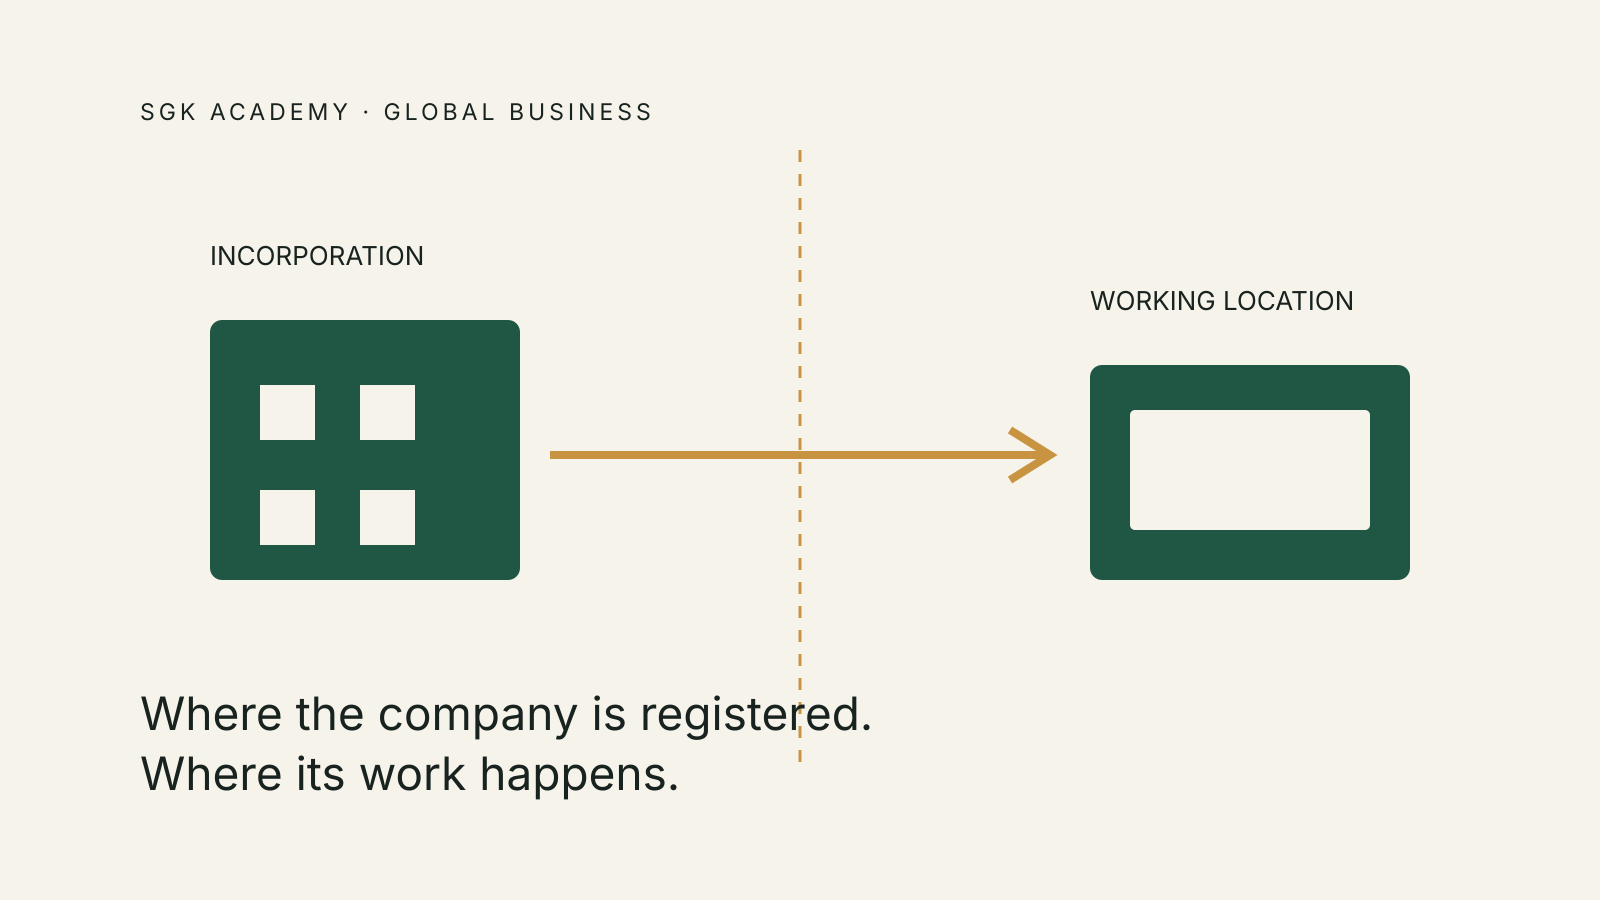
Company registration and a separate working location connected across a border.
Global Business ·

Permanent Establishment and Remote Work: A Founder's Guide

Working abroad can raise company tax questions. Understand fixed-place, agent and recurring-work considerations.
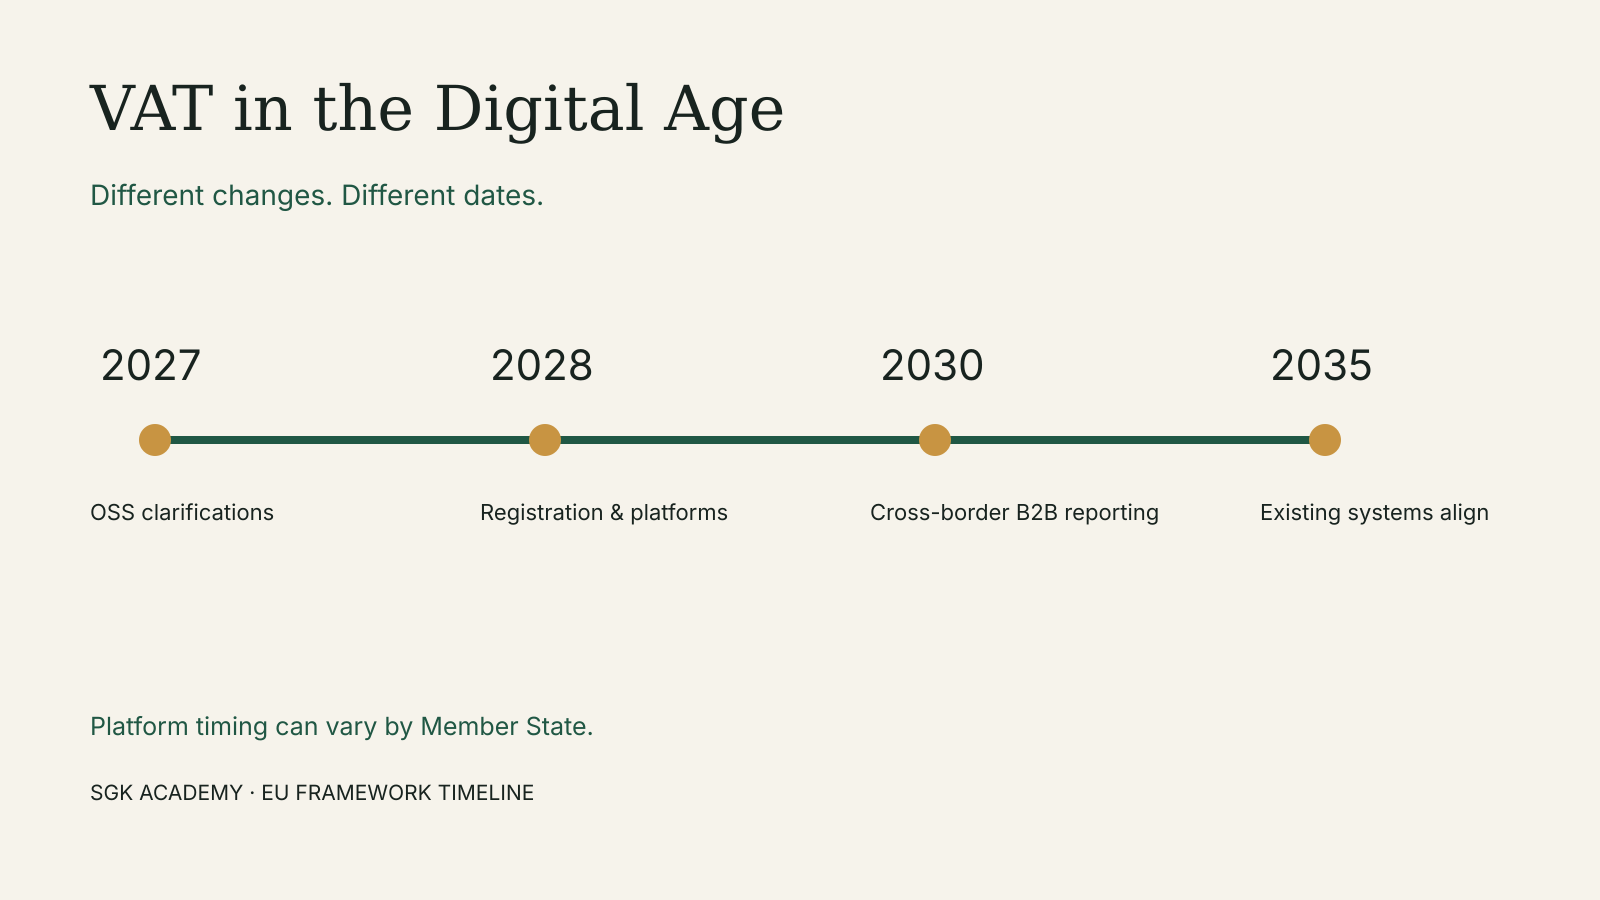
ViDA timeline: OSS changes in 2027, registration and platforms from 2028, cross-border reporting in 2030, existing systems aligning by 2035.
VAT ·

VAT in the Digital Age: what changes for small businesses from 2027

The ViDA timetable and the sales, invoice and software checks a small business can prepare.
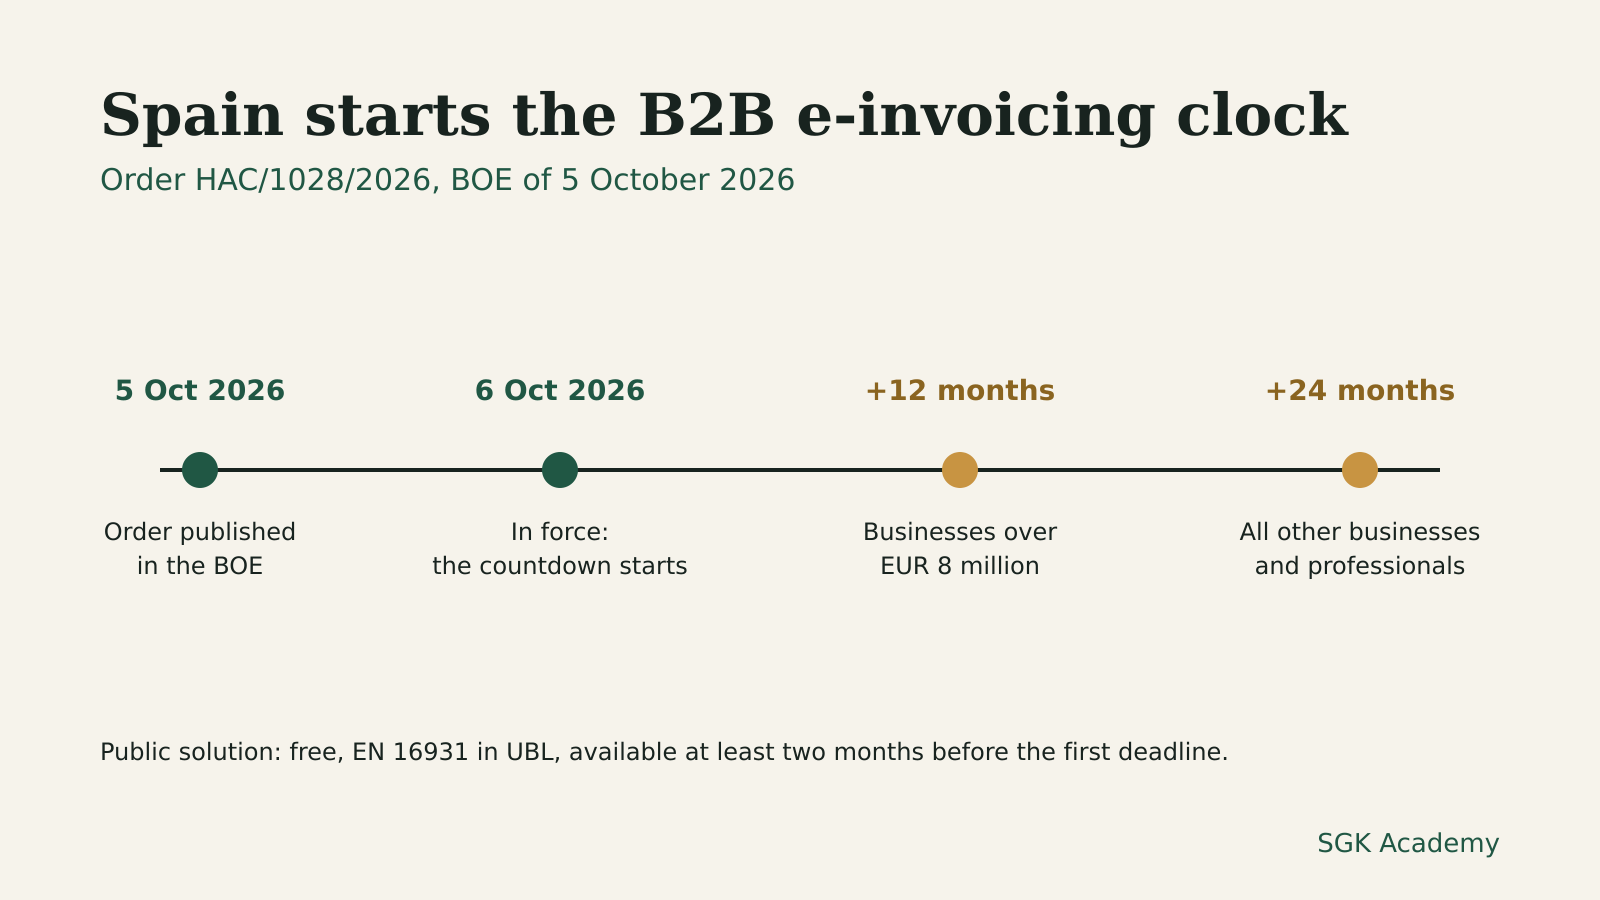
Timeline of Spain's B2B e-invoicing rollout: Order HAC/1028/2026 published in the BOE on 5 October 2026, in force on 6 October 2026, obligation for businesses over EUR 8 million 12 months later and for all other businesses and professionals 24 months later.
e-invoicing ·

Spain Starts the Clock on Mandatory B2B E-Invoicing

Order HAC/1028/2026 is in force from 6 October 2026: 12 or 24 months until Spanish B2B e-invoices are mandatory.
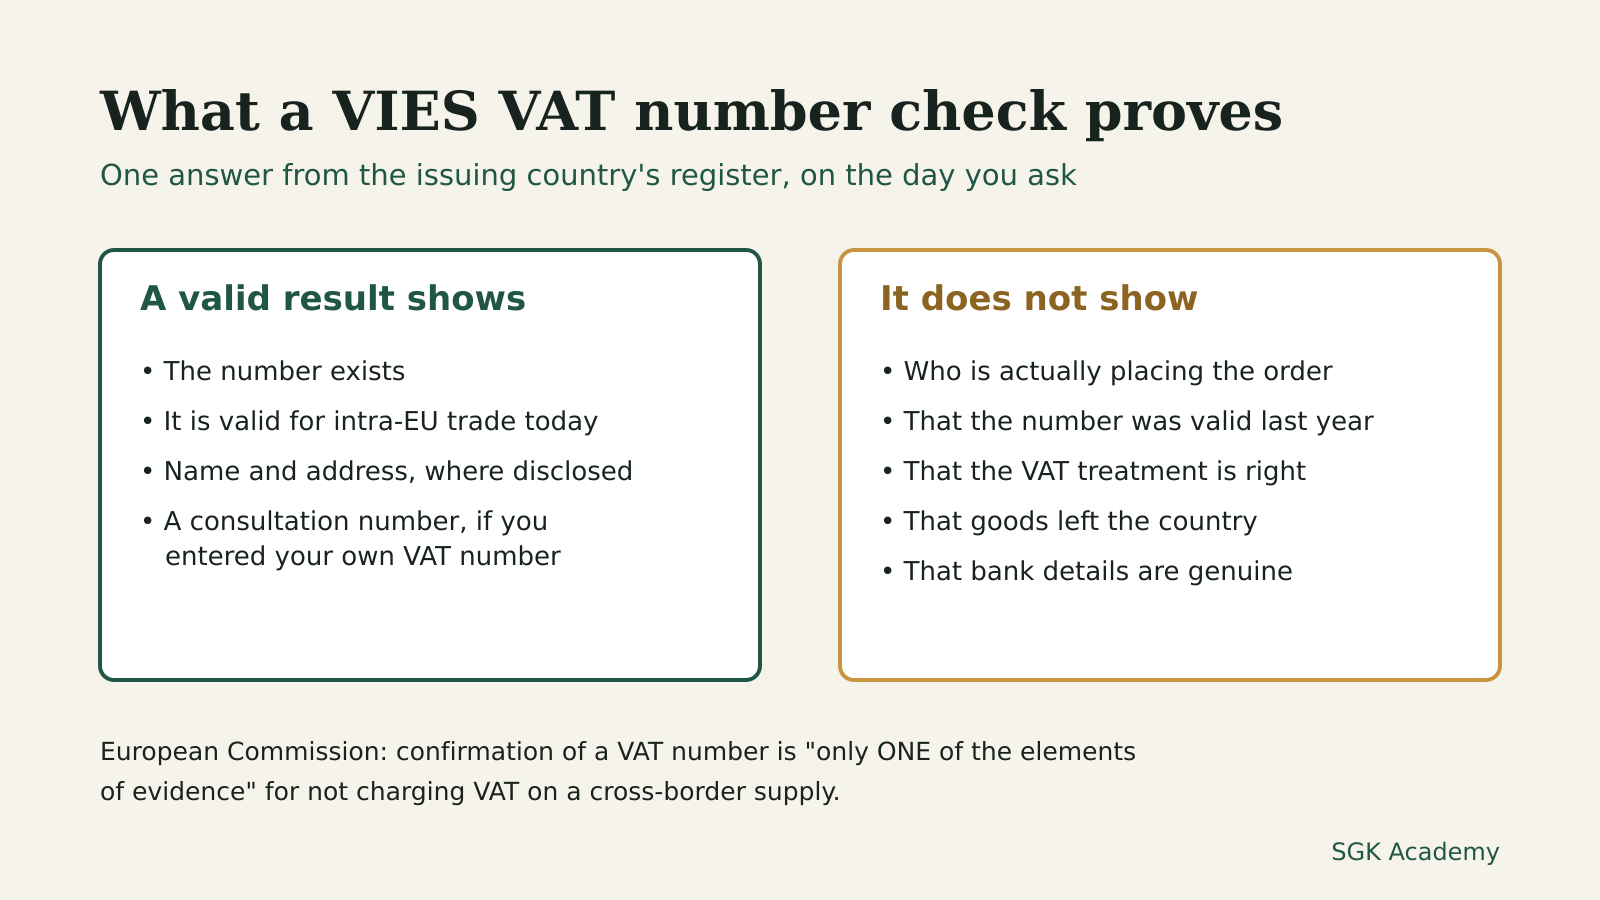
Diagram comparing what a valid VIES VAT number check shows (the number exists, is valid for intra-EU trade today, name and address where disclosed, a consultation number) with what it does not show (who places the order, past validity, correct VAT treatment, goods leaving the country, genuine bank details).
VAT ·

VIES VAT Number Check: What a Valid Result Proves

A valid VIES result lets you treat a customer as a business. How to run a check you can prove later, and its limits.
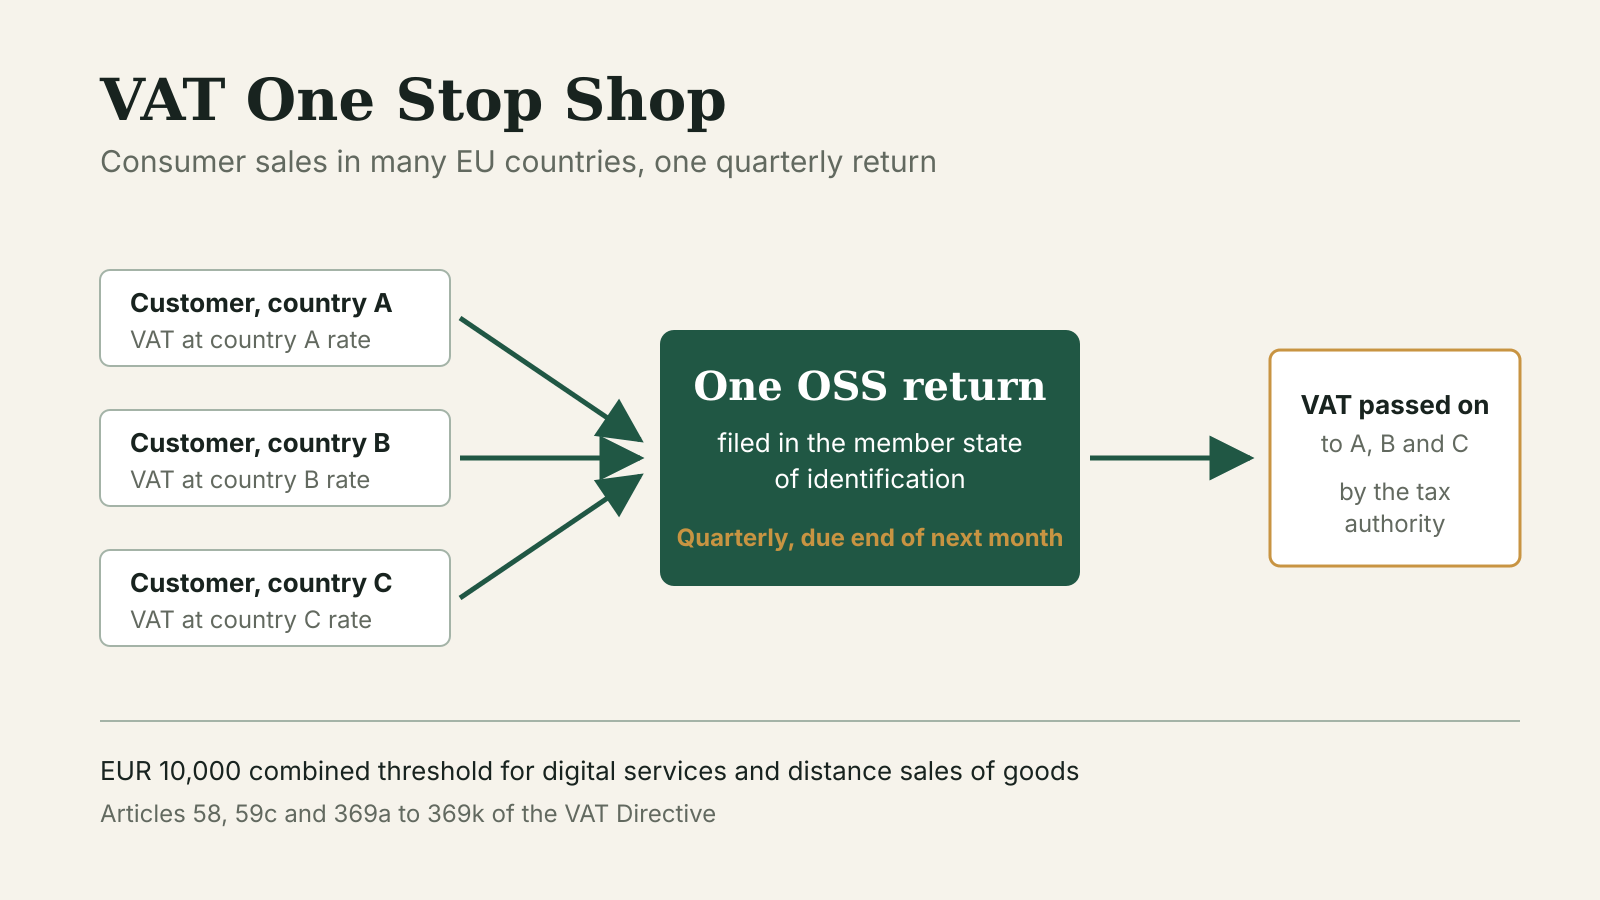
Diagram of the VAT One Stop Shop: sales to consumers in countries A, B and C, each at that country's VAT rate, go into one quarterly OSS return filed in the member state of identification, which passes the VAT on.
VAT ·

VAT One Stop Shop (OSS): One Return for EU Consumer Sales

How the EU One Stop Shop that replaced MOSS works, the EUR 10,000 threshold and what changes in 2027.

SGK Academy

What are you looking for?

Search a topic, product or question