
Money & Finance
Understand cash flow, business finances and the currency of your real-world obligations.
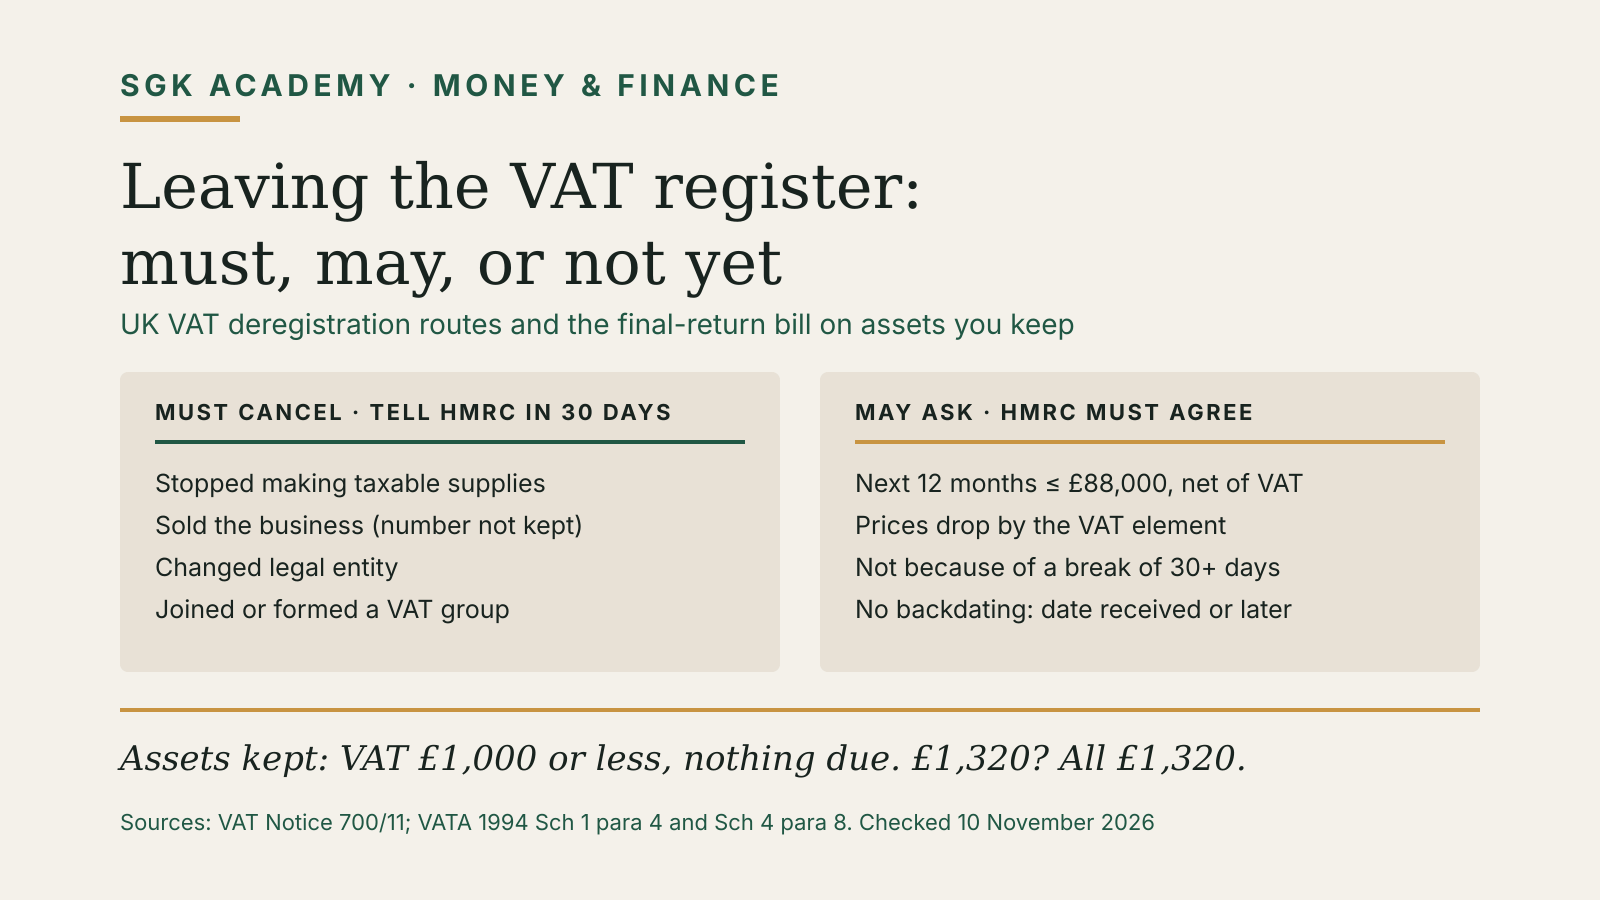
VAT Deregistration: When You Must Cancel and When You May
When you must cancel UK VAT registration, when you may below £88,000, and the VAT due on assets you keep.
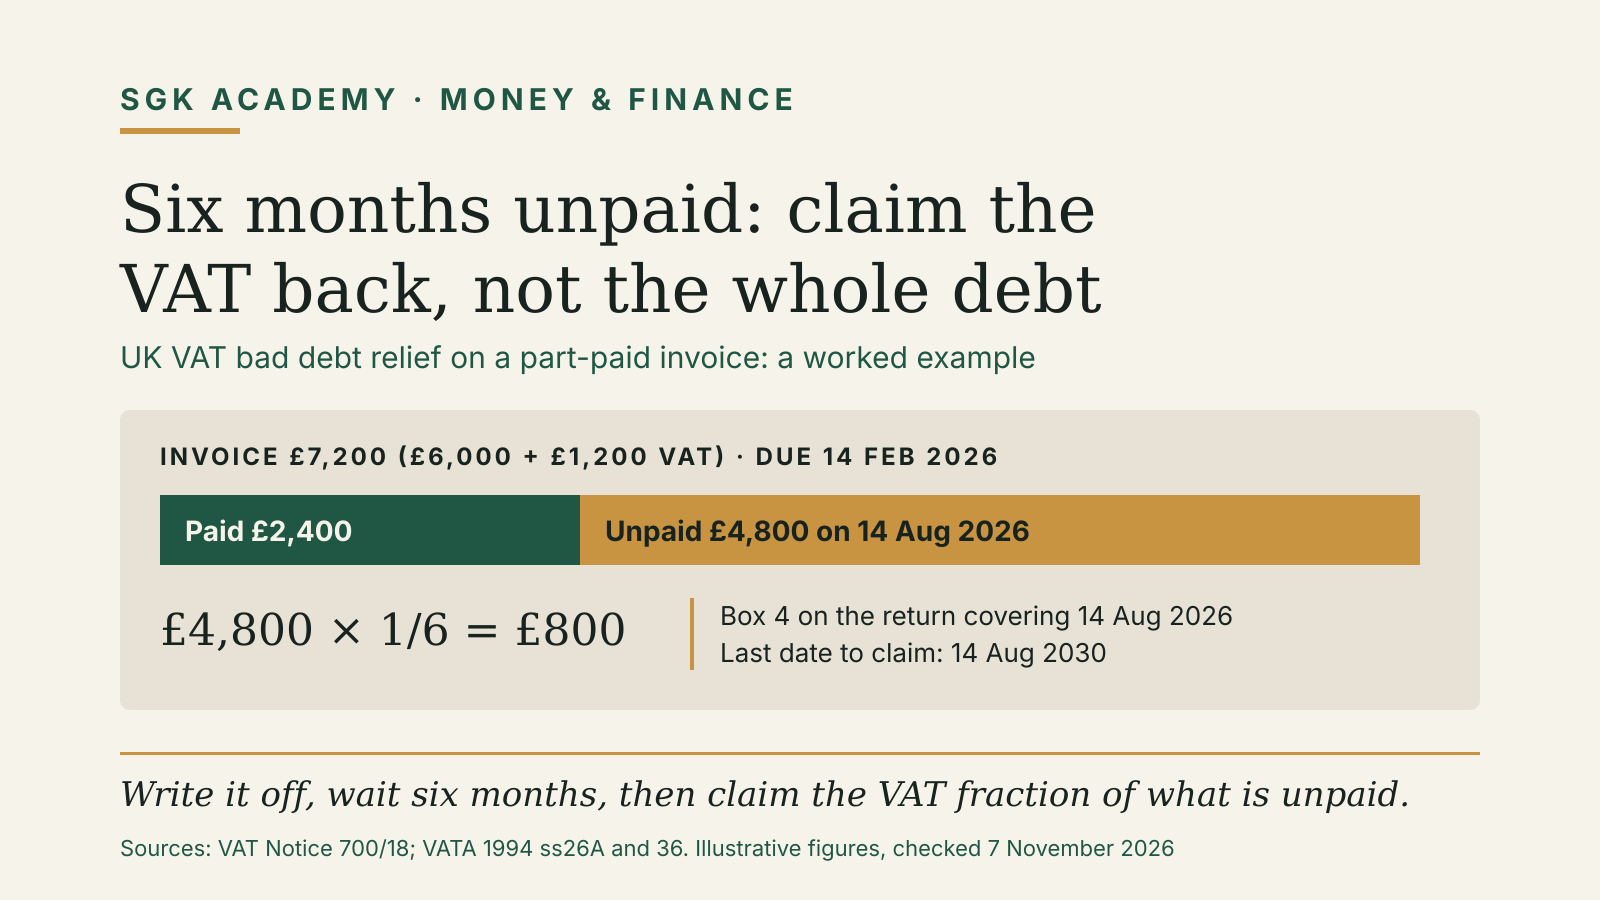
Bad Debt Relief VAT: Reclaiming VAT on an Unpaid Invoice
Reclaim the VAT on an unpaid invoice once it is six months overdue: conditions, VAT Return boxes and a worked example.
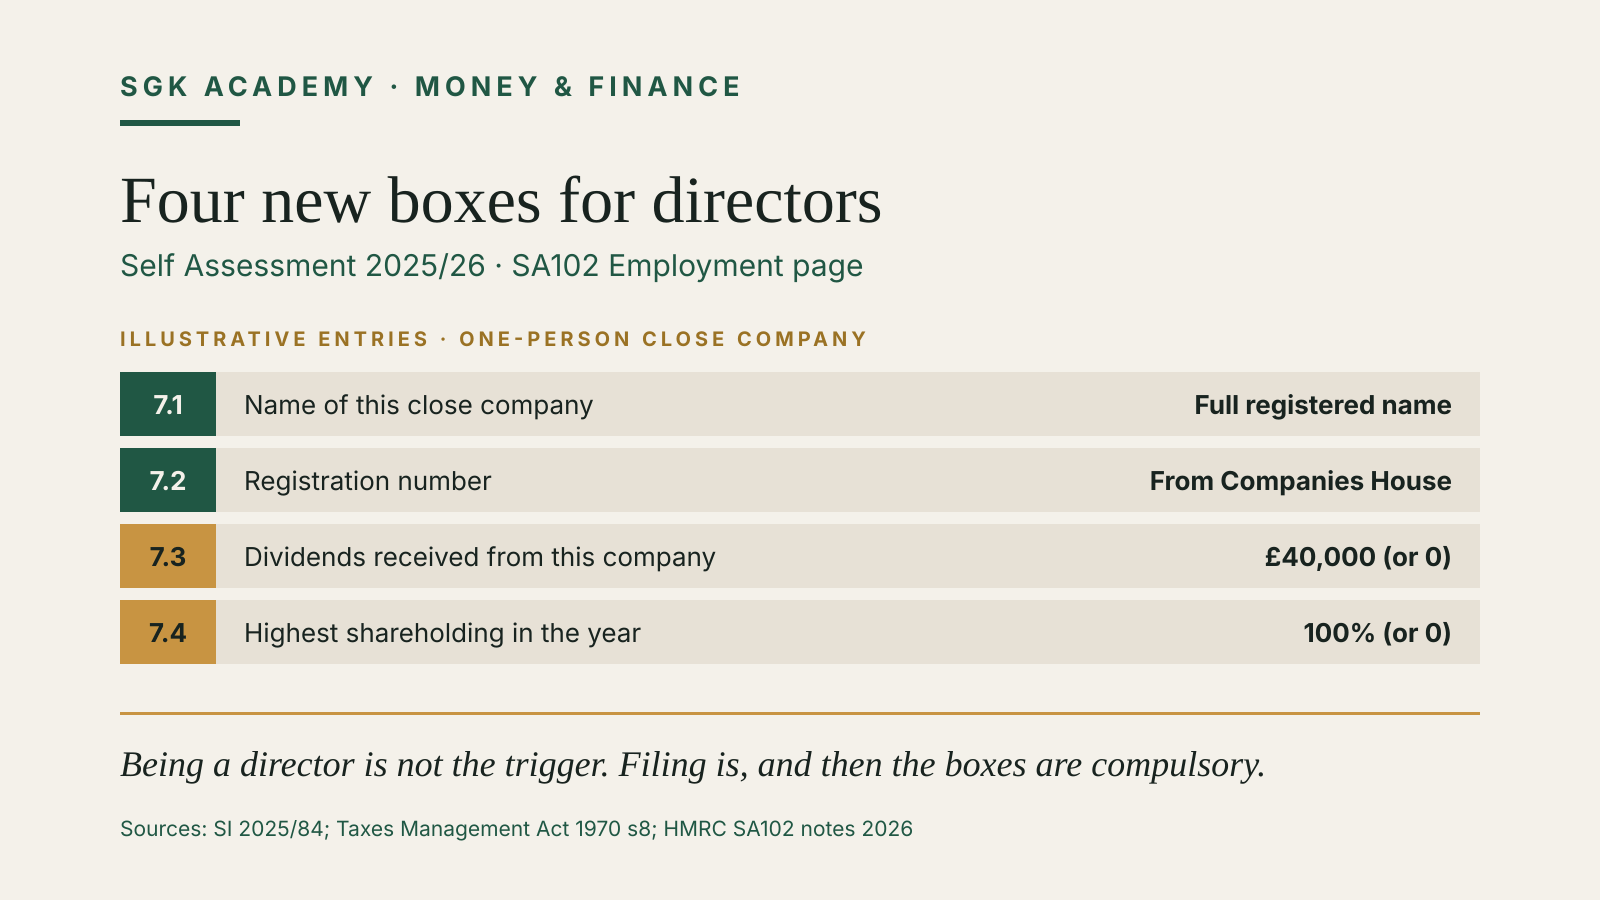
Do Company Directors Need to Do Self Assessment? The 2025/26 Rules
When a UK company director must file Self Assessment, the £10,000 dividend line and the new 2025/26 SA102 boxes.
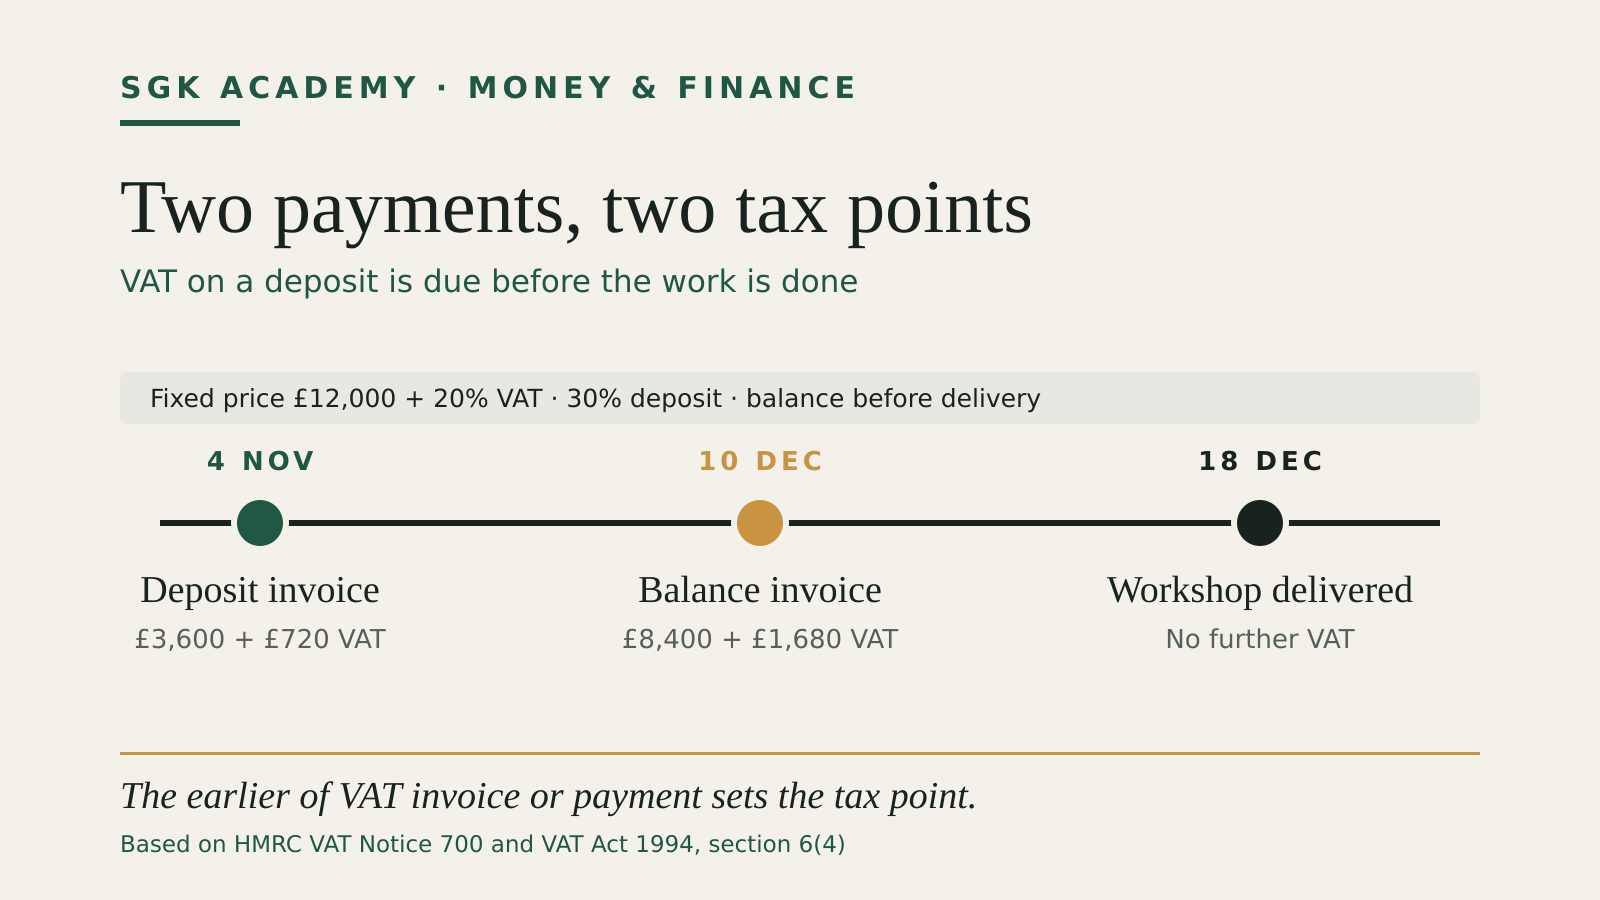
VAT on Deposits and Advance Payments
When a customer deposit creates a UK VAT tax point, how refundable security differs, and what to record.
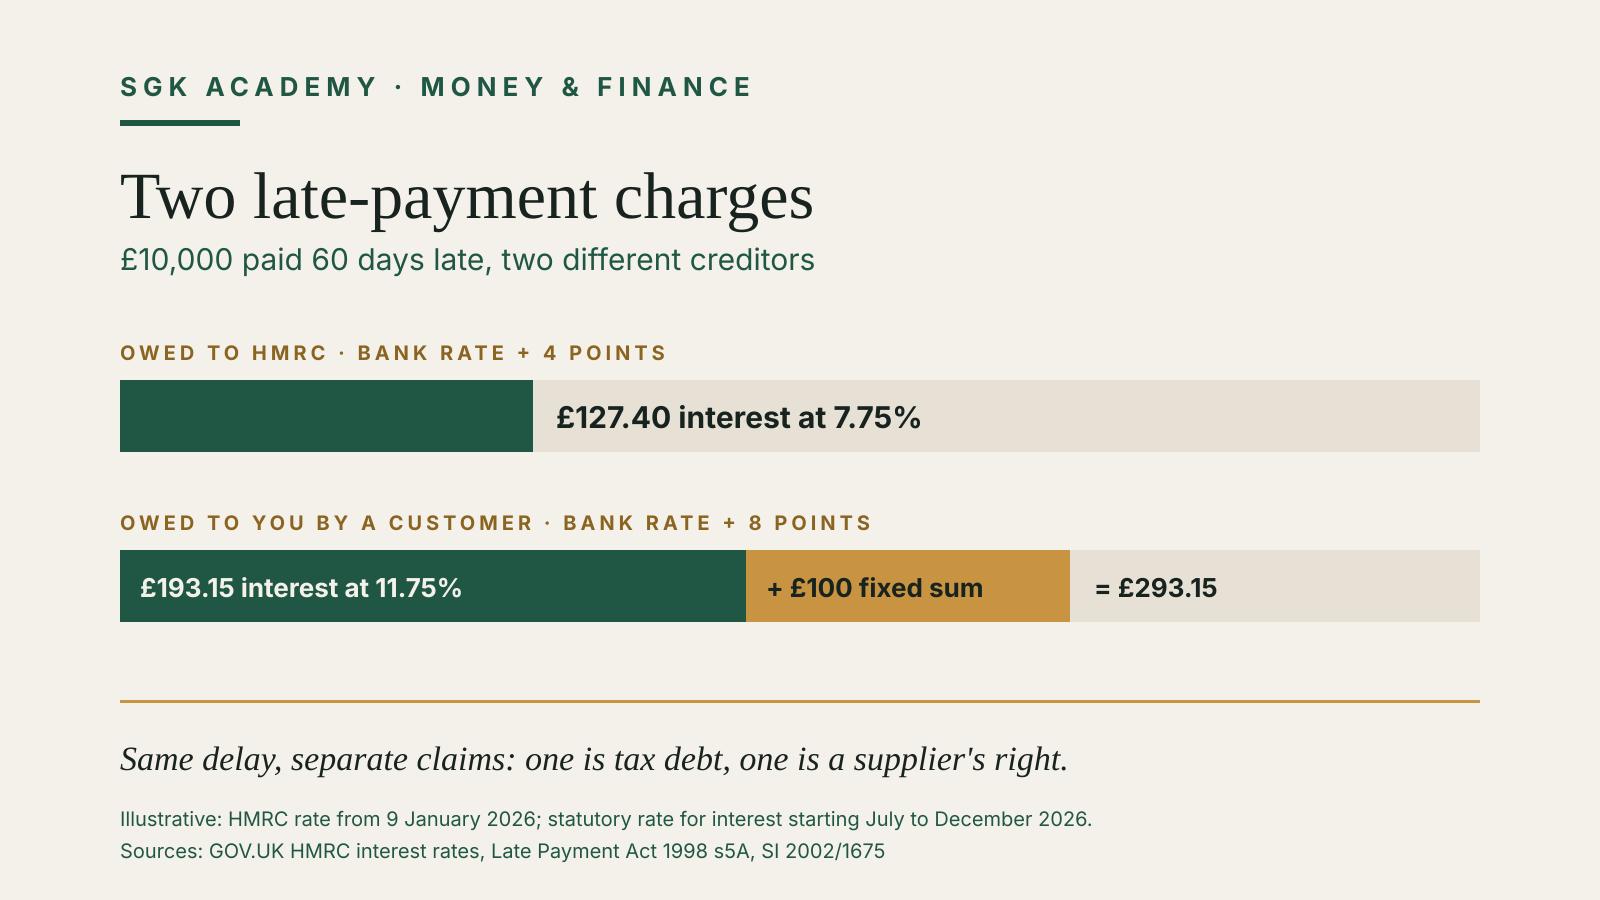
HMRC Late Payment Interest vs Statutory B2B Interest
Compare HMRC interest on late tax with statutory interest on an overdue business invoice.
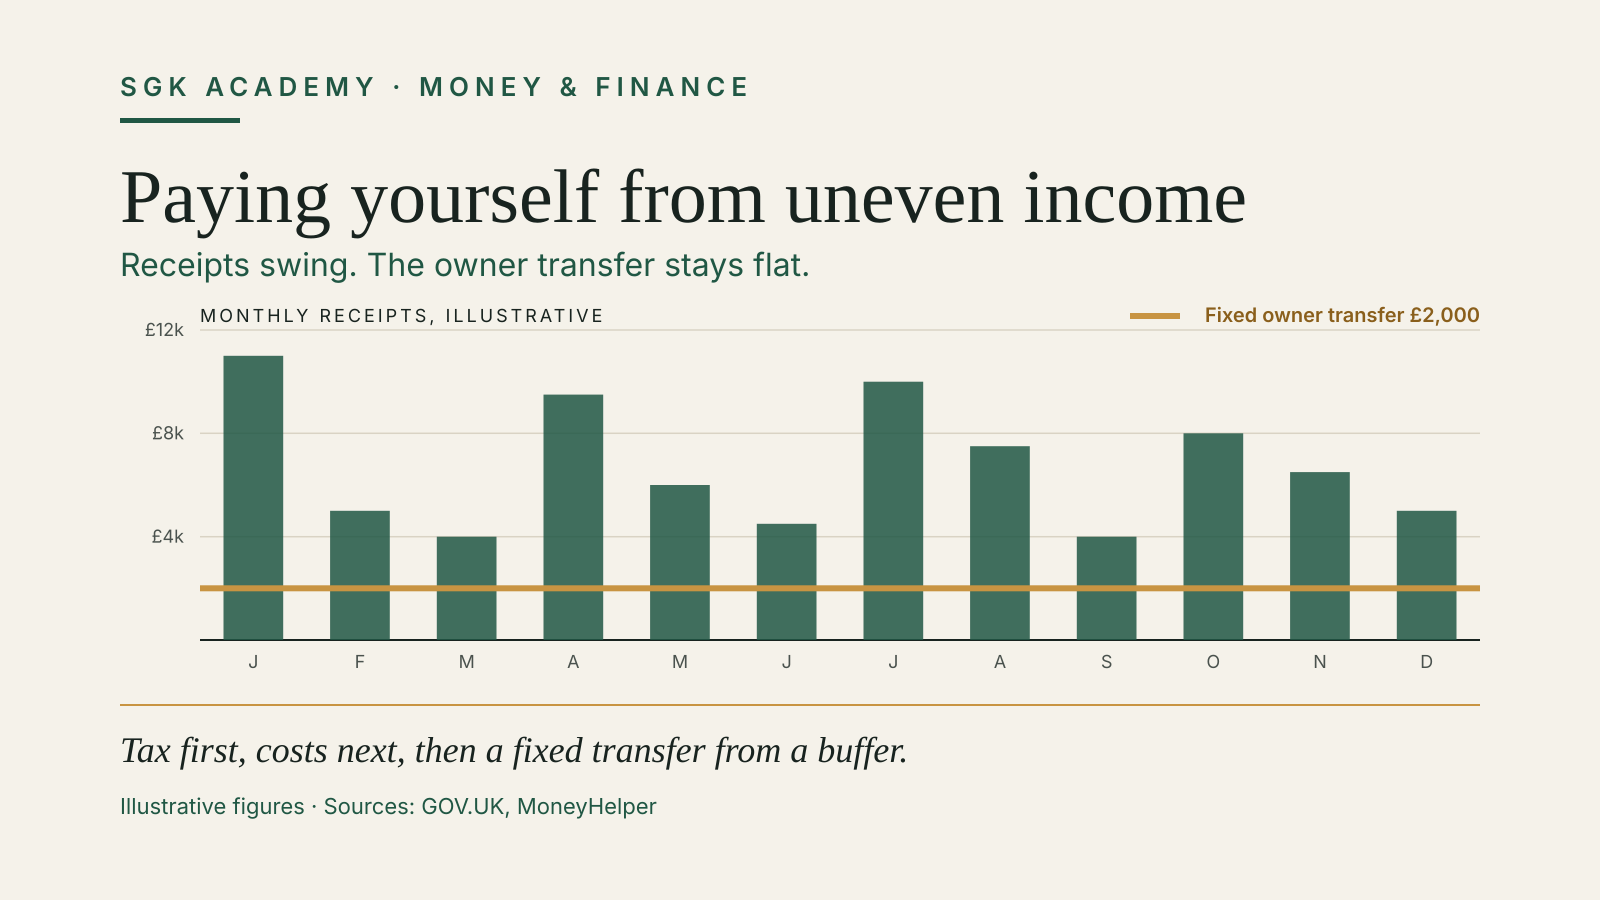
How to Pay Yourself From Irregular Income
Turn uneven business revenue into a steady owner transfer without draining taxes or operating cash.
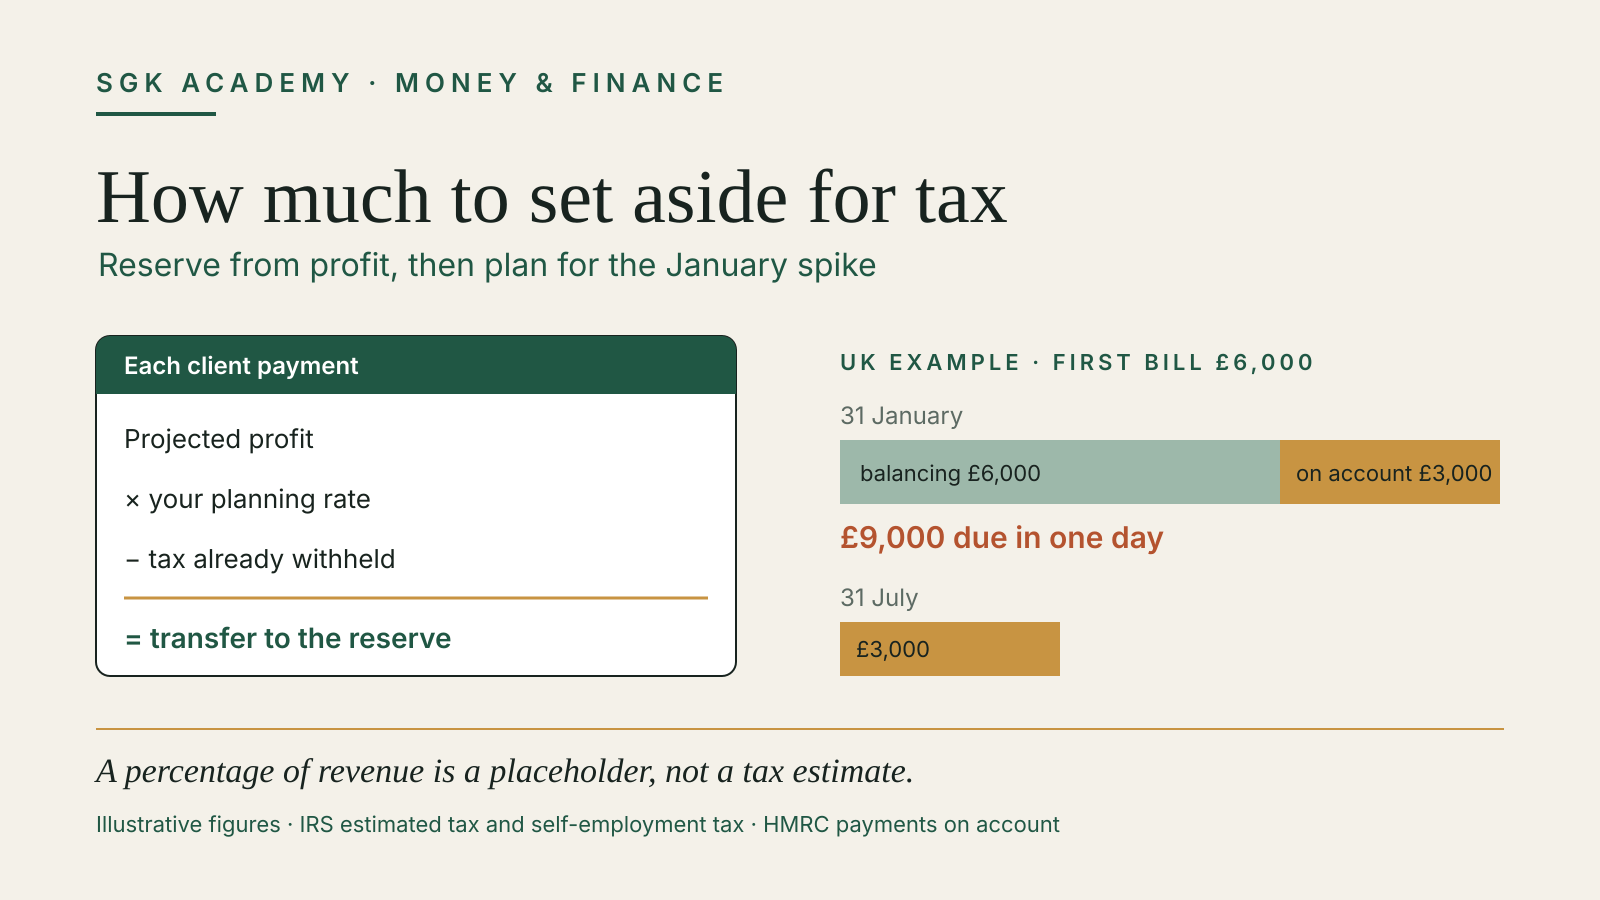
How Much to Set Aside for Tax as a Freelancer
Build a freelancer tax reserve from projected profit, official payment rules and quarterly true-ups.
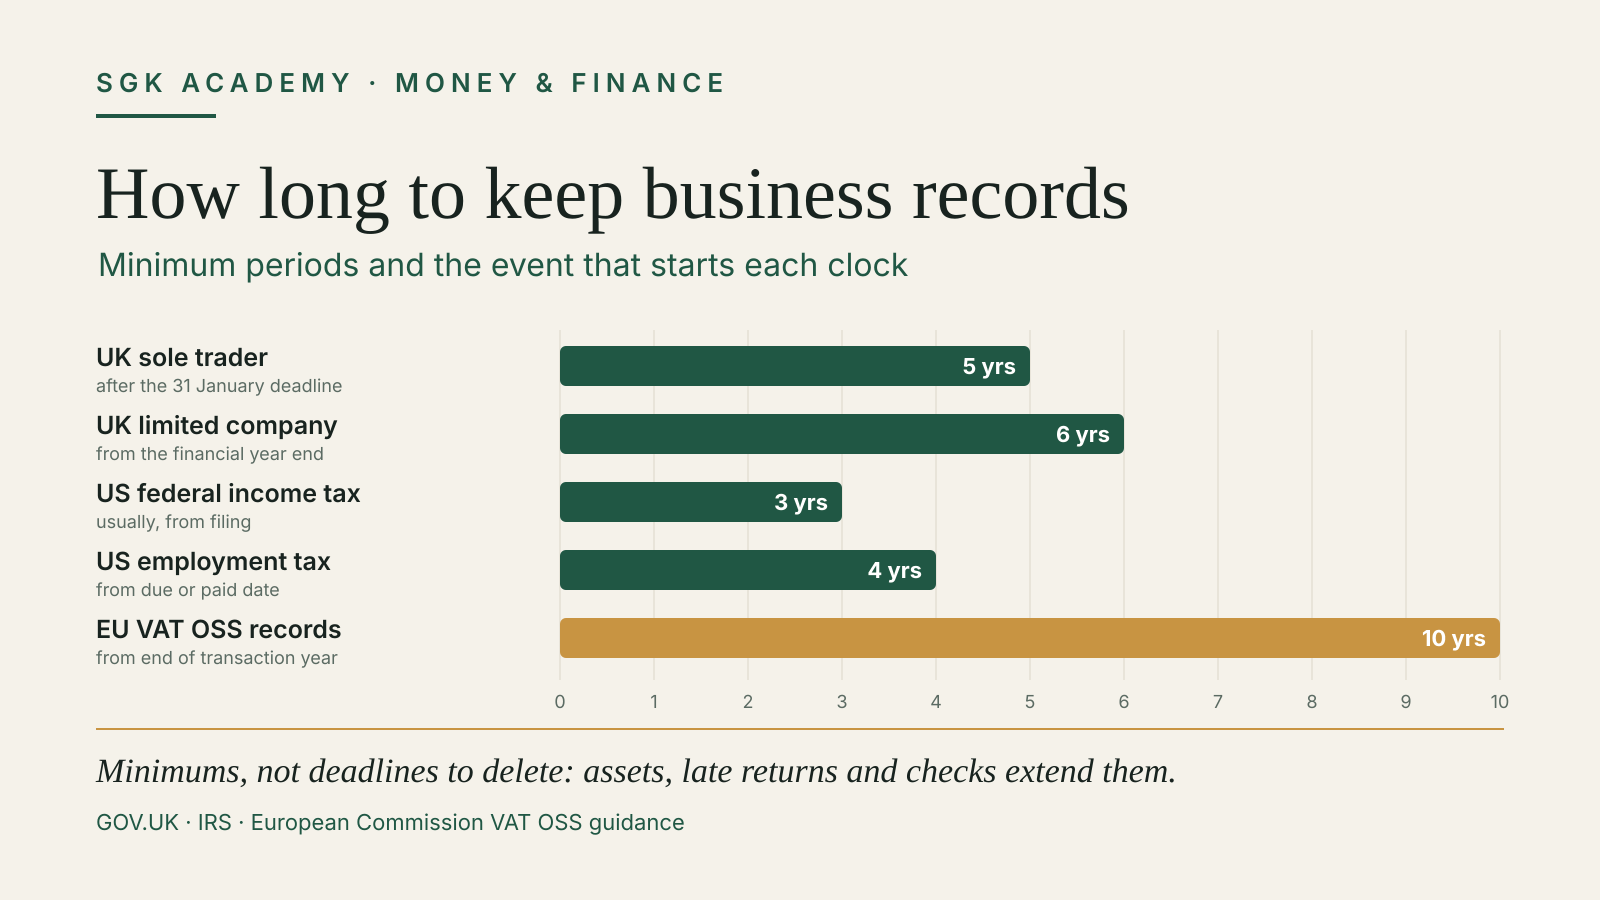
How Long to Keep Business Records: UK, US and EU OSS
A practical retention map for UK, US and EU VAT OSS business records, with the exceptions that extend it.
13-Week Cash Flow Forecast: A Small-Business Guide
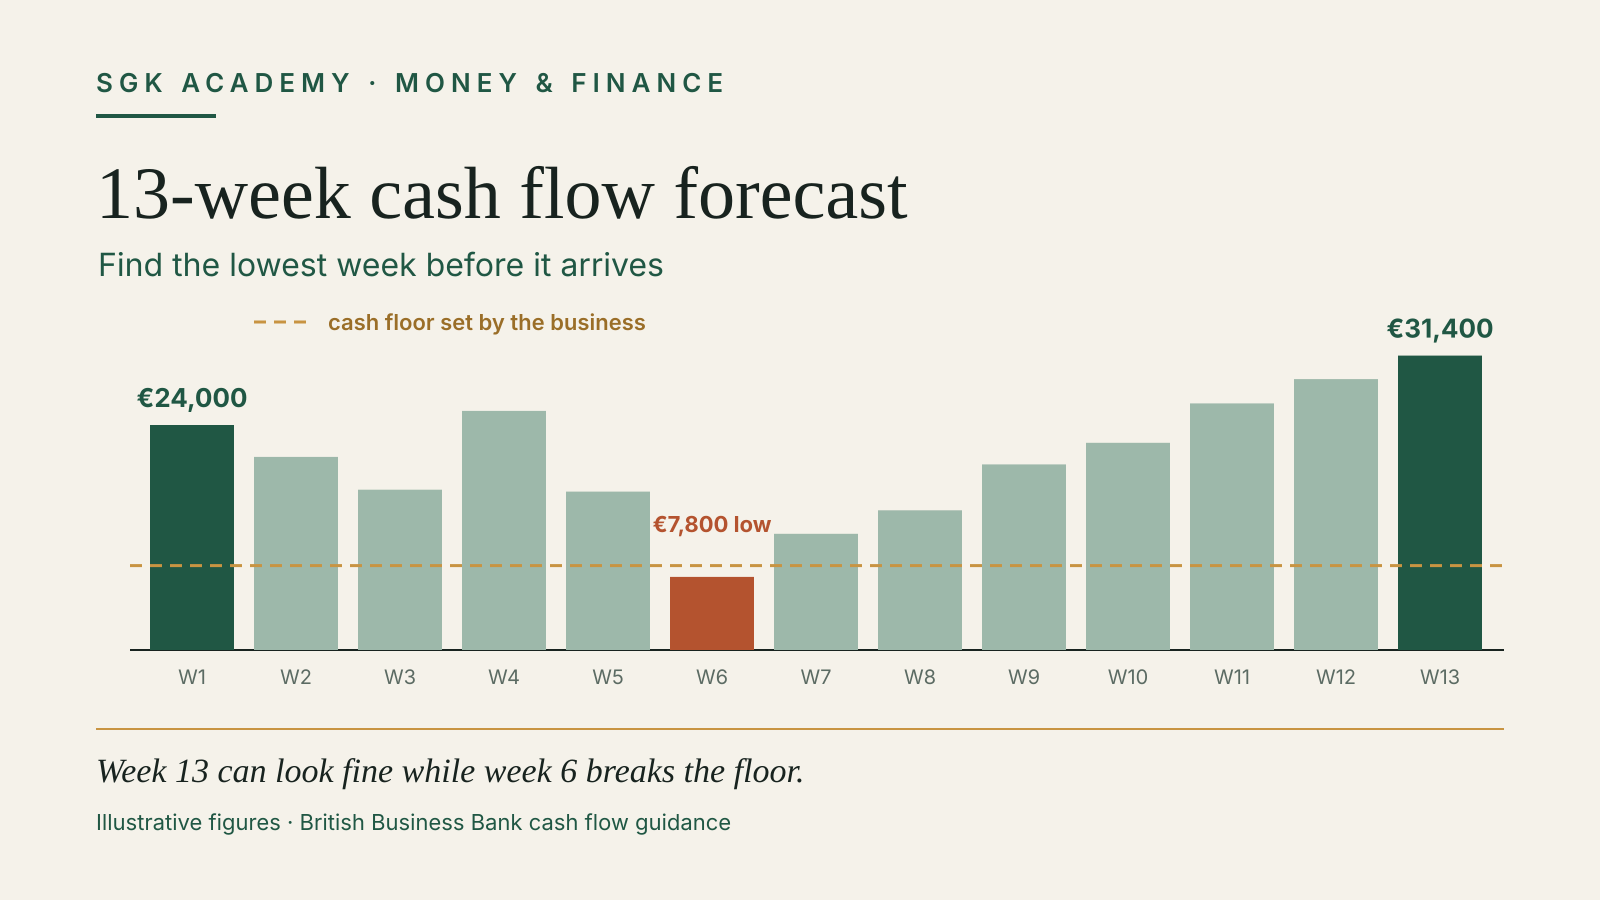
Build a rolling 13-week cash flow forecast, find the lowest cash week and turn gaps into dated actions.
Milestone Billing: Plan the Work and Payment Dates
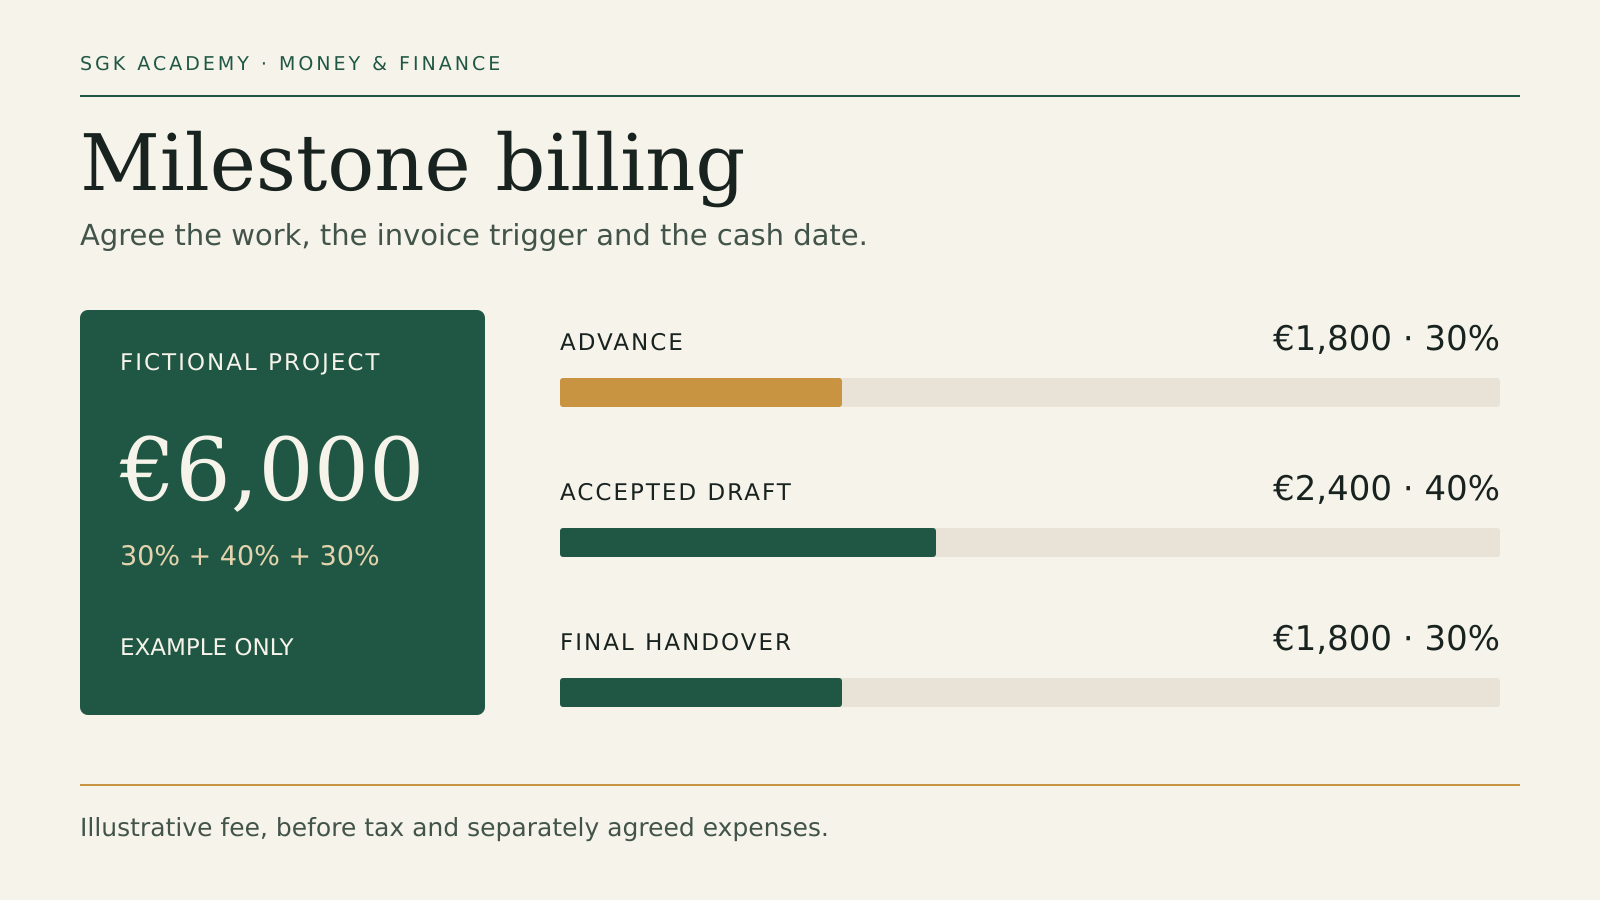
A practical milestone billing plan with acceptance checks, invoice dates and a clearly labelled €6,000 example.
Overdue Invoice Reminder: A Dated Chase Sequence
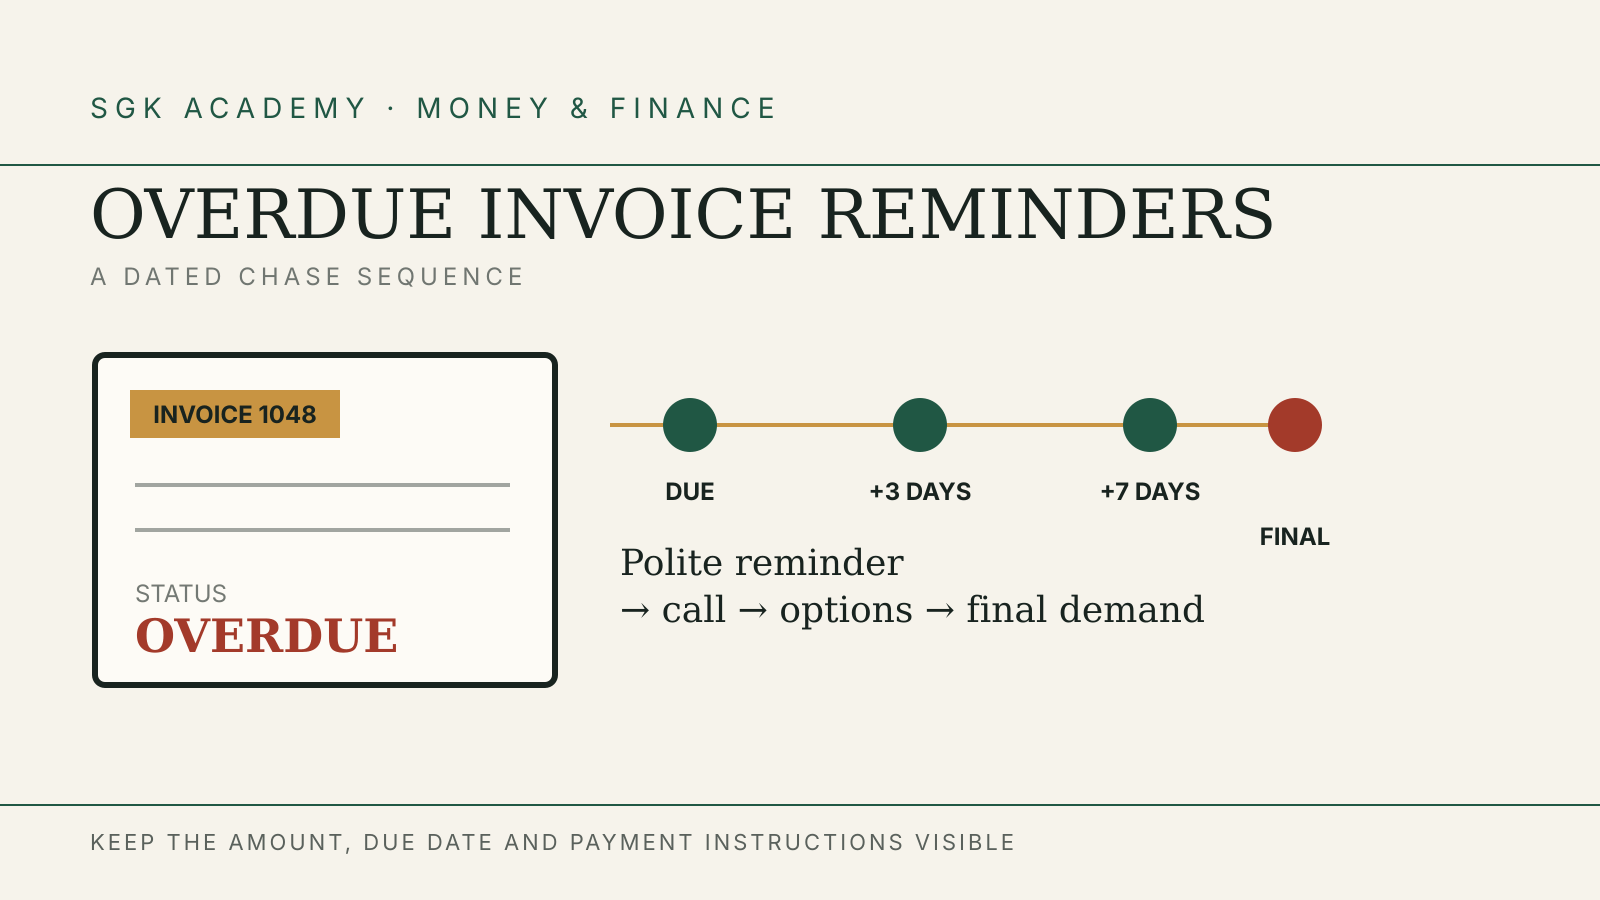
A dated reminder sequence to verify an overdue invoice, chase it, offer options and escalate accurately.
Late Payment Interest on B2B Invoices: UK and EU Guide
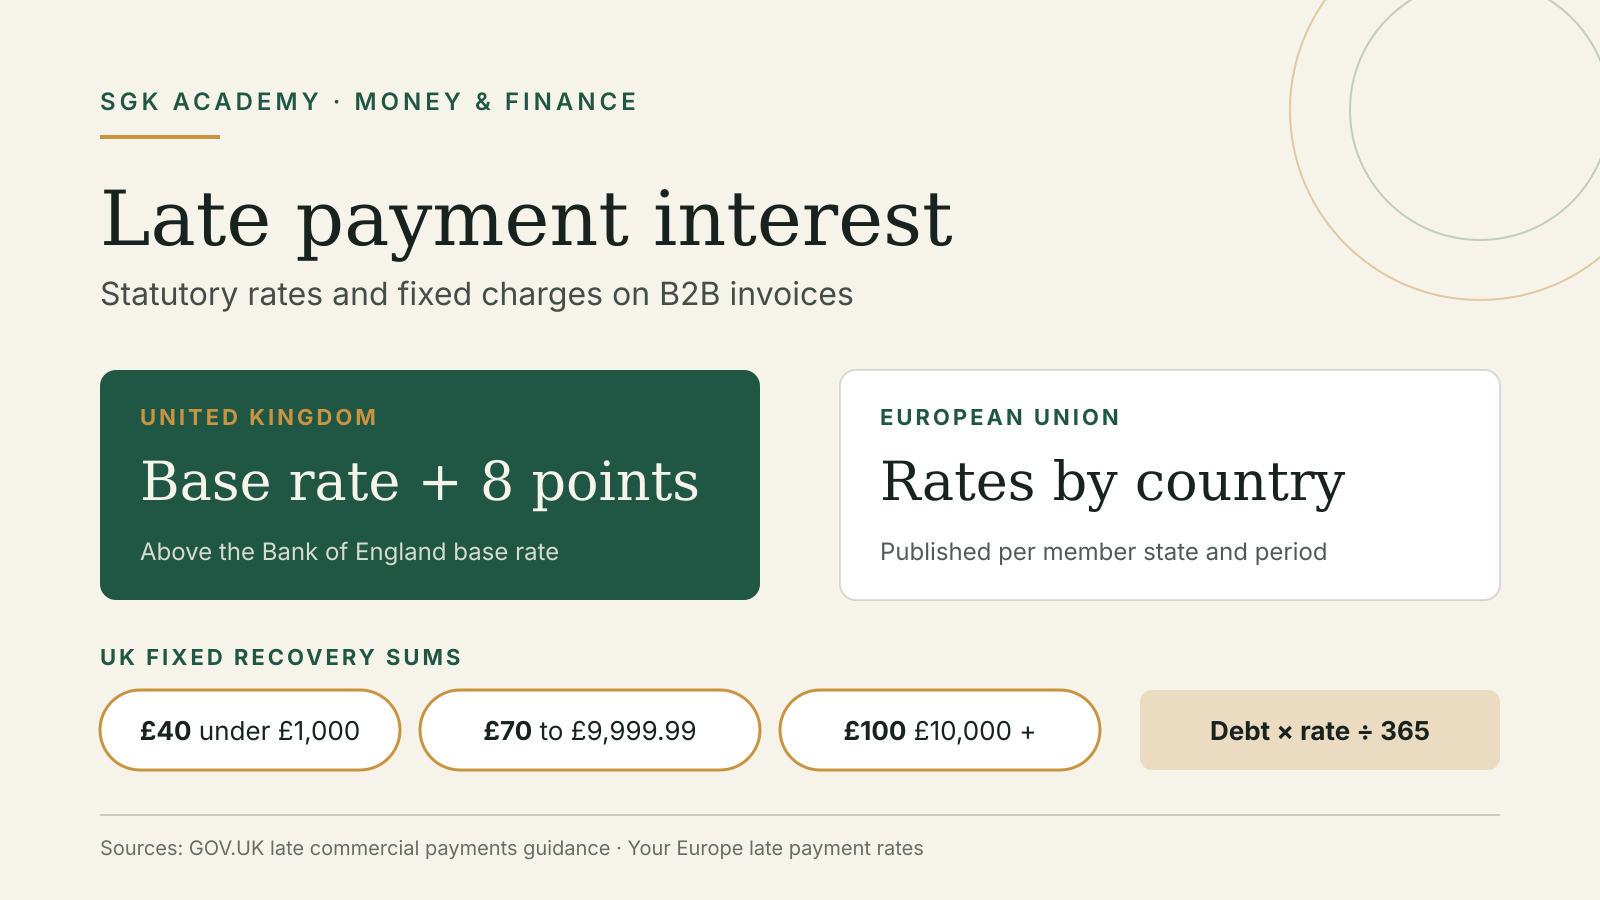
How to calculate UK and EU late-payment interest, fixed recovery charges and the correct start date.
US Estimated Tax Payments for Self-Employed People in 2026
How self-employed people calculate, schedule and record 2026 US federal estimated tax payments.
Making Tax Digital for Income Tax: Who Must Join and When
Check the MTD Income Tax thresholds, start dates, digital records and quarterly updates for sole traders and landlords.
Director's Loan Account: The Section 455 Deadline and Charge
Track a director's loan account, the nine-month deadline, section 455 tax and benefit-in-kind rules.
Salary vs Dividends for a UK Company Director in 2026/27
Compare salary and dividends for a UK director using 2026/27 tax, payroll and profit rules.
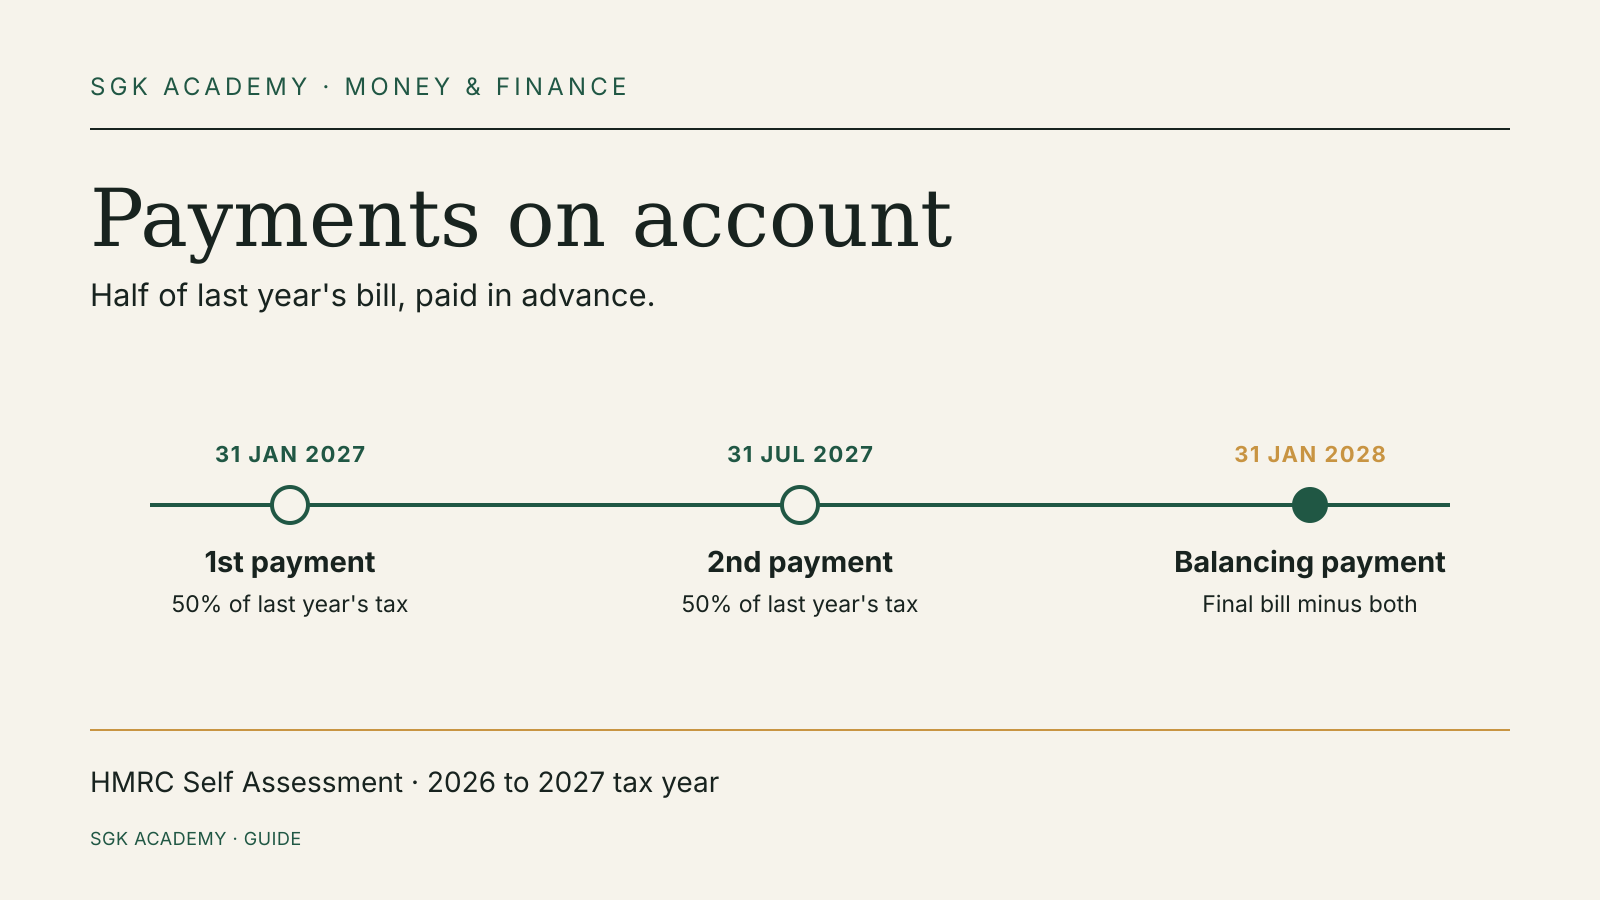
Payments on Account: How HMRC's Advance Tax Bills Work
Who pays them, why the first January bill is so large, and what a reduction costs if the estimate is wrong.
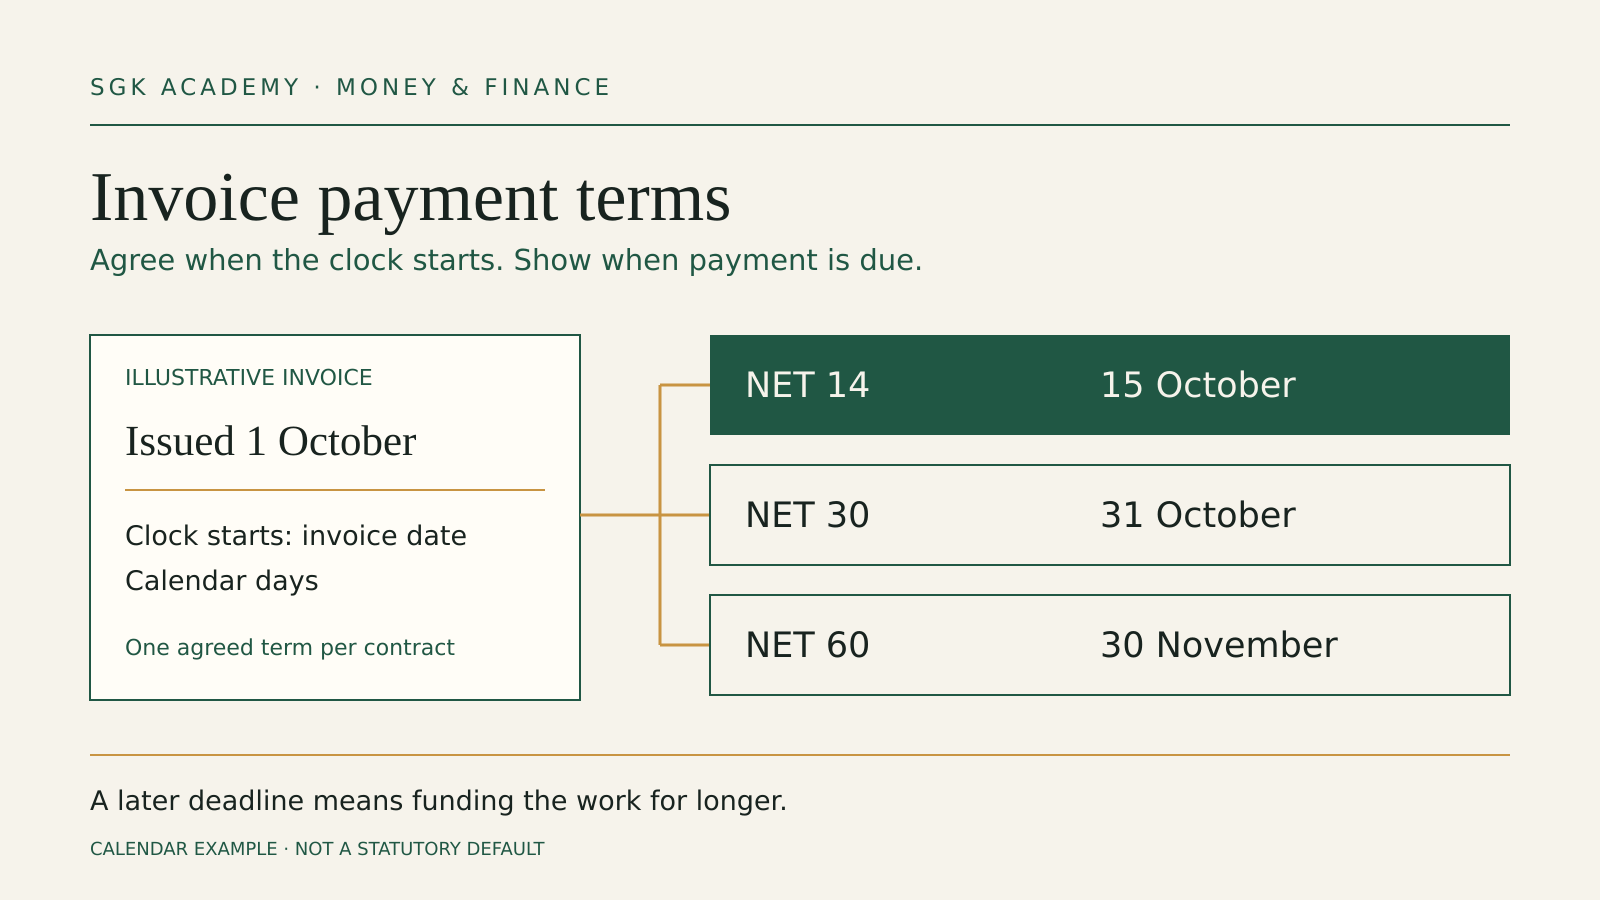
Invoice Payment Terms: Choose Net 14, 30 or 60
Choose invoice deadlines your cash flow can carry, with UK rules and worked examples for net 14, 30 and 60.
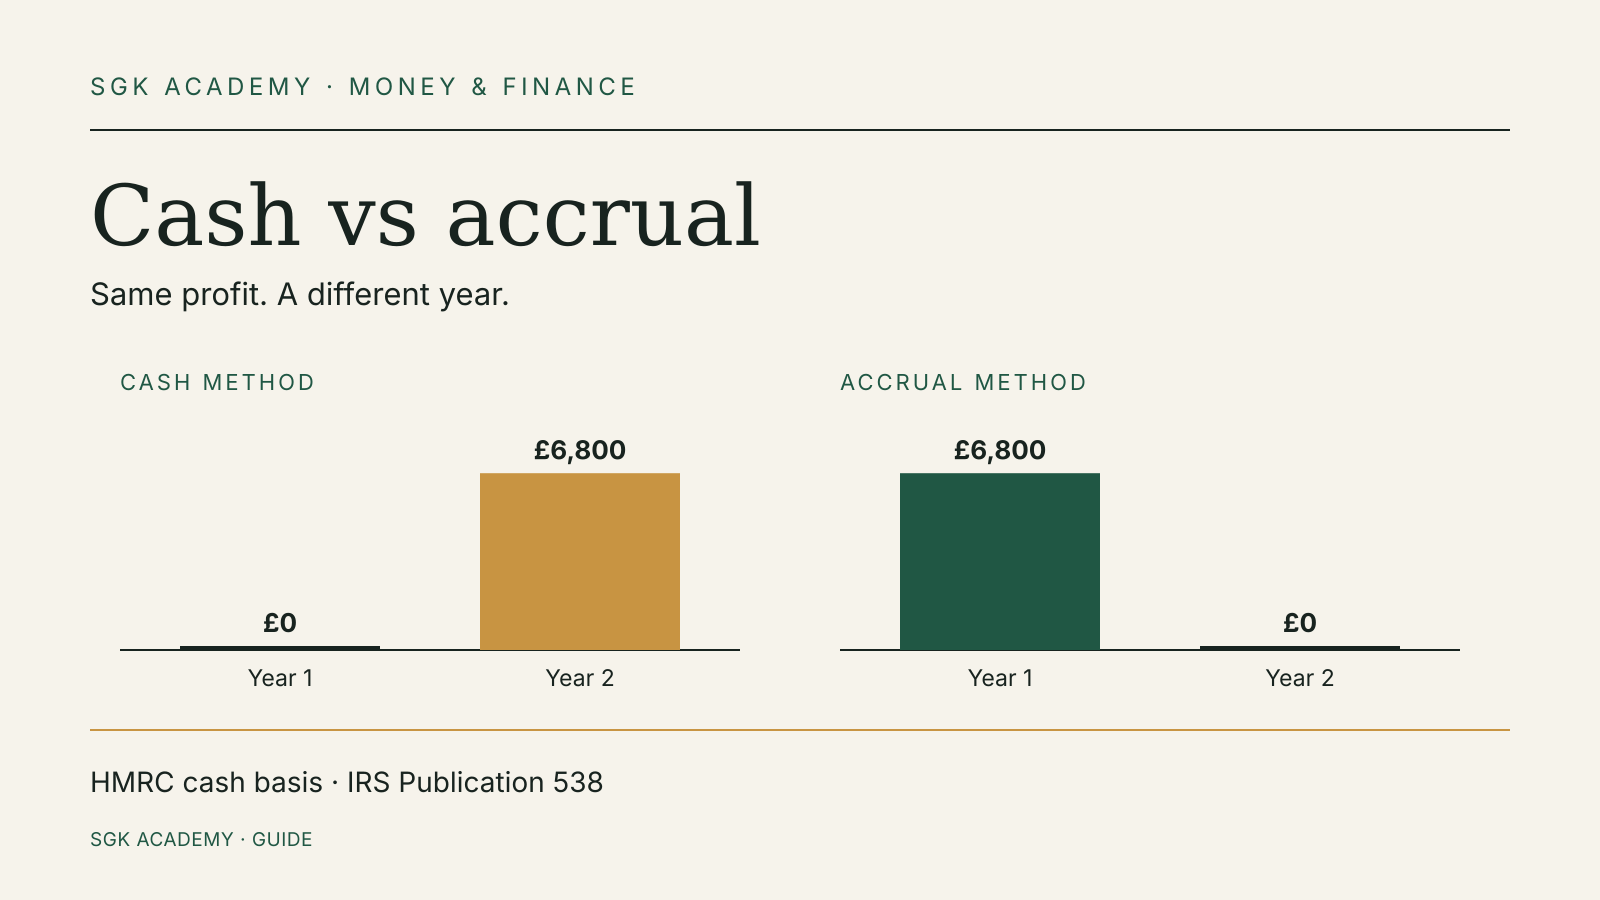
Cash vs Accrual Accounting for Small Businesses: UK and US Rules
Cash vs accrual accounting with a worked example and the UK and US rules on who may use each.
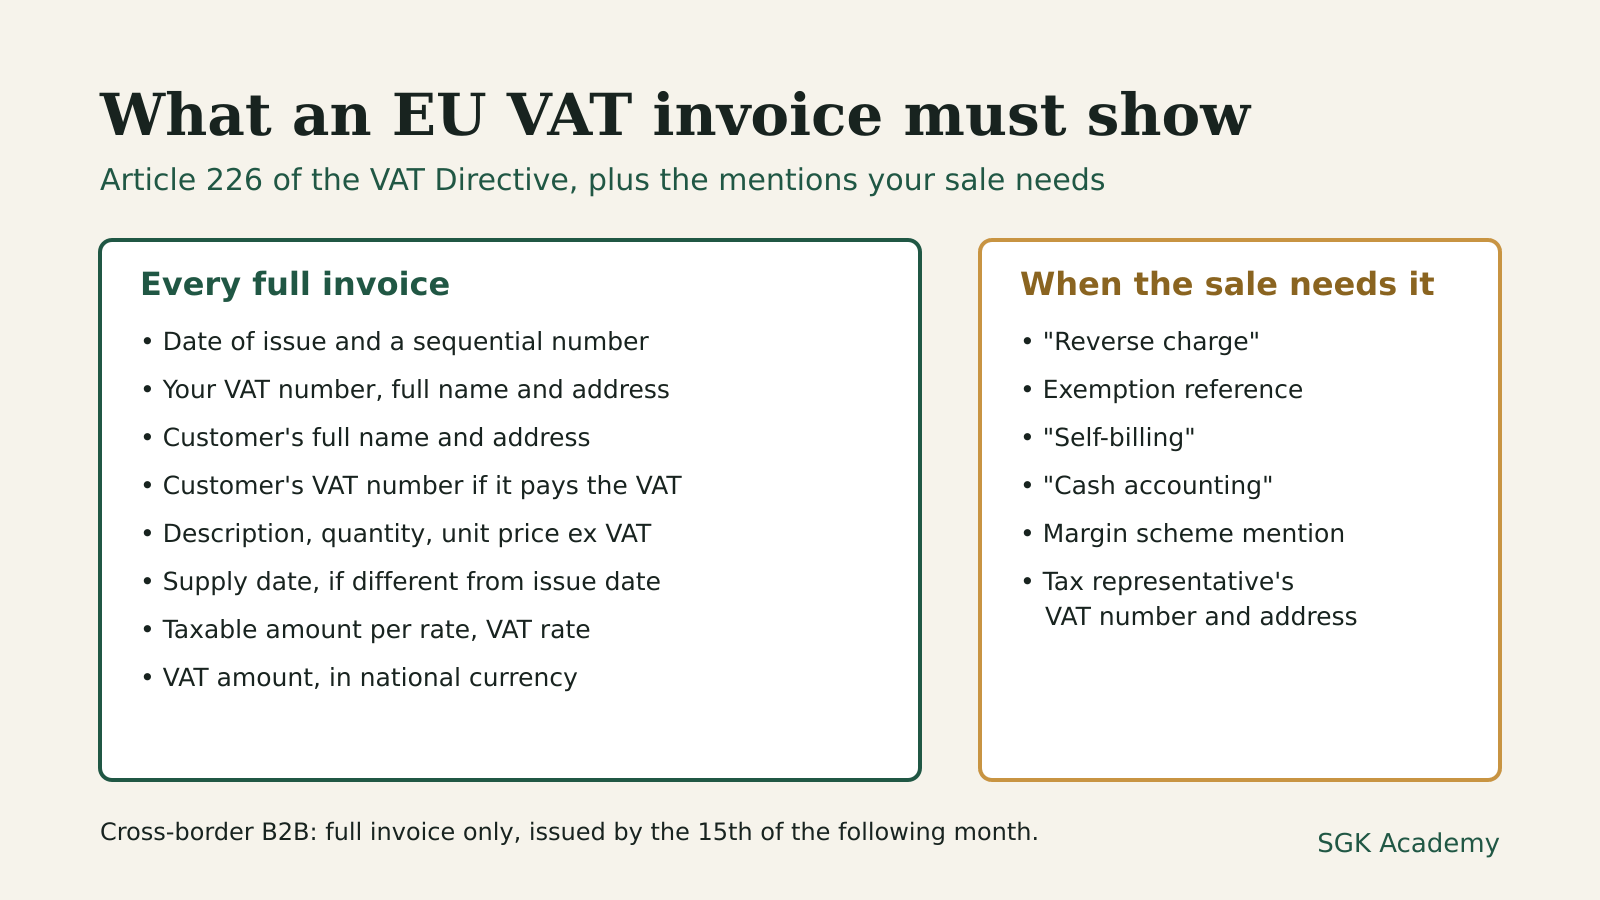
VAT Invoice Requirements: What an EU Invoice Must Show
The details every EU VAT invoice needs under Article 226, the extra mentions, simplified invoices and deadlines.
Profit vs Cash Flow: Why Growing Businesses Run Short
See how profitable work creates a cash gap, then build a weekly forecast.
Currency Risk When You Earn and Spend Abroad
Map currency mismatches by amount and date before choosing how to manage them.
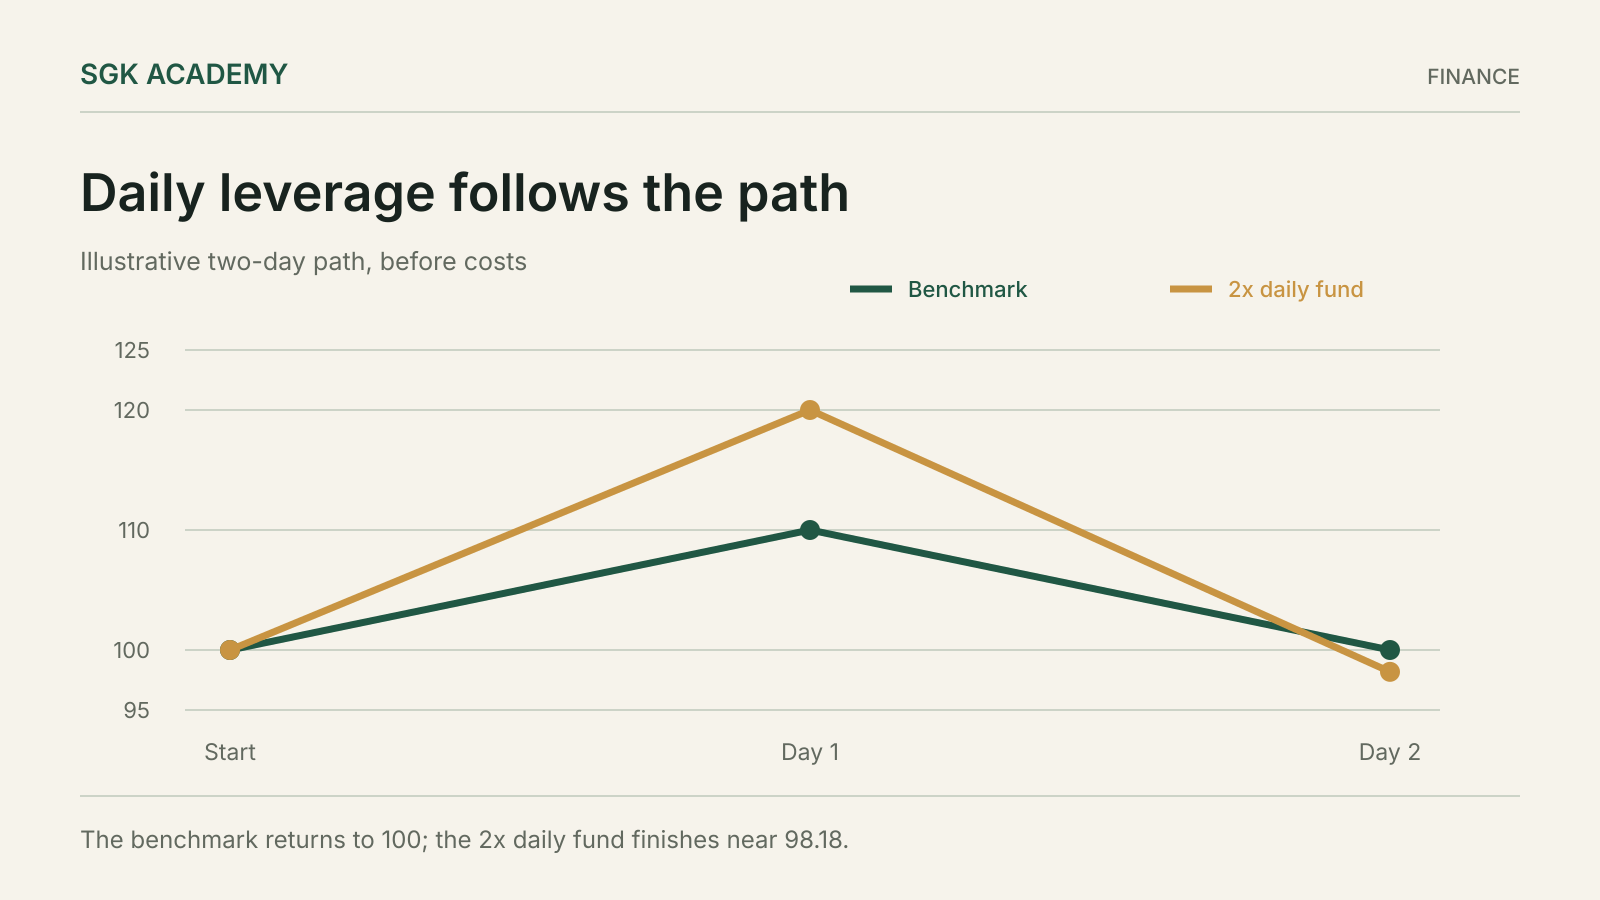
Leveraged ETFs: Why Daily Returns Do Not Add Up
Worked single-stock examples: why a 2x or −2x daily fund misses the simple multiple, and why new US funds stop at 2x.
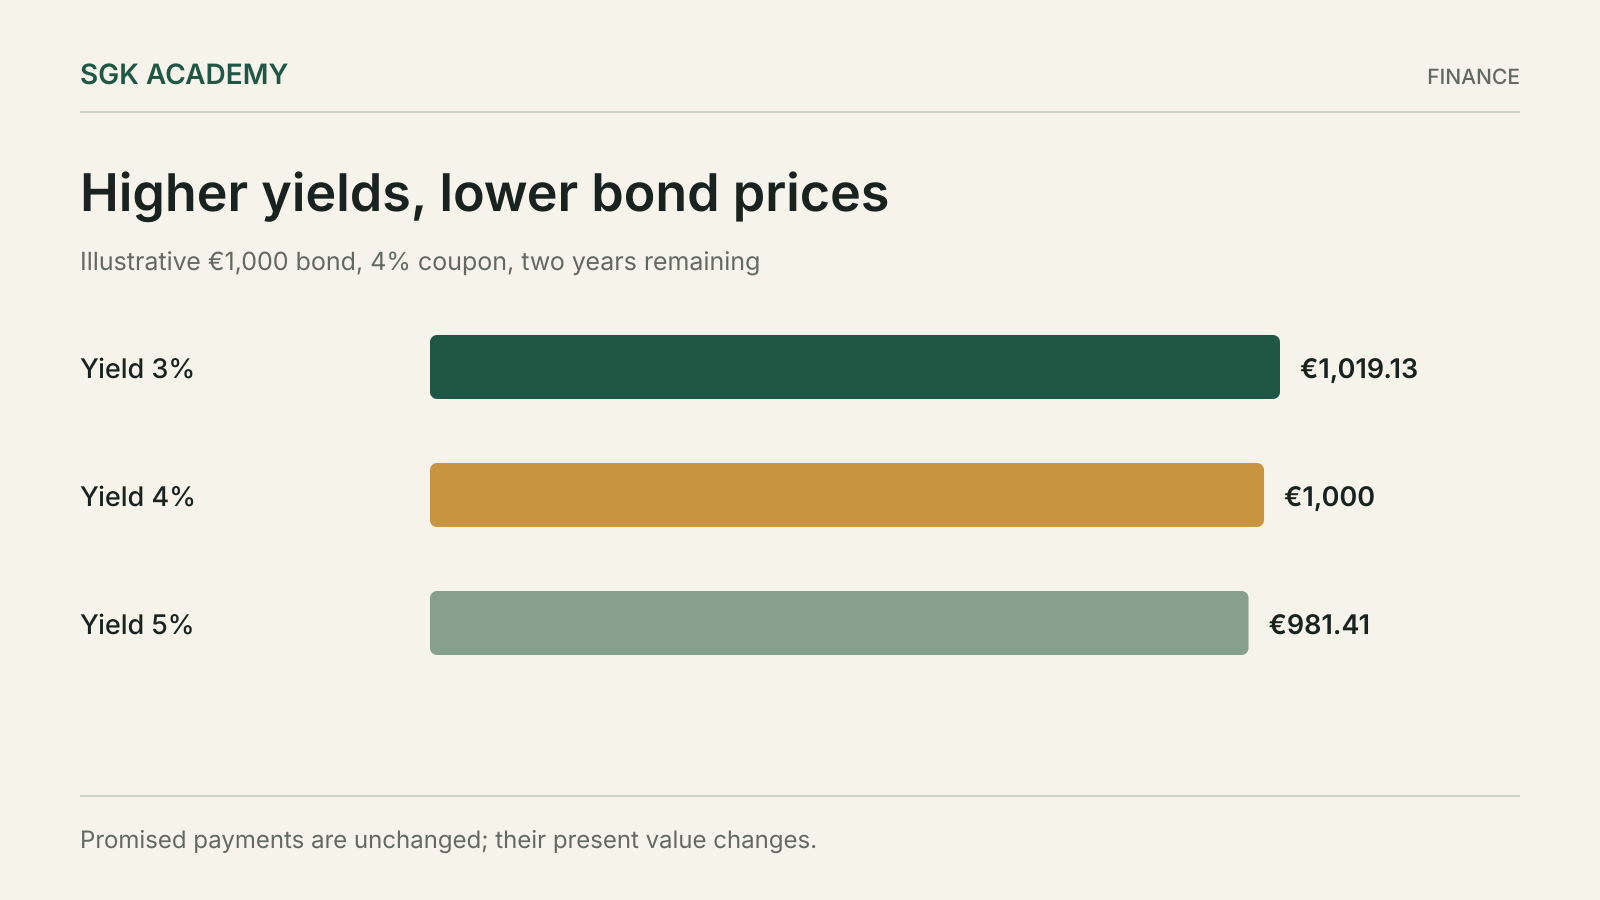
Bond Duration: Why Safe Debt Can Lose Value
Separate repayment risk from price risk before buying bonds for a future bill.
A useful financial explanation should help you read a statement, check a calculation or see where a budget becomes fragile. This desk focuses on those mechanics. The first guides show why profit and cash can move in different directions and how earning in one currency while spending another changes the amount available for bills.
The examples are deliberately explicit about dates, units and assumptions. You can reproduce the arithmetic and replace the fictional figures with your own planning inputs, while keeping professional accounting and financial decisions within their proper scope.
Begin with profit versus cash flow, then examine currency risk. For the cost of moving money, continue to international transfers.