
Fintech & Payments
Follow money from the sender’s account to the amount the recipient can use.

Rolling Reserve: How Payment Providers Hold Back Your Sales
How rolling reserves at Stripe, PayPal and Shopify work, and how much cash a 10% 90-day reserve ties up.
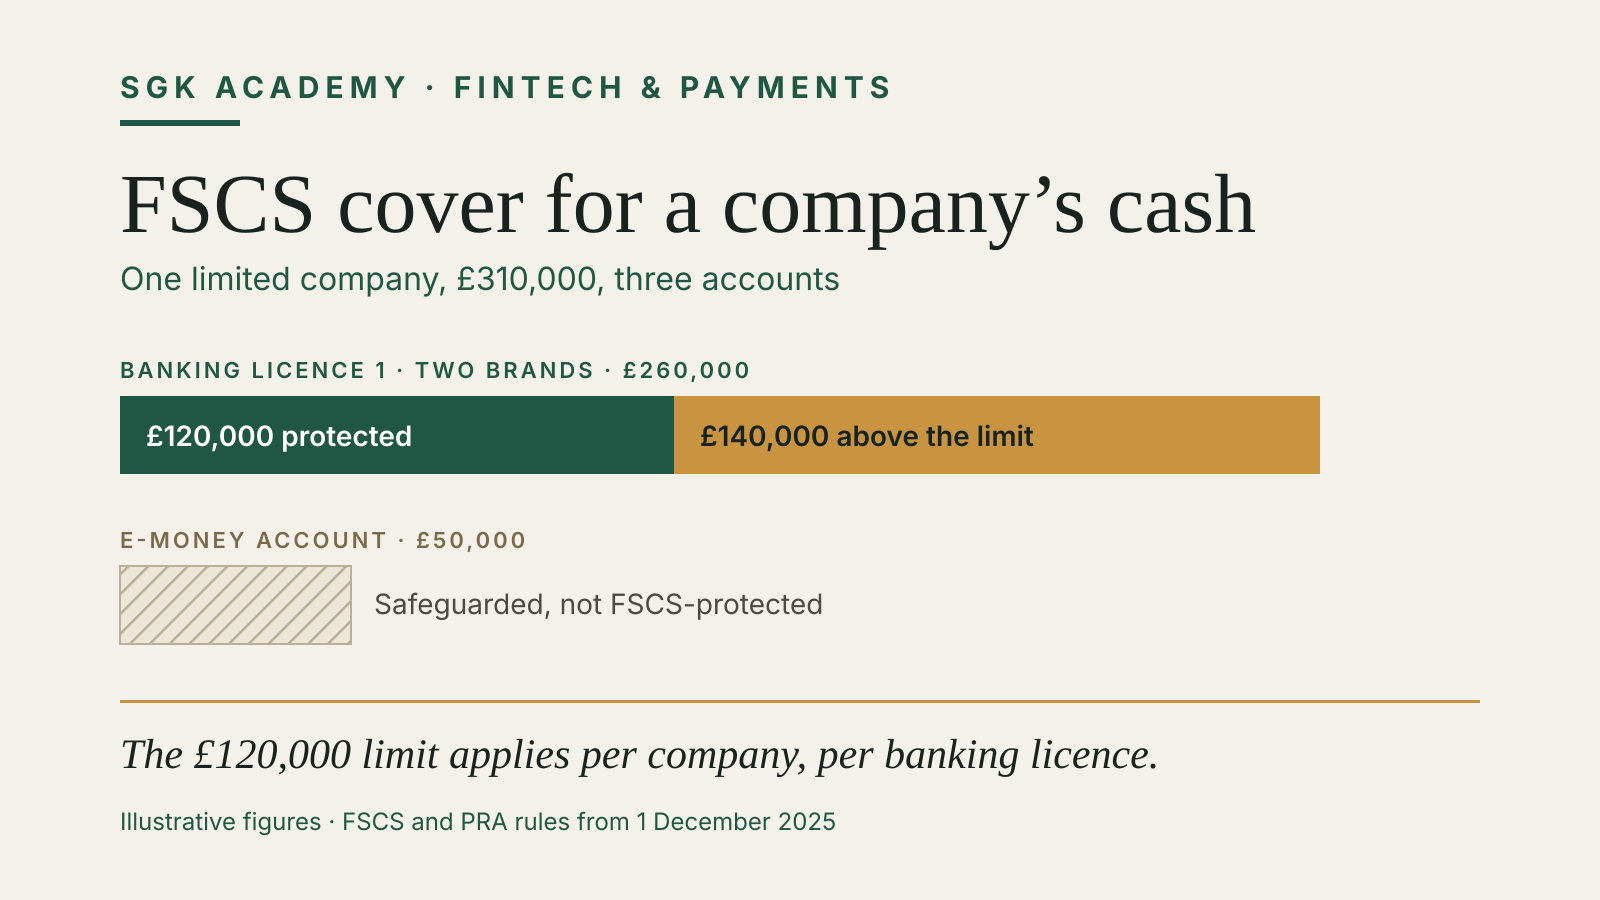
FSCS Protection for Business Accounts: How the £120,000 Limit Works
How FSCS protects a company's bank deposits up to £120,000, why shared licences cut cover and why e-money is excluded.
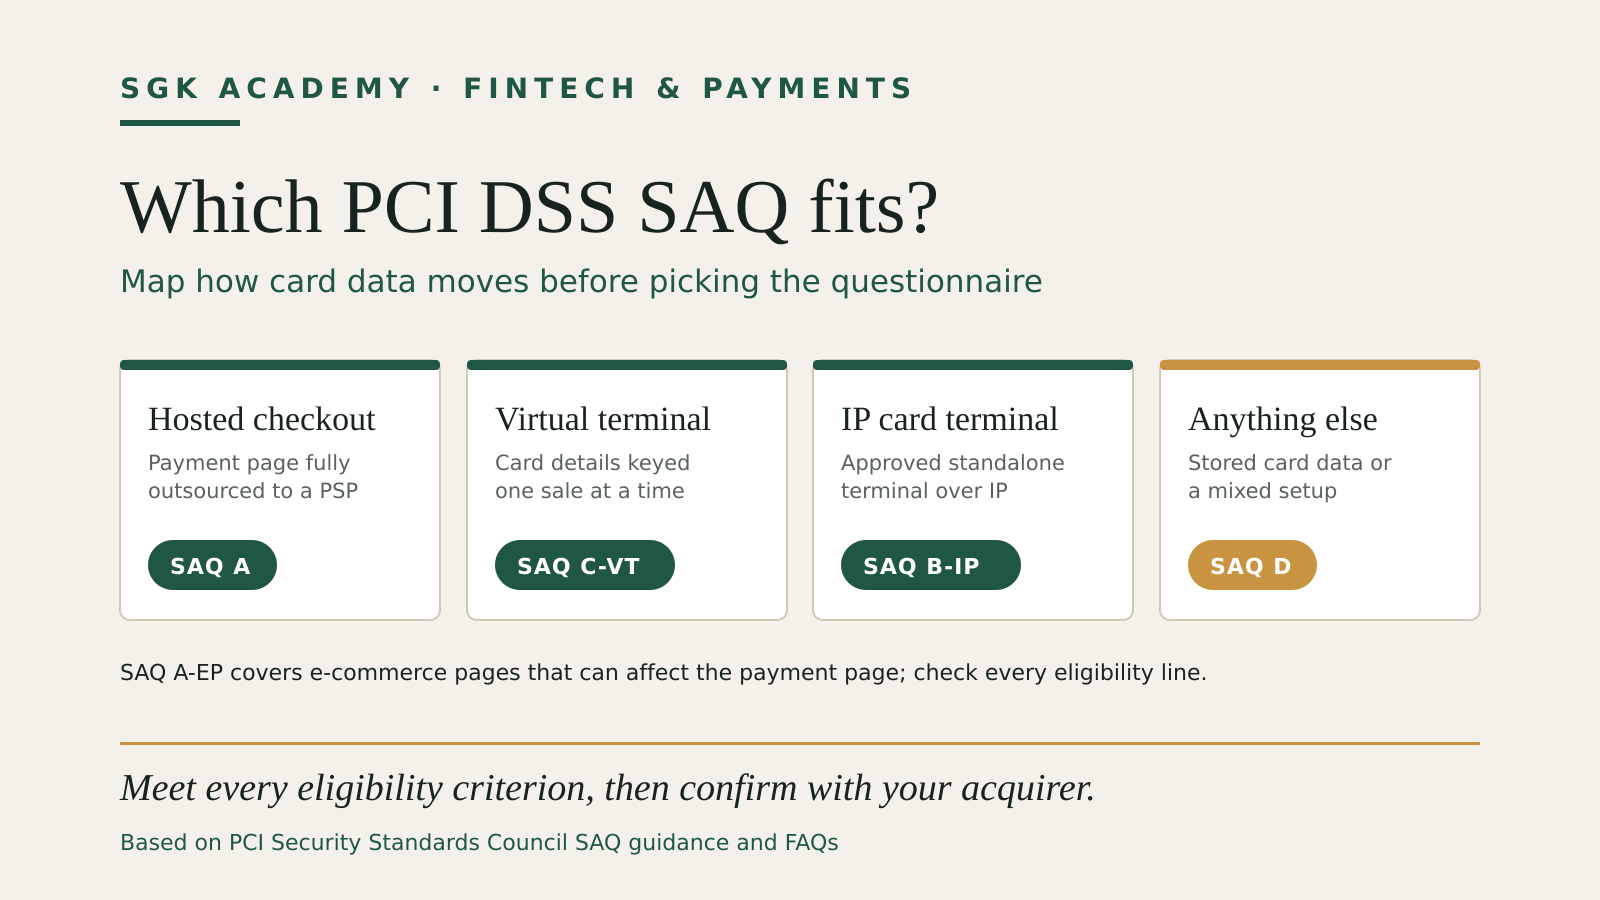
PCI DSS Self-Assessment Questionnaire: Which SAQ Fits?
Map your checkout, virtual terminal or card-terminal environment to the right PCI DSS SAQ.
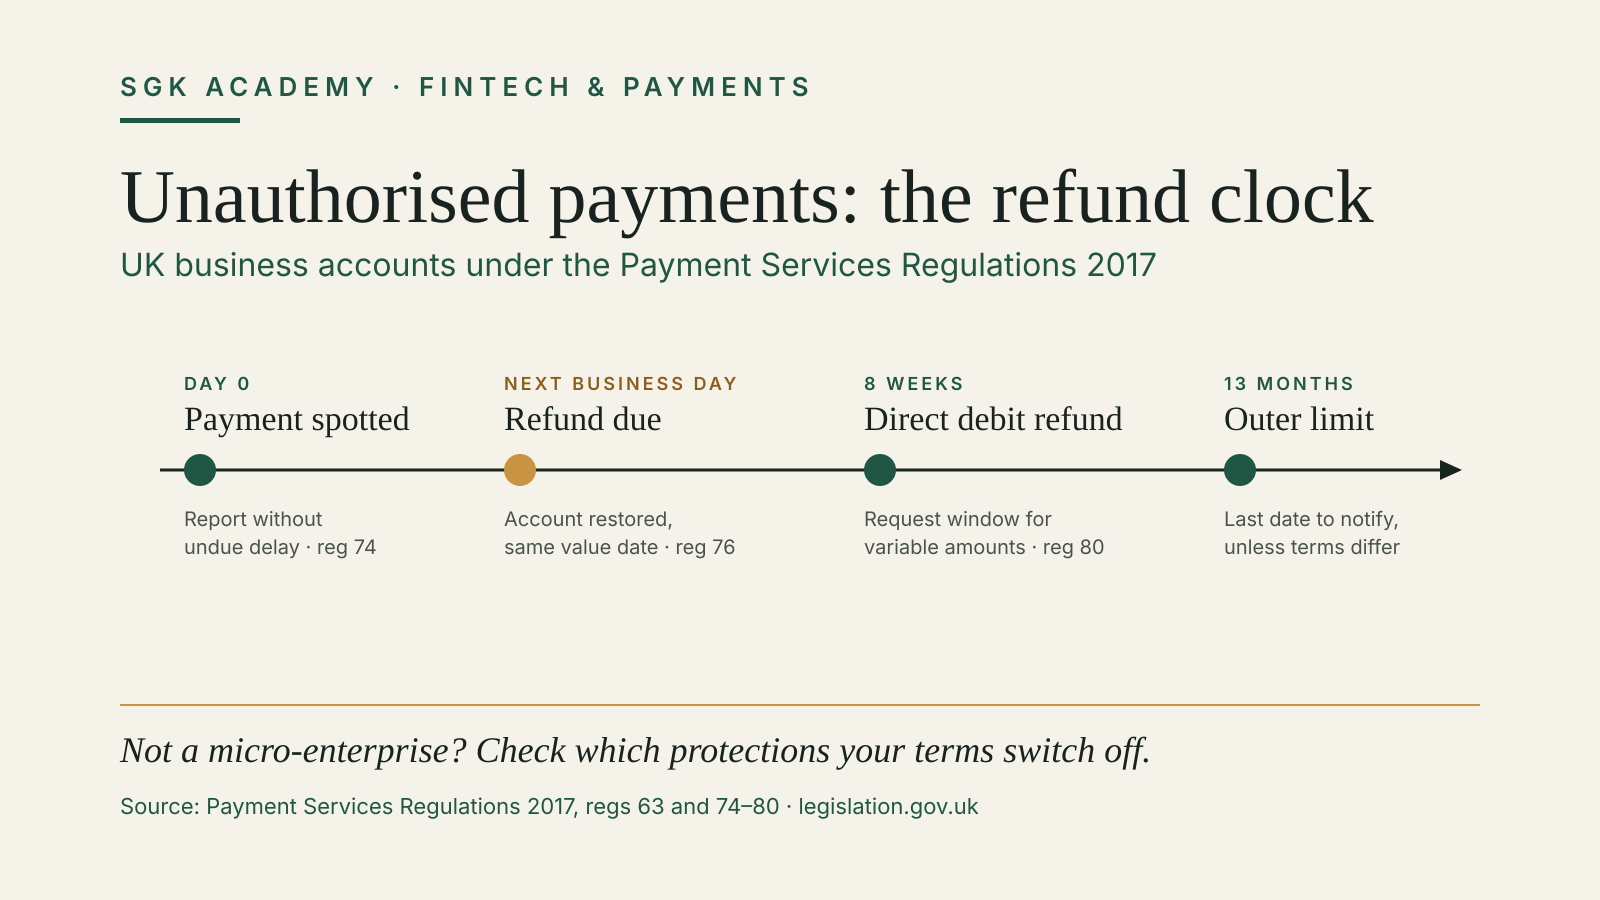
Unauthorised Payments on a Business Account: UK Refund Rights
Who refunds an unauthorised payment from a UK business account, how fast, and when the protection can be signed away.
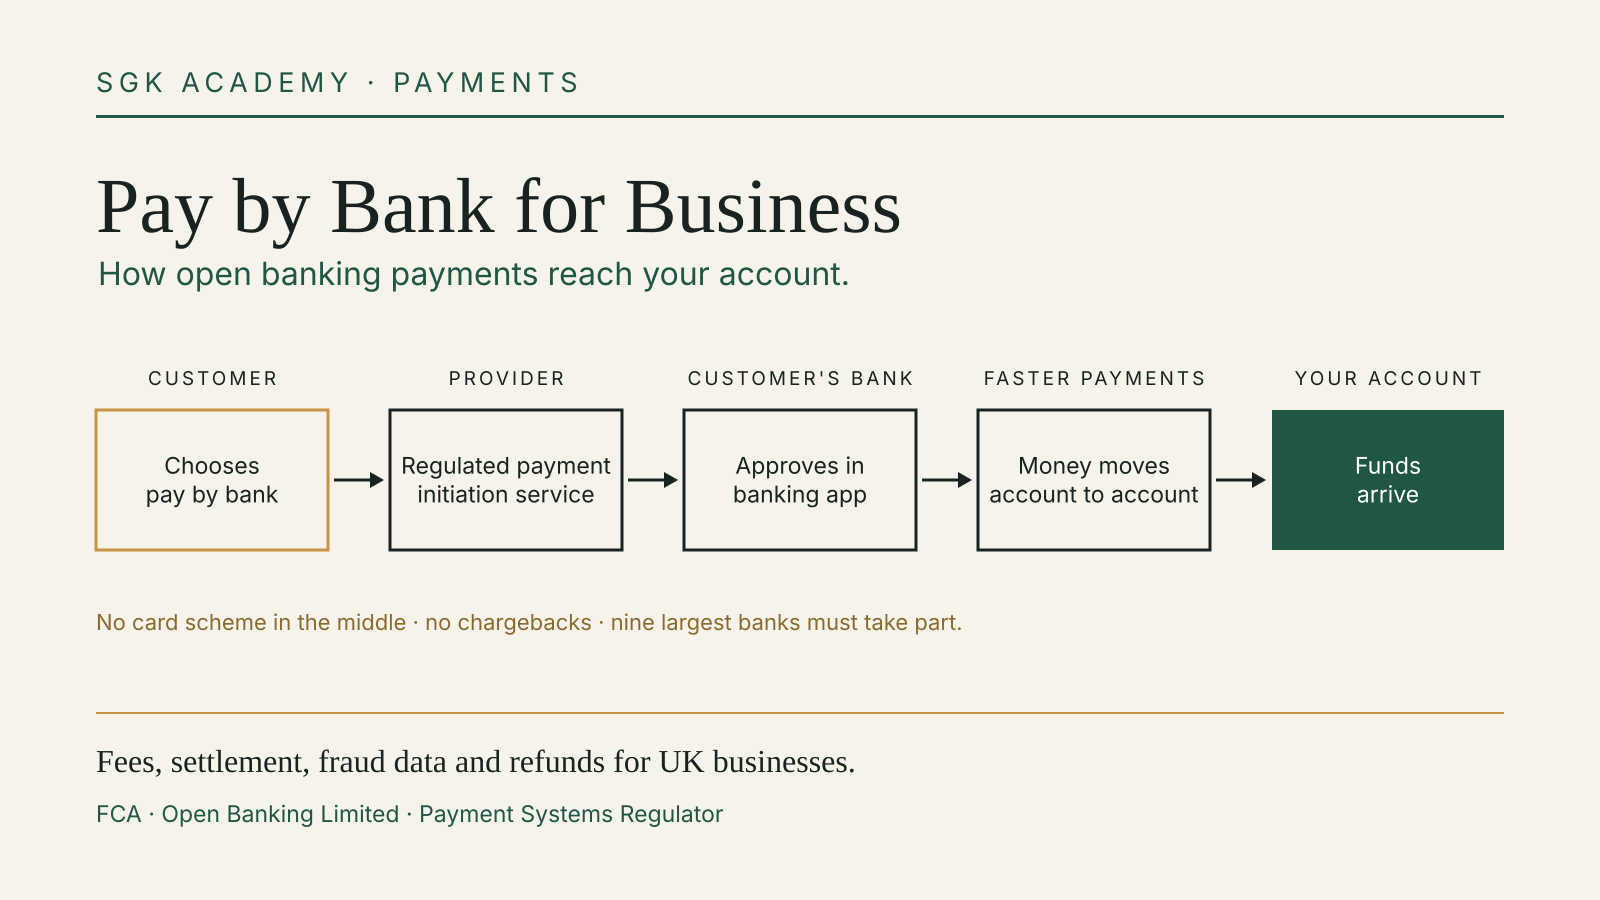
Pay by Bank for Business: How Open Banking Payments Work
How pay by bank works for UK businesses: open banking checkout, fees, settlement, VRPs and refunds.
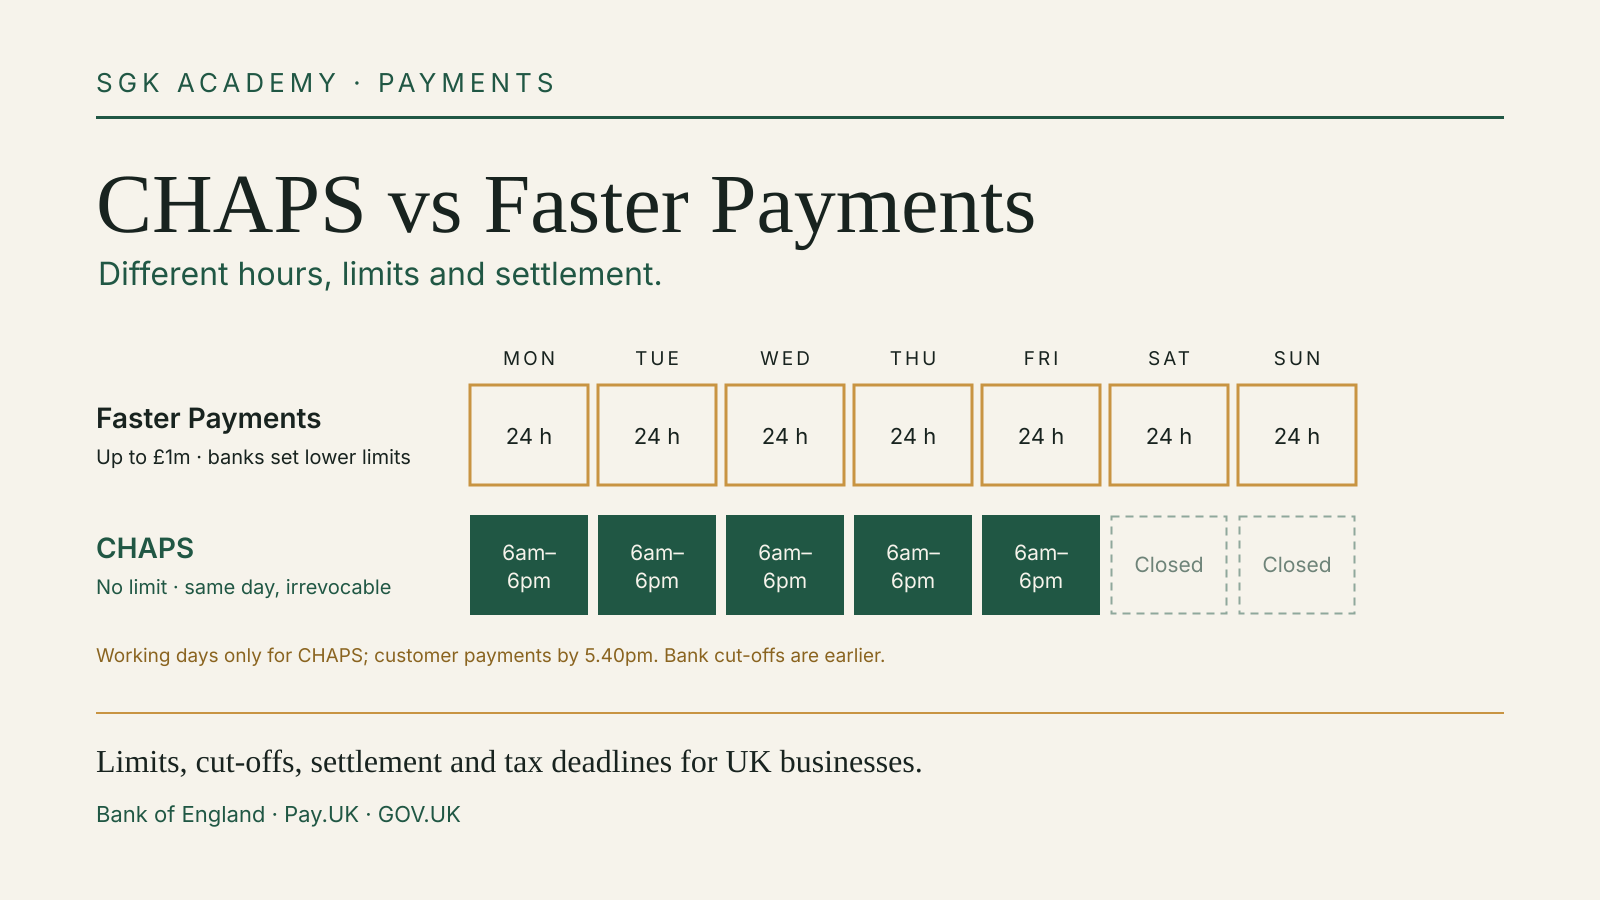
CHAPS vs Faster Payments: Which UK Transfer to Use for Business
Hours, limits, settlement and cut-offs of the two UK systems, and which to use for large or deadline payments.
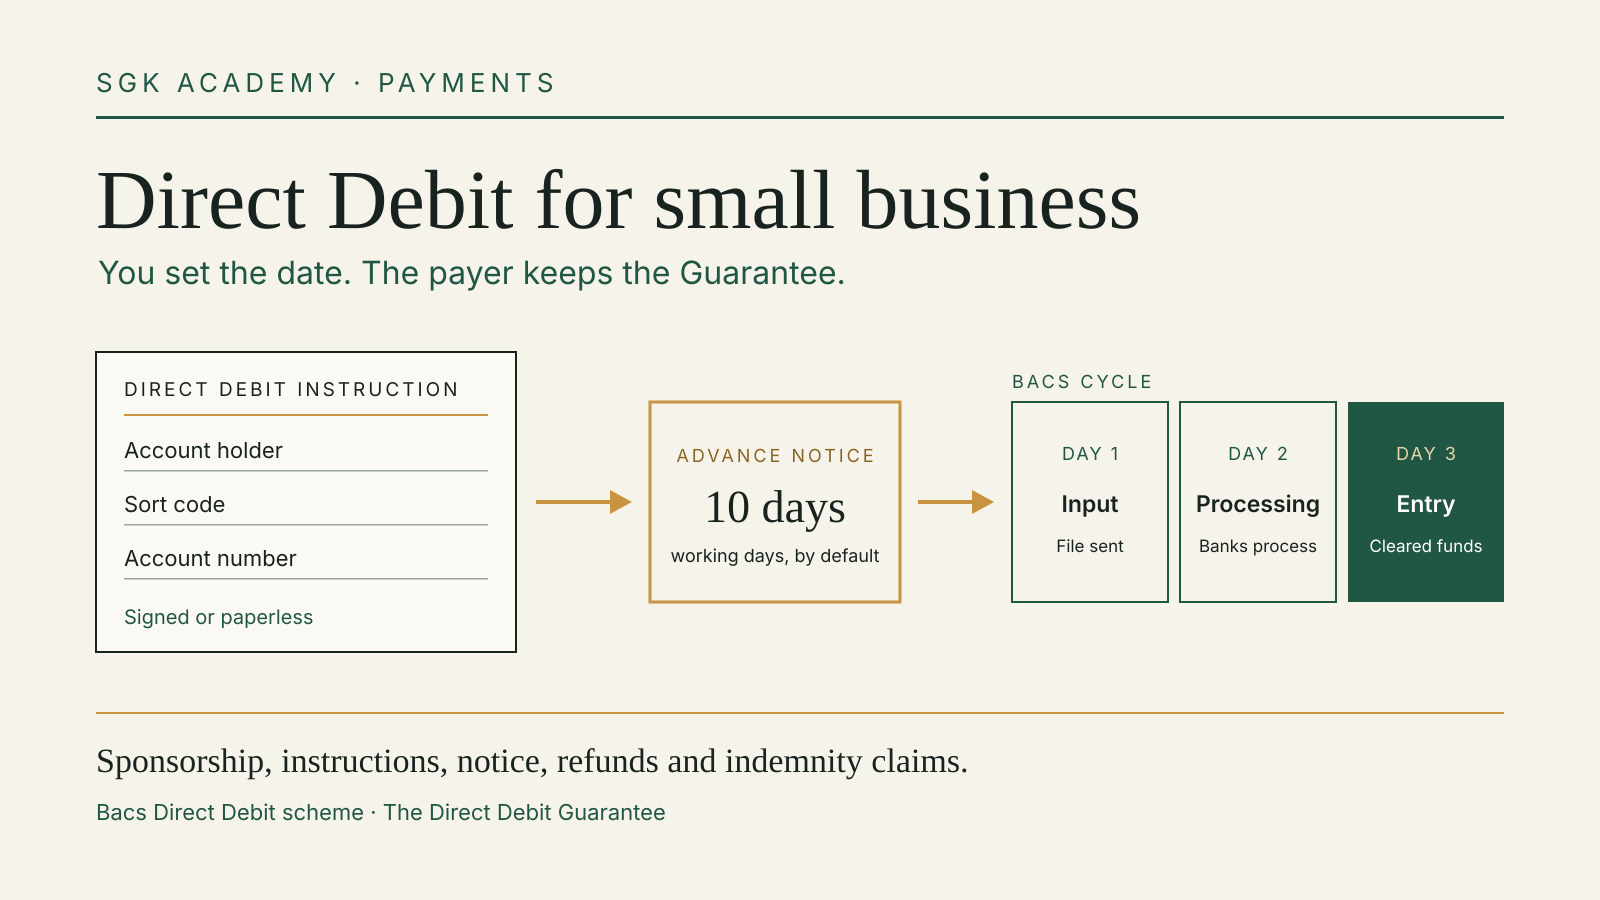
Direct Debit for Small Business: Set Up, Notice and Refunds
How to collect UK payments on your own date: bank sponsorship, instructions, notice periods and refund risk.
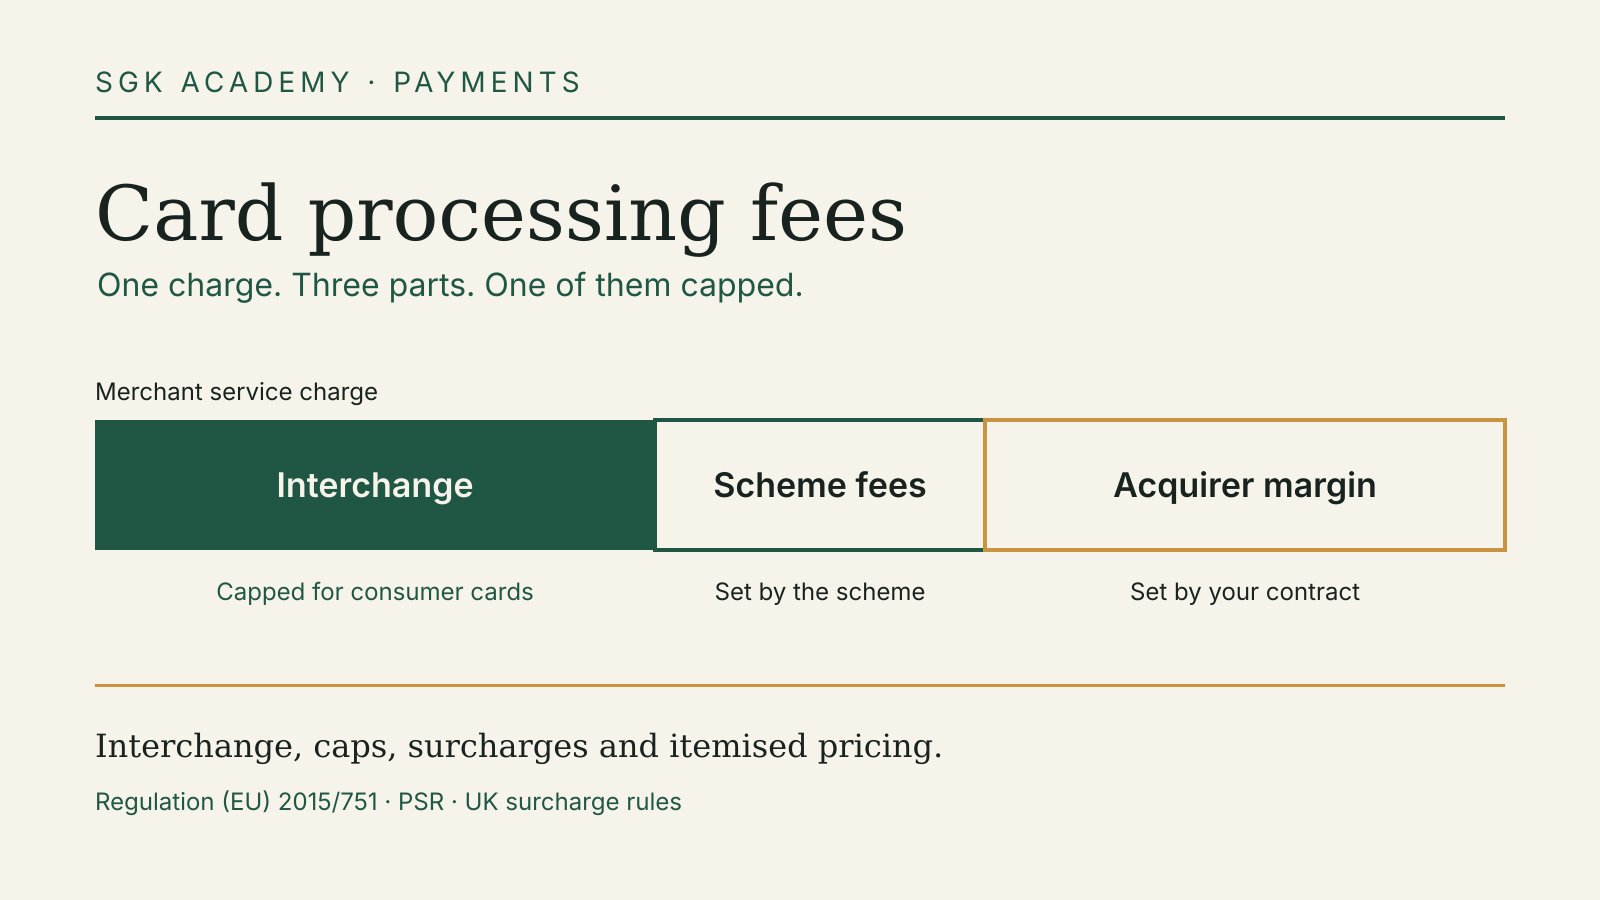
Card Processing Fees: Interchange, Caps and Surcharges
What card fees are made of, which part is capped in the EU and UK, and when a surcharge is allowed.
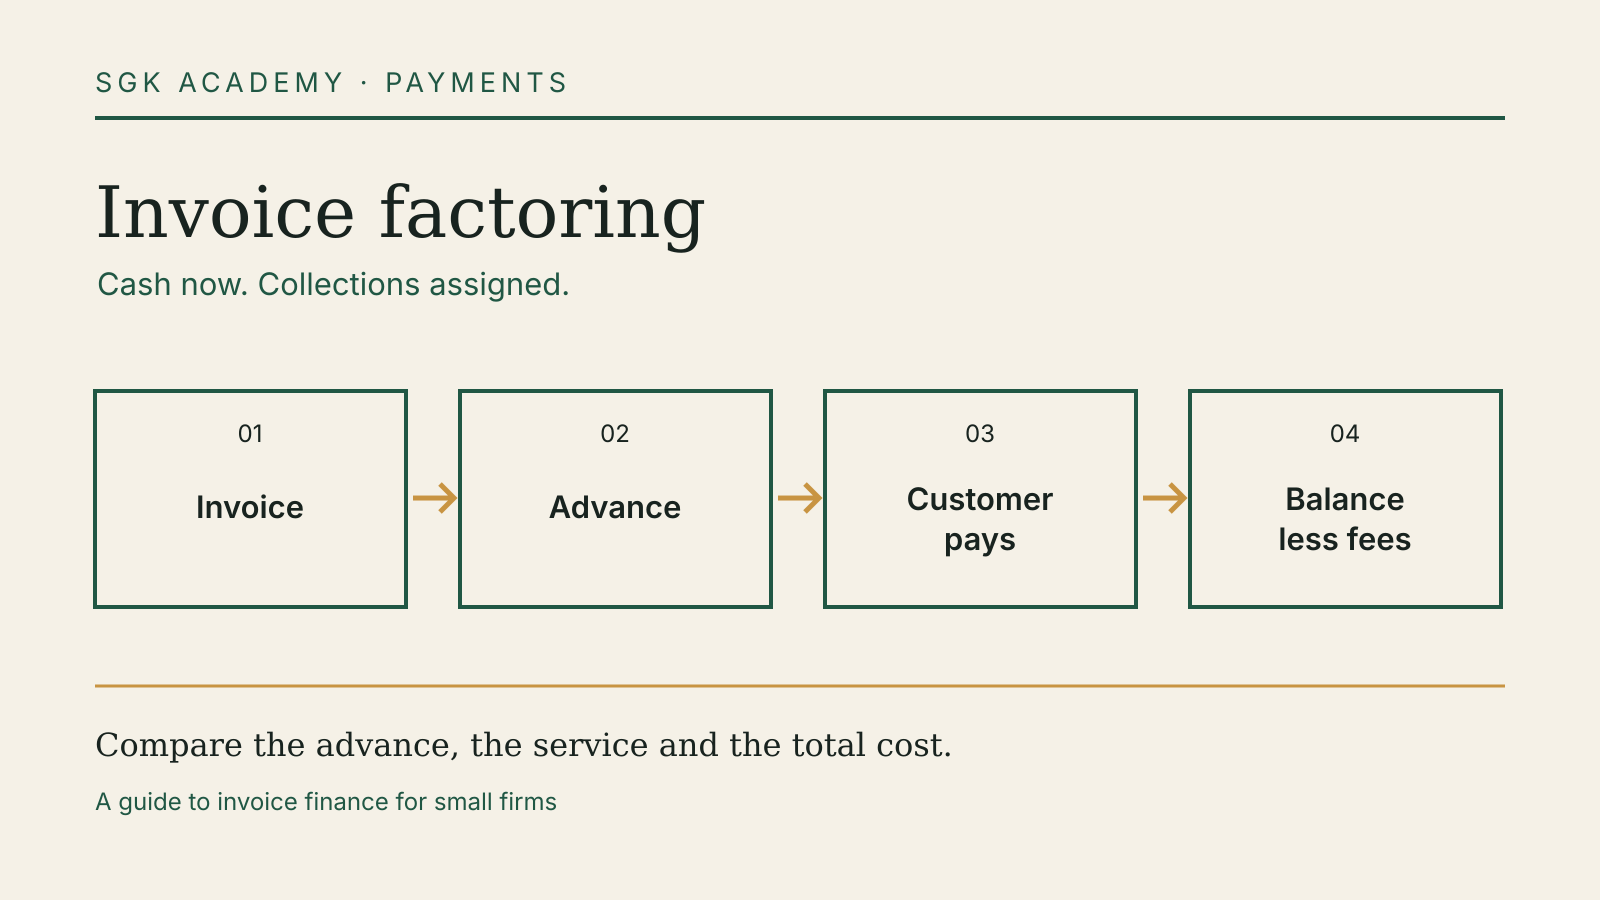
Invoice Factoring vs Discounting: Who Collects the Cash?
Compare invoice factoring and discounting by collections, cash released, fees and responsibility for unpaid invoices.
Bank Accounts, E-Money Accounts and Wallets
Identify the provider, product and protections behind the balance in an app.
The True Cost of an International Transfer
Compare the full sender debit with usable recipient proceeds, including rates and fees.
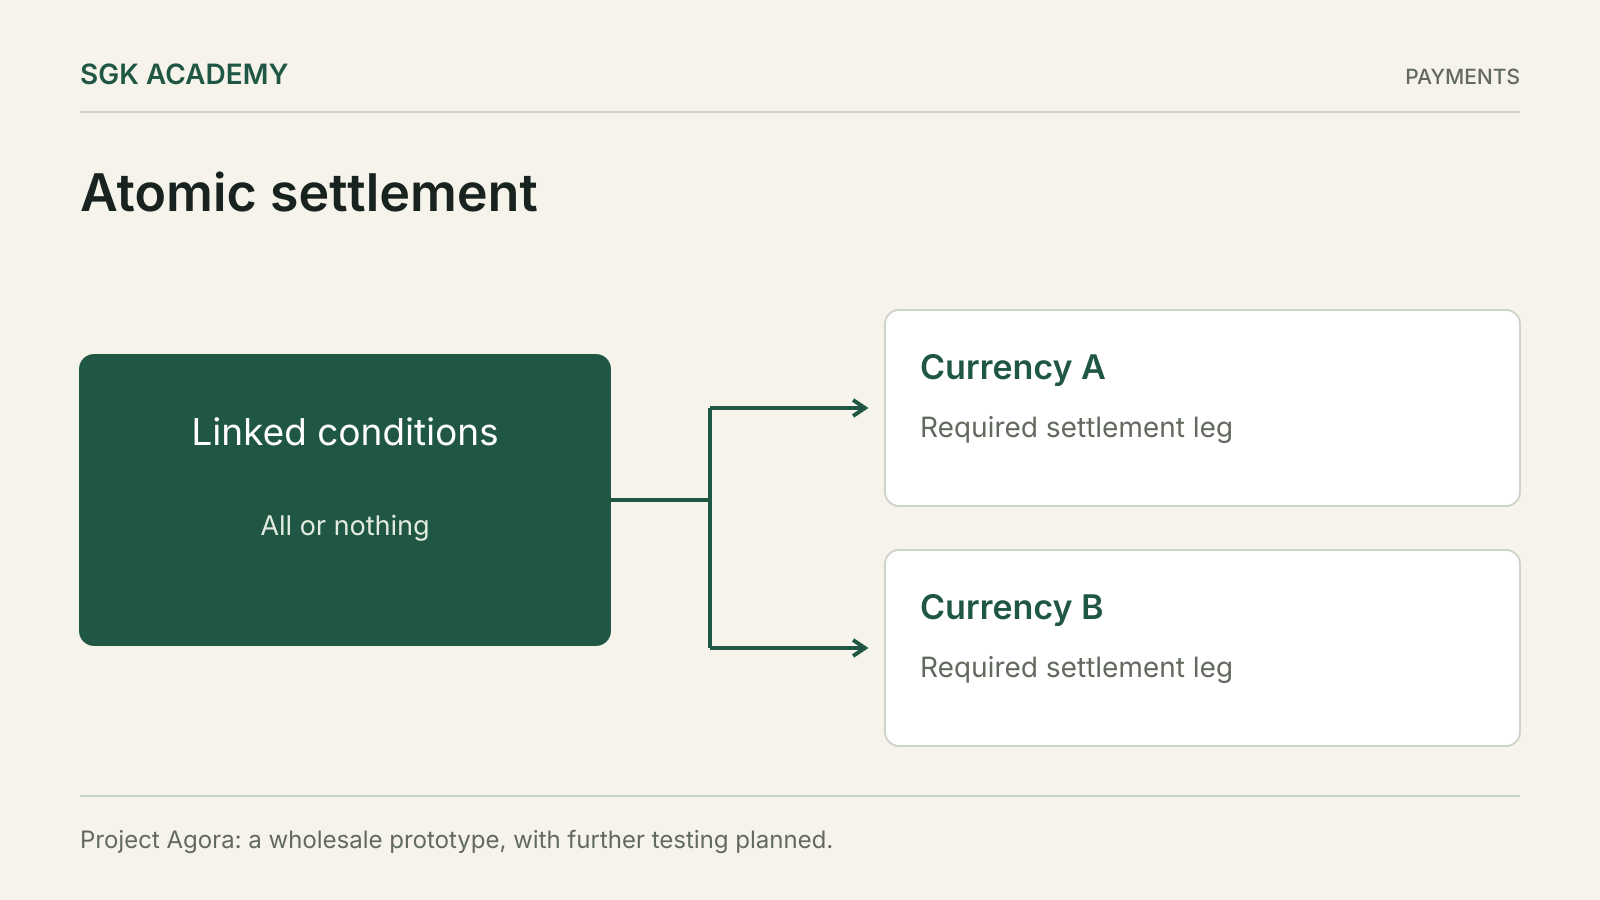
Project Agora: What Atomic Payments Actually Solve
Follow a cross-border payment through an all-or-nothing settlement design.
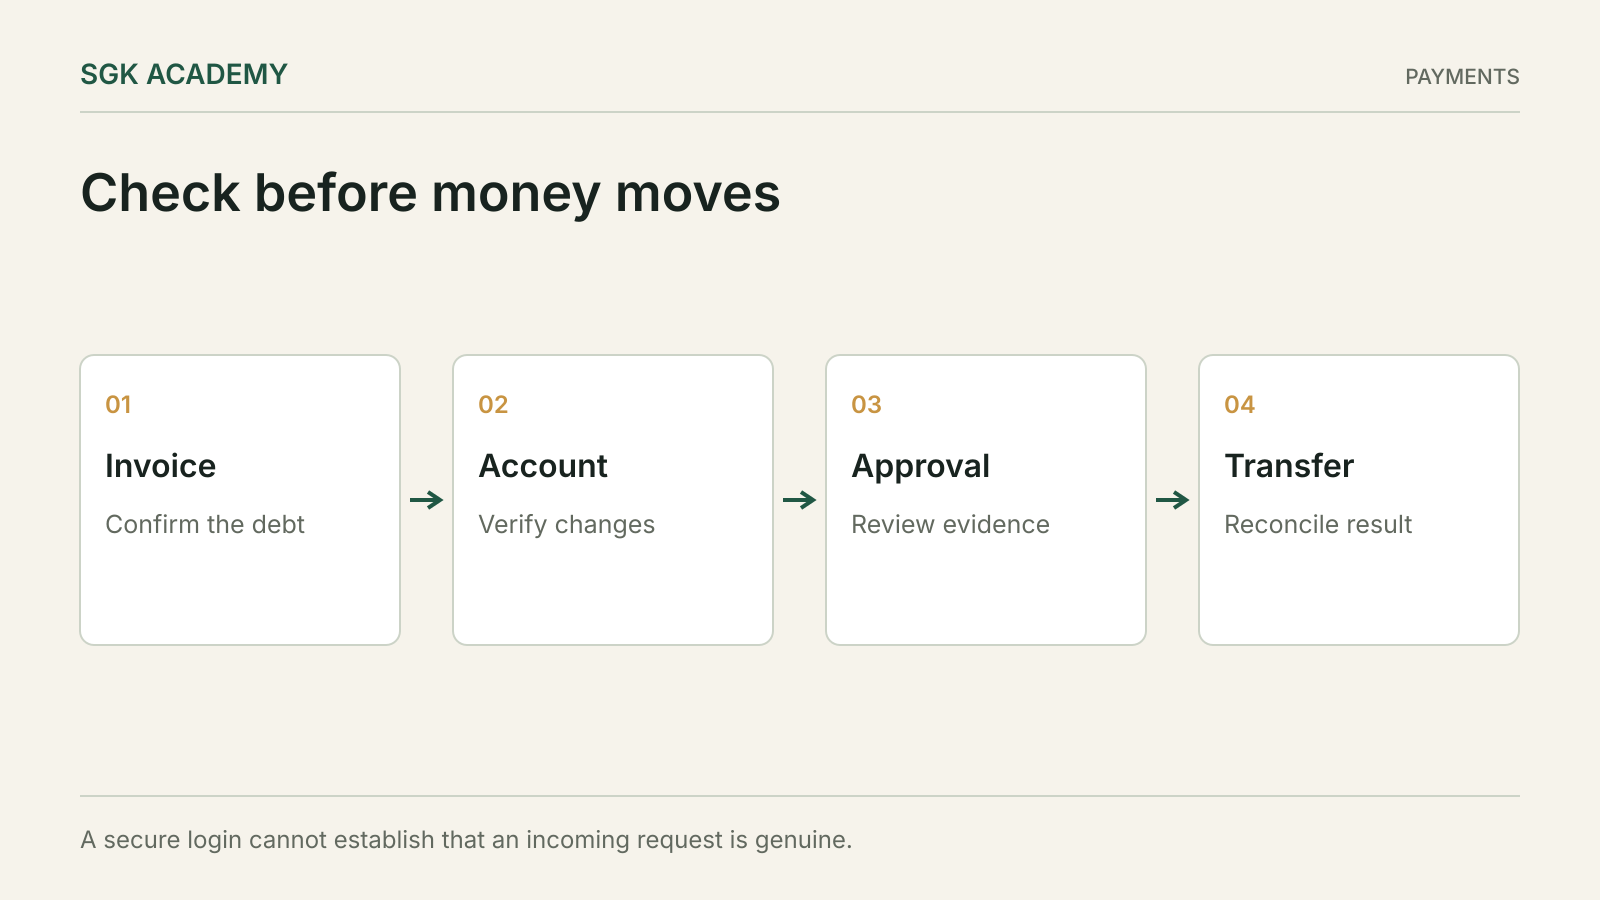
Invoice Fraud: A Payment Check for Small Teams
Verify changed bank details and payment requests before a legitimate login moves money.
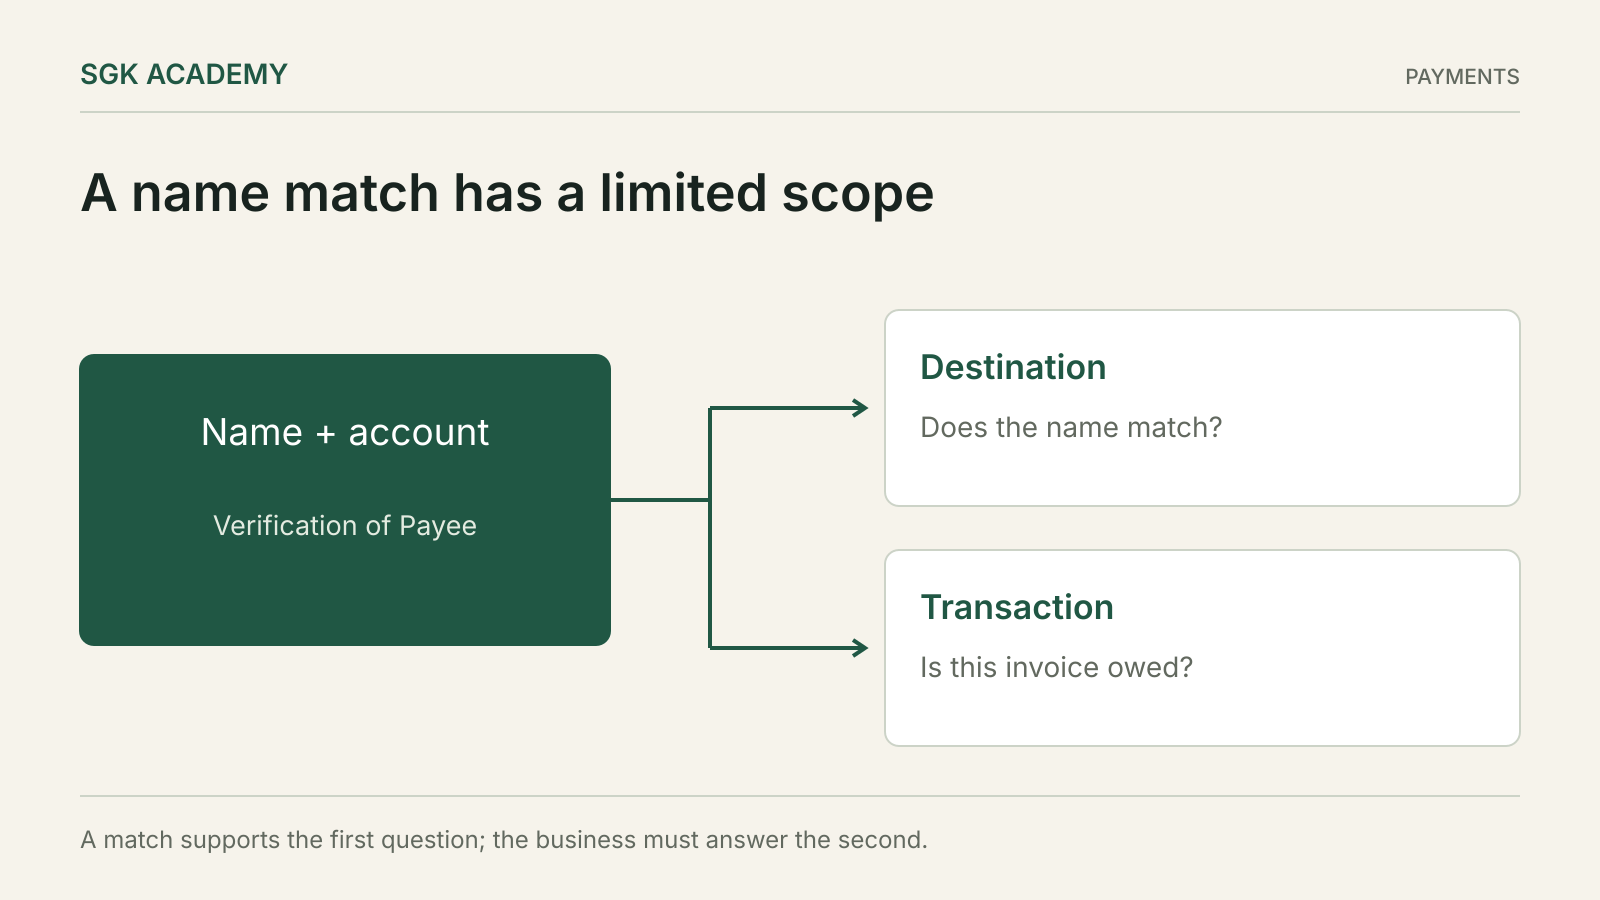
Verification of Payee: What a Name Match Proves
Use bank name checks without mistaking a matching account for a trustworthy supplier.
Payment products can look similar while offering different account arrangements, conversion prices and withdrawal routes. Our guides start by identifying the actual task: holding a balance, receiving a customer payment or delivering an exact amount to a supplier. That task determines which fees, protections and timing conditions matter.
Use the worked comparisons to separate the visible transfer charge from the exchange rate and any later deductions. Use the account guide to identify the provider and product behind an app’s balance. Regulatory examples are labelled by jurisdiction and should not be treated as universal rules.
Read international transfer costs and bank accounts, e-money accounts and wallets, or follow a sequence on Start Here.