


Illustrated portrait of Alex Rowan wearing dark sunglasses.

Alex Rowan

Alex Rowan writes about crypto, payments and everyday finance, with a particular interest in fees, custody and cash flow.

Latest

Bar chart of an illustrative 10%, 90-day rolling reserve through a seasonal peak: the reserve balance at month end rises from £6,000 in September to £27,000 in December, then falls to £25,500 in January, £21,000 in February and £15,000 in March.
rolling reserve ·

Rolling Reserve: How Payment Providers Hold Back Your Sales

How rolling reserves at Stripe, PayPal and Shopify work, and how much cash a 10% 90-day reserve ties up.

Illustrative comparison of 2 BTC bought for £120,000 and worth £90,000 at year-end: £89,550 with a £30,450 impairment under FRS 105 or the FRS 102 cost model, £90,000 under the revaluation model, £90,000 at fair value through net income under US GAAP ASU 2023-08, and no Corporation Tax loss until disposal.
Crypto accounting ·

Accounting for Cryptocurrency: FRS 102, FRS 105 and IFRS

How a company records bitcoin and other tokens under FRS 105, FRS 102, IFRS and US GAAP, with a worked example.
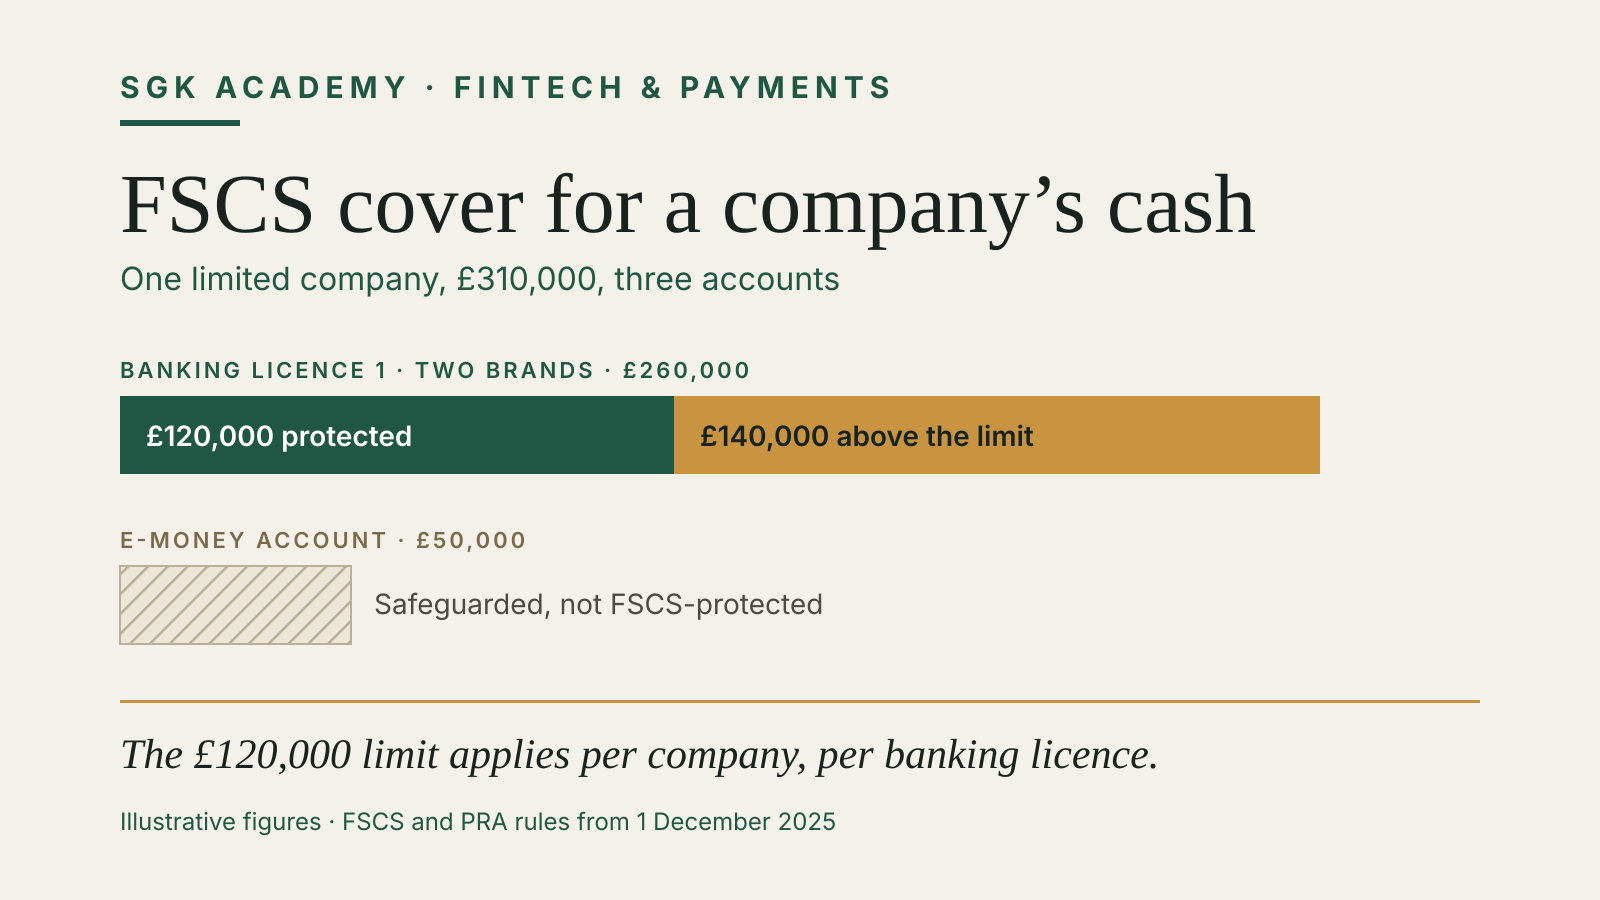
Bar chart: a limited company holds £260,000 under one banking licence, of which £120,000 is FSCS-protected and £140,000 is above the limit, plus £50,000 in an e-money account that is safeguarded but not FSCS-protected.
FSCS ·

FSCS Protection for Business Accounts: How the £120,000 Limit Works

How FSCS protects a company's bank deposits up to £120,000, why shared licences cut cover and why e-money is excluded.
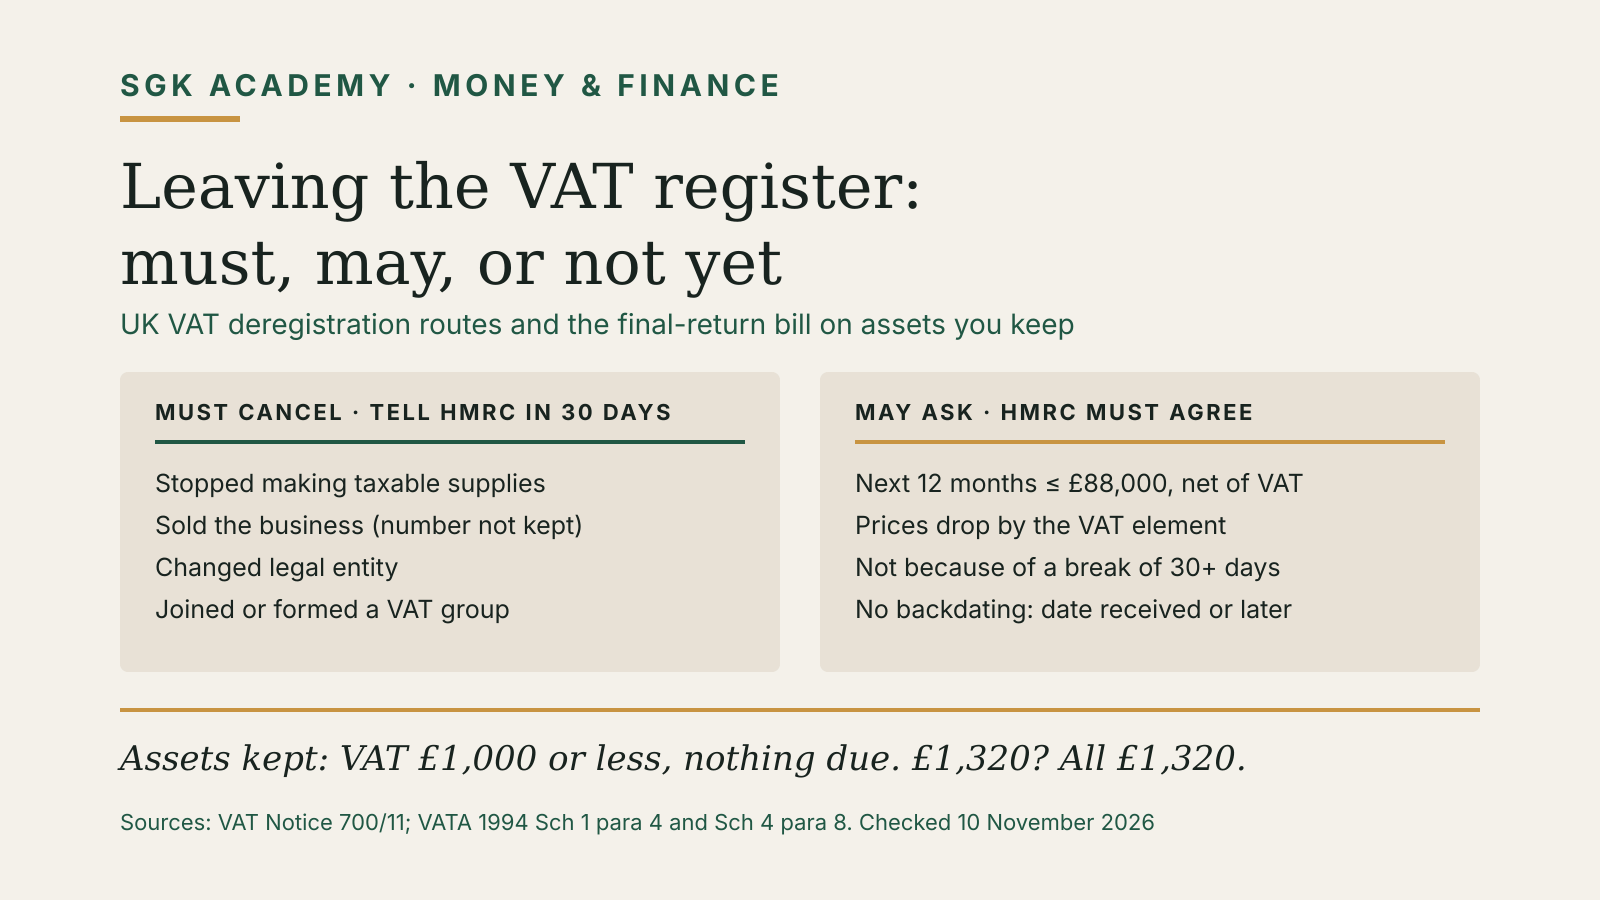
UK VAT deregistration routes compared: you must cancel and tell HMRC within 30 days if you stop making taxable supplies, sell the business without the number, change legal entity or join a VAT group; you may ask HMRC to cancel if VAT-exclusive turnover in the next 12 months will not exceed £88,000, prices drop by the VAT element, the fall is not due to a break of 30 days or more, and the date is not backdated. VAT on assets kept is nothing if £1,000 or less, otherwise all of it, for example £1,320.
VAT ·

VAT Deregistration: When You Must Cancel and When You May

When you must cancel UK VAT registration, when you may below £88,000, and the VAT due on assets you keep.
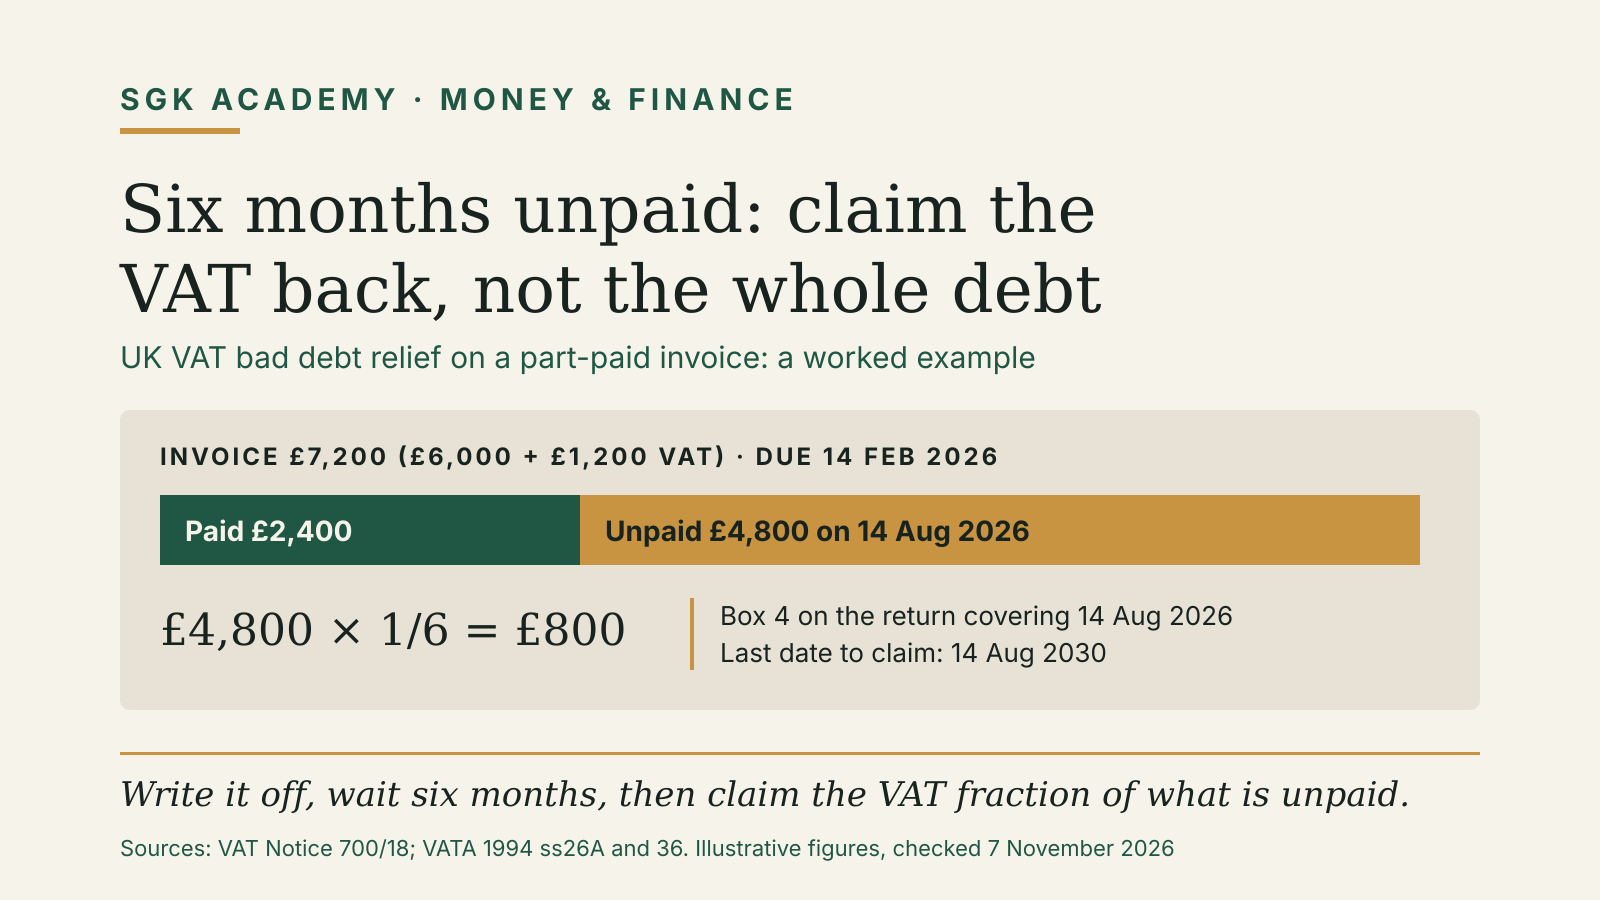
Worked example of UK VAT bad debt relief: a £7,200 invoice (£6,000 plus £1,200 VAT) due 14 February 2026, £2,400 paid and £4,800 unpaid on 14 August 2026; relief is £4,800 × 1/6 = £800, claimed in box 4 of the VAT return covering 14 August 2026, with a last claim date of 14 August 2030.
VAT ·

Bad Debt Relief VAT: Reclaiming VAT on an Unpaid Invoice

Reclaim the VAT on an unpaid invoice once it is six months overdue: conditions, VAT Return boxes and a worked example.
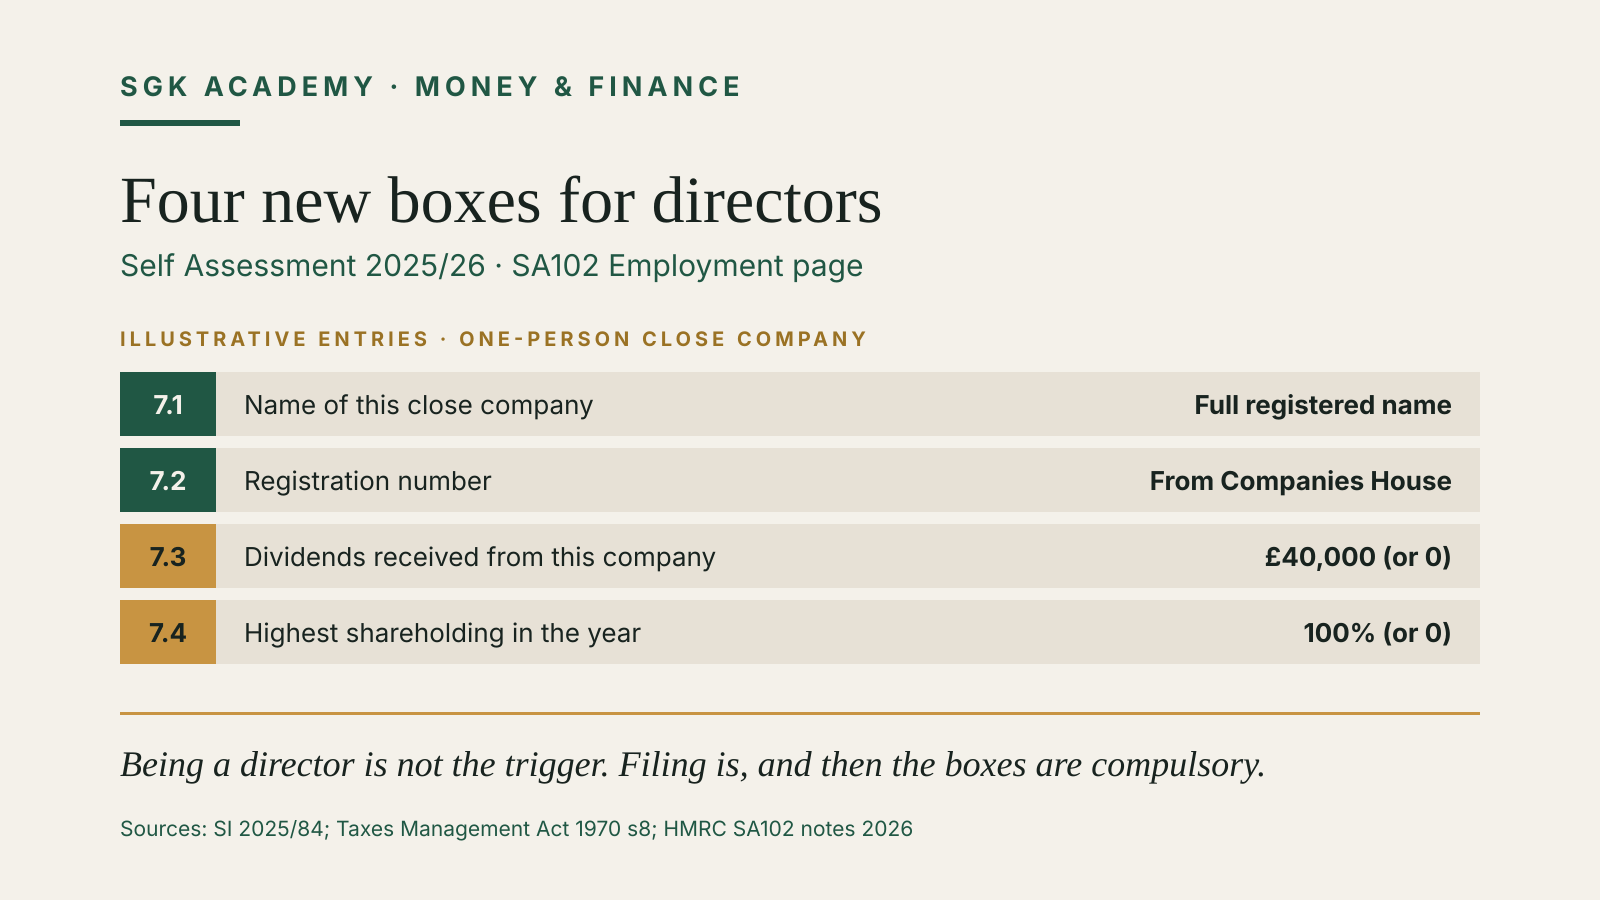
The four close-company boxes on the 2025/26 SA102 Employment page: 7.1 company name, 7.2 registration number, 7.3 dividends received (£40,000 in the example, or 0) and 7.4 highest shareholding (100%, or 0).
Self Assessment ·

Do Company Directors Need to Do Self Assessment? The 2025/26 Rules

When a UK company director must file Self Assessment, the £10,000 dividend line and the new 2025/26 SA102 boxes.
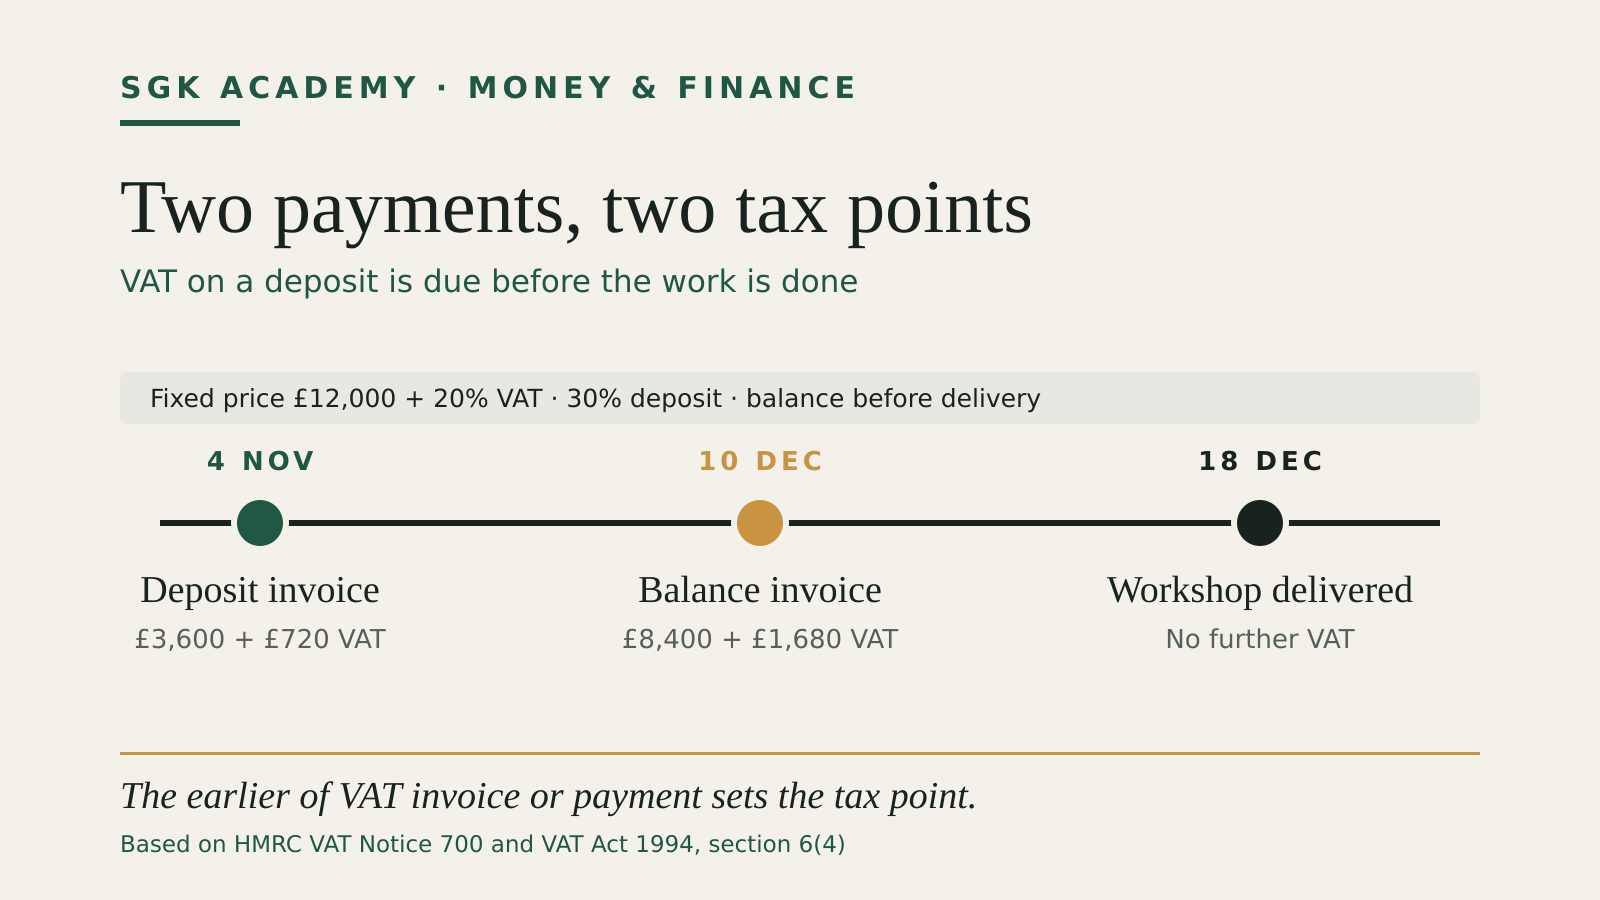
Timeline of a £12,000 project: deposit invoice on 4 November with £720 VAT, balance invoice on 10 December with £1,680 VAT, and no further VAT at delivery on 18 December
VAT ·

VAT on Deposits and Advance Payments

When a customer deposit creates a UK VAT tax point, how refundable security differs, and what to record.
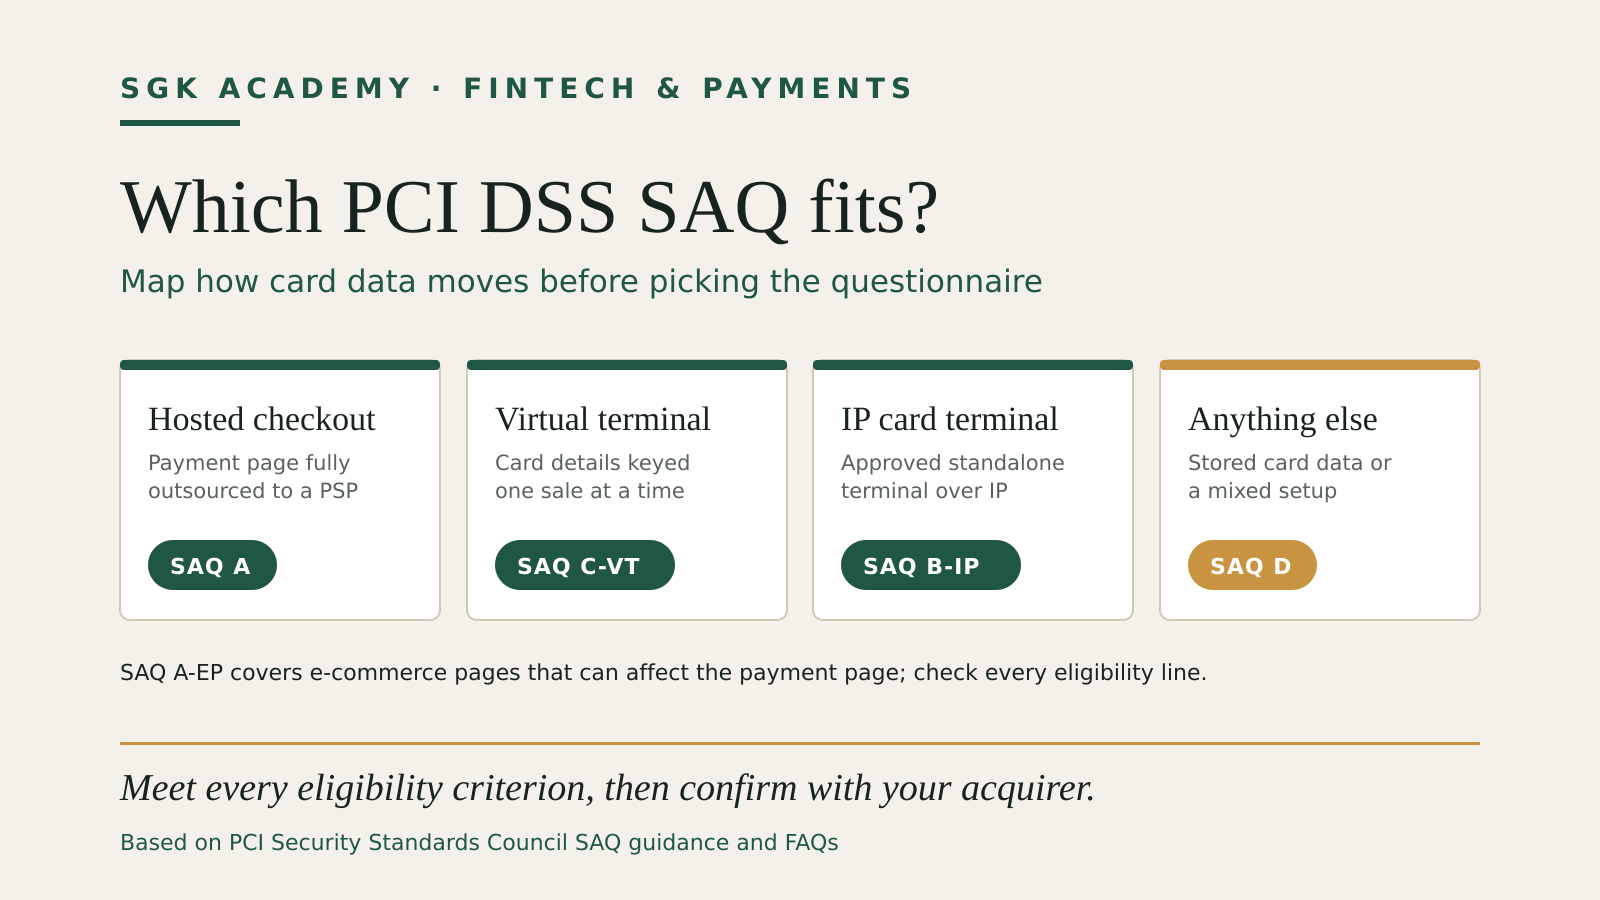
Four card-payment setups matched to a PCI DSS questionnaire: hosted checkout to SAQ A, virtual terminal to SAQ C-VT, IP card terminal to SAQ B-IP, anything else to SAQ D
PCI DSS ·

PCI DSS Self-Assessment Questionnaire: Which SAQ Fits?

Map your checkout, virtual terminal or card-terminal environment to the right PCI DSS SAQ.
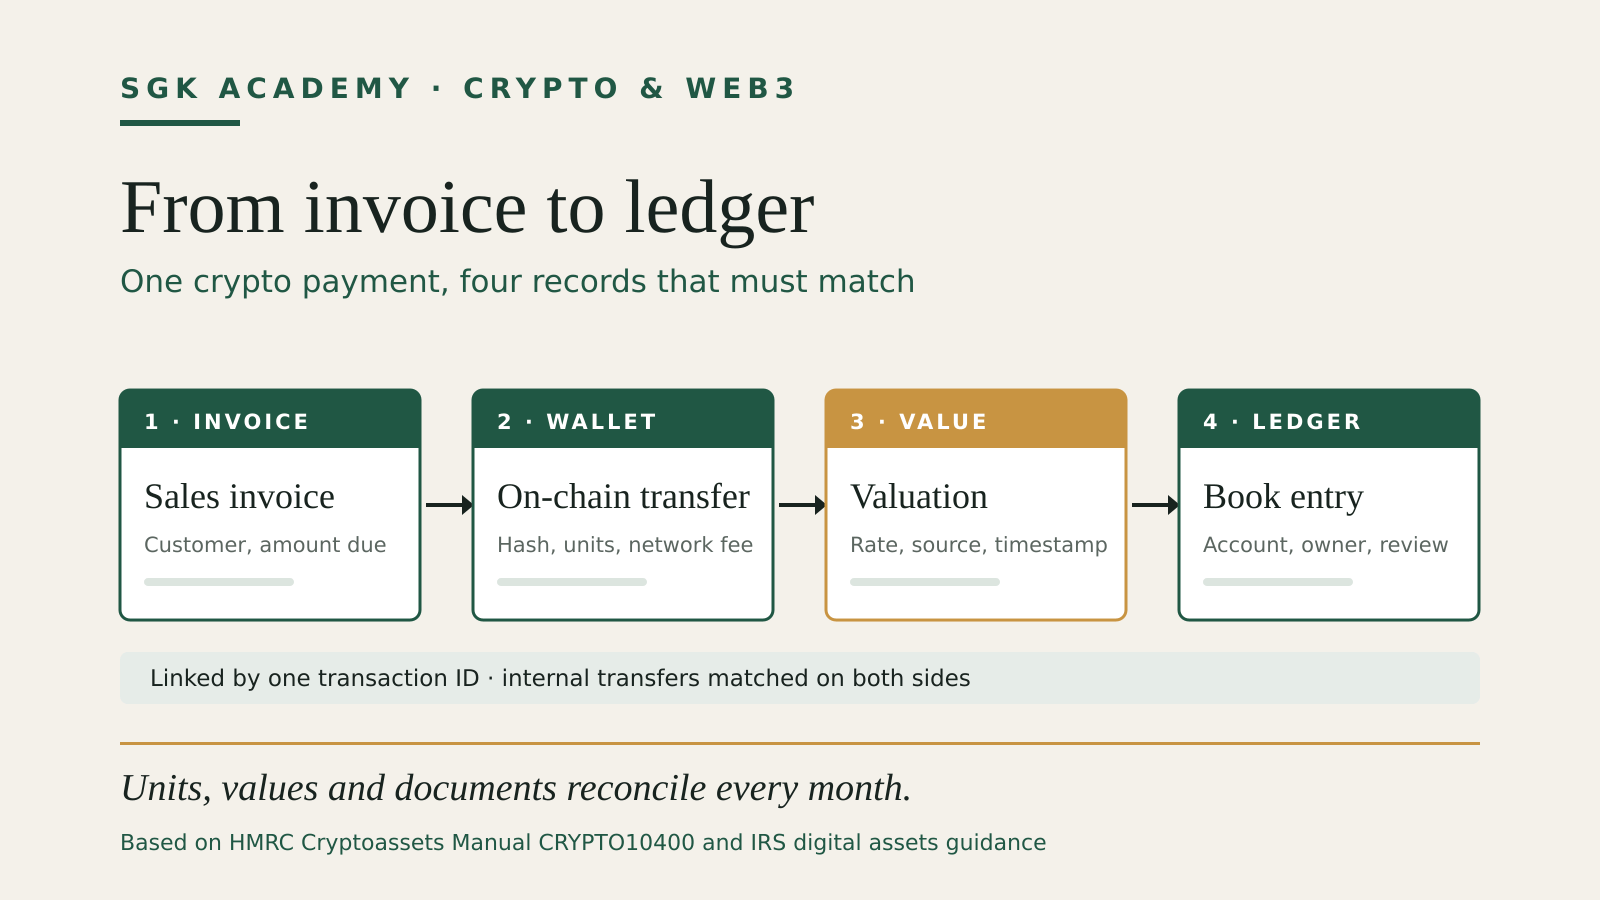
Diagram of one crypto payment traced through four linked records: sales invoice, on-chain wallet transfer, valuation and ledger entry
crypto tax ·

Crypto Transaction Records for a Small Business

Build an audit trail from invoice to wallet transfer, valuation and business ledger.
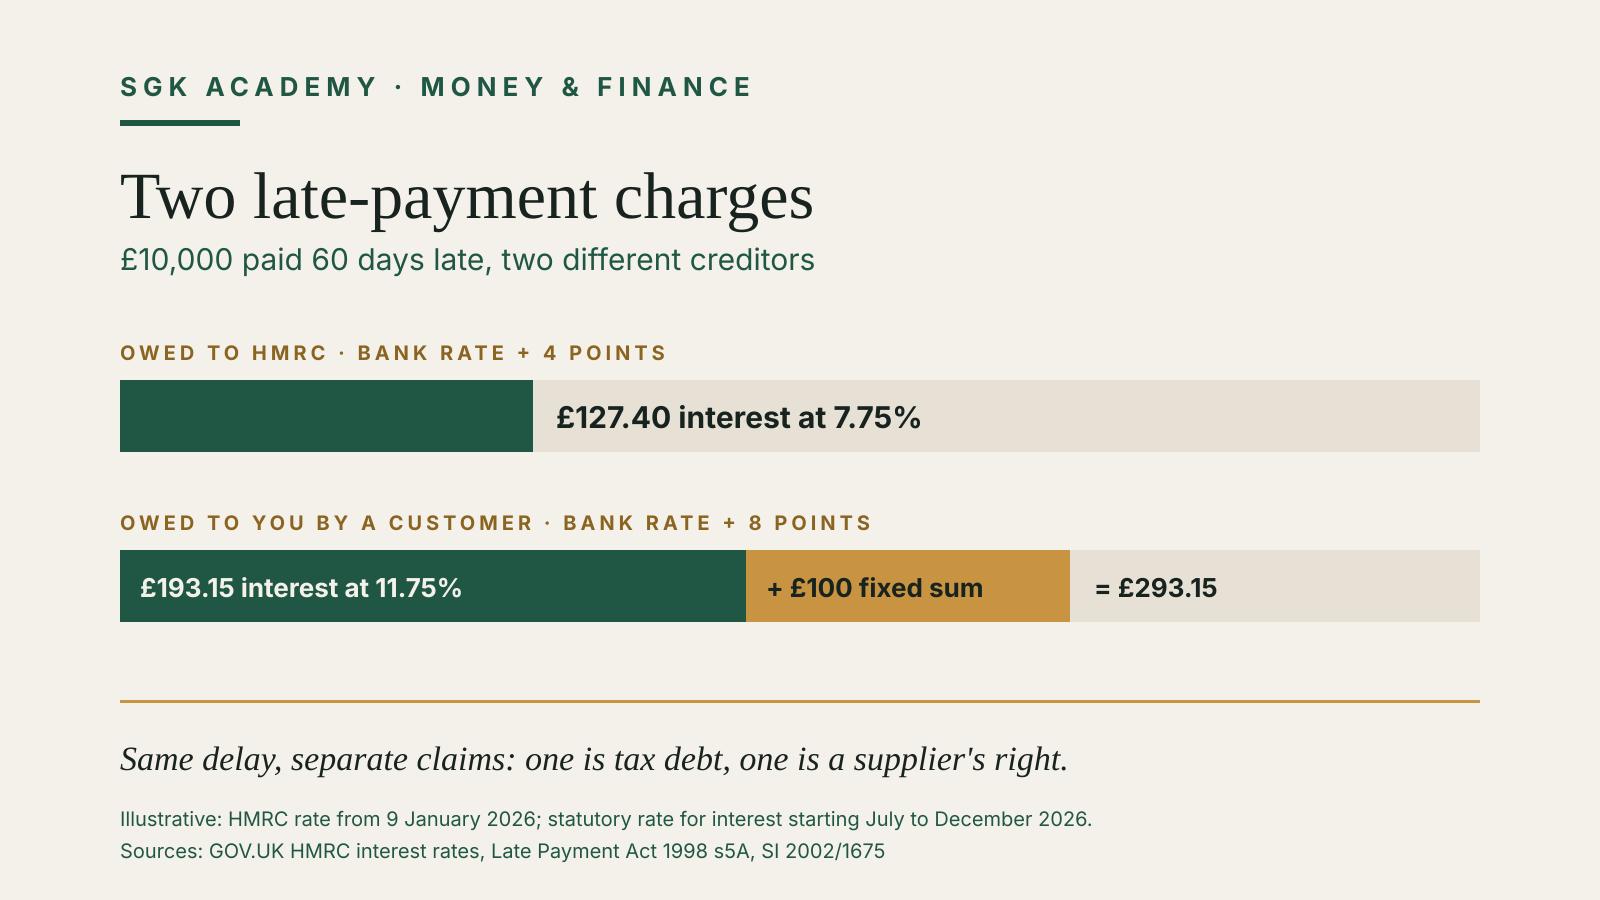
Bar comparison for £10,000 paid 60 days late: £127.40 HMRC interest at 7.75% against £193.15 statutory interest at 11.75% plus a £100 fixed sum.
HMRC ·

HMRC Late Payment Interest vs Statutory B2B Interest

Compare HMRC interest on late tax with statutory interest on an overdue business invoice.
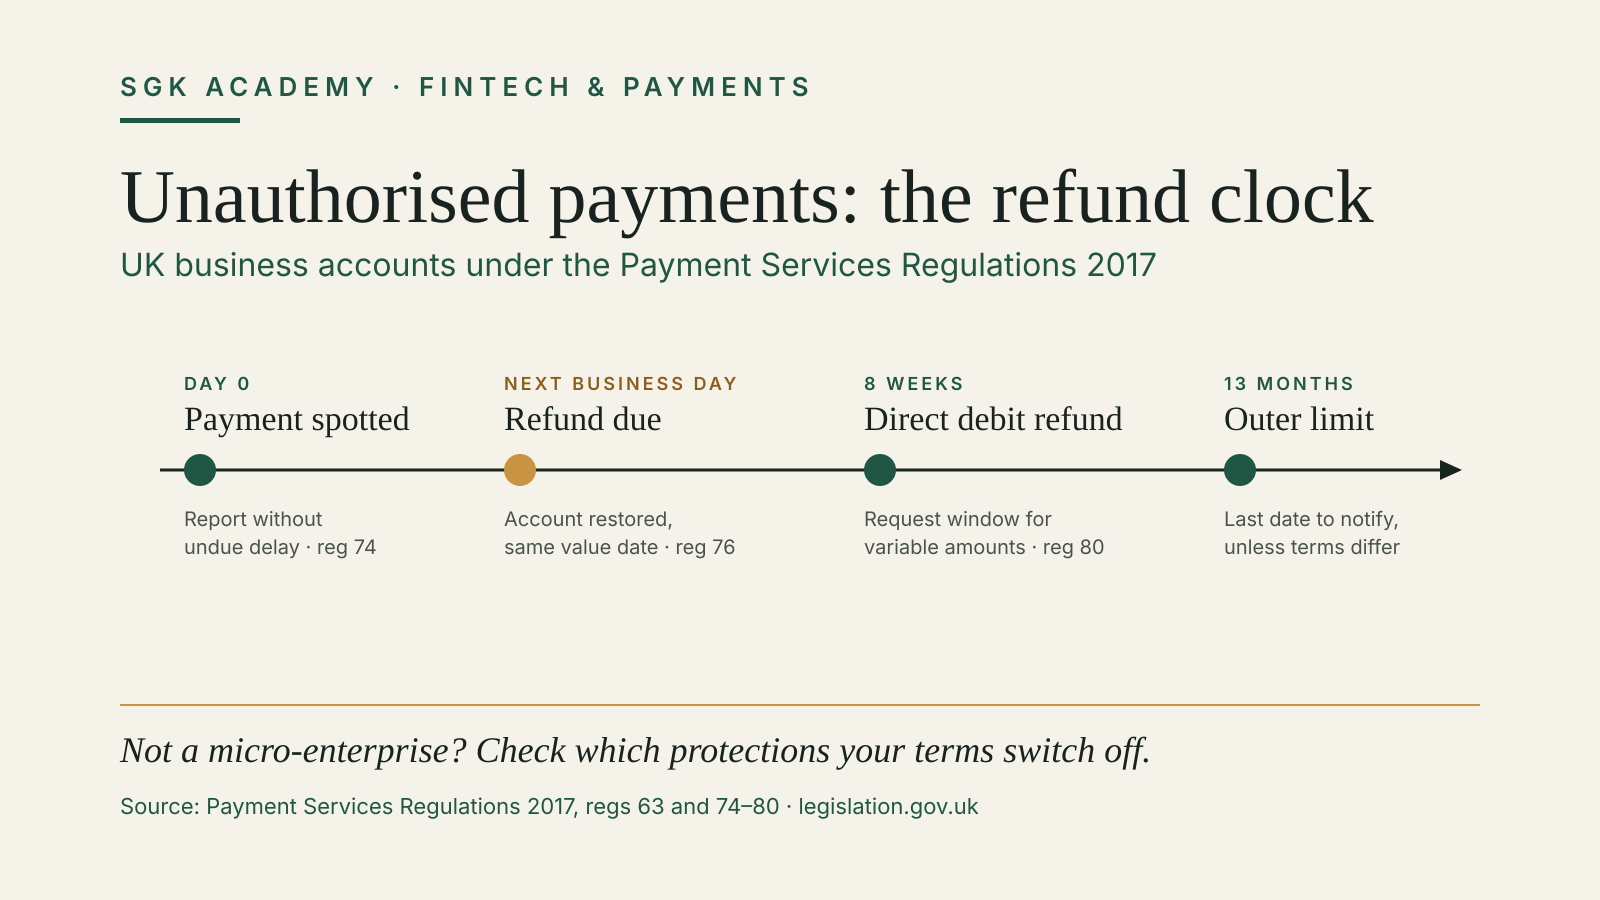
Timeline of refund deadlines for an unauthorised payment on a UK business account: report without undue delay, refund by the next business day, 8 weeks for direct debit refunds, 13 months outer limit.
payments ·

Unauthorised Payments on a Business Account: UK Refund Rights

Who refunds an unauthorised payment from a UK business account, how fast, and when the protection can be signed away.
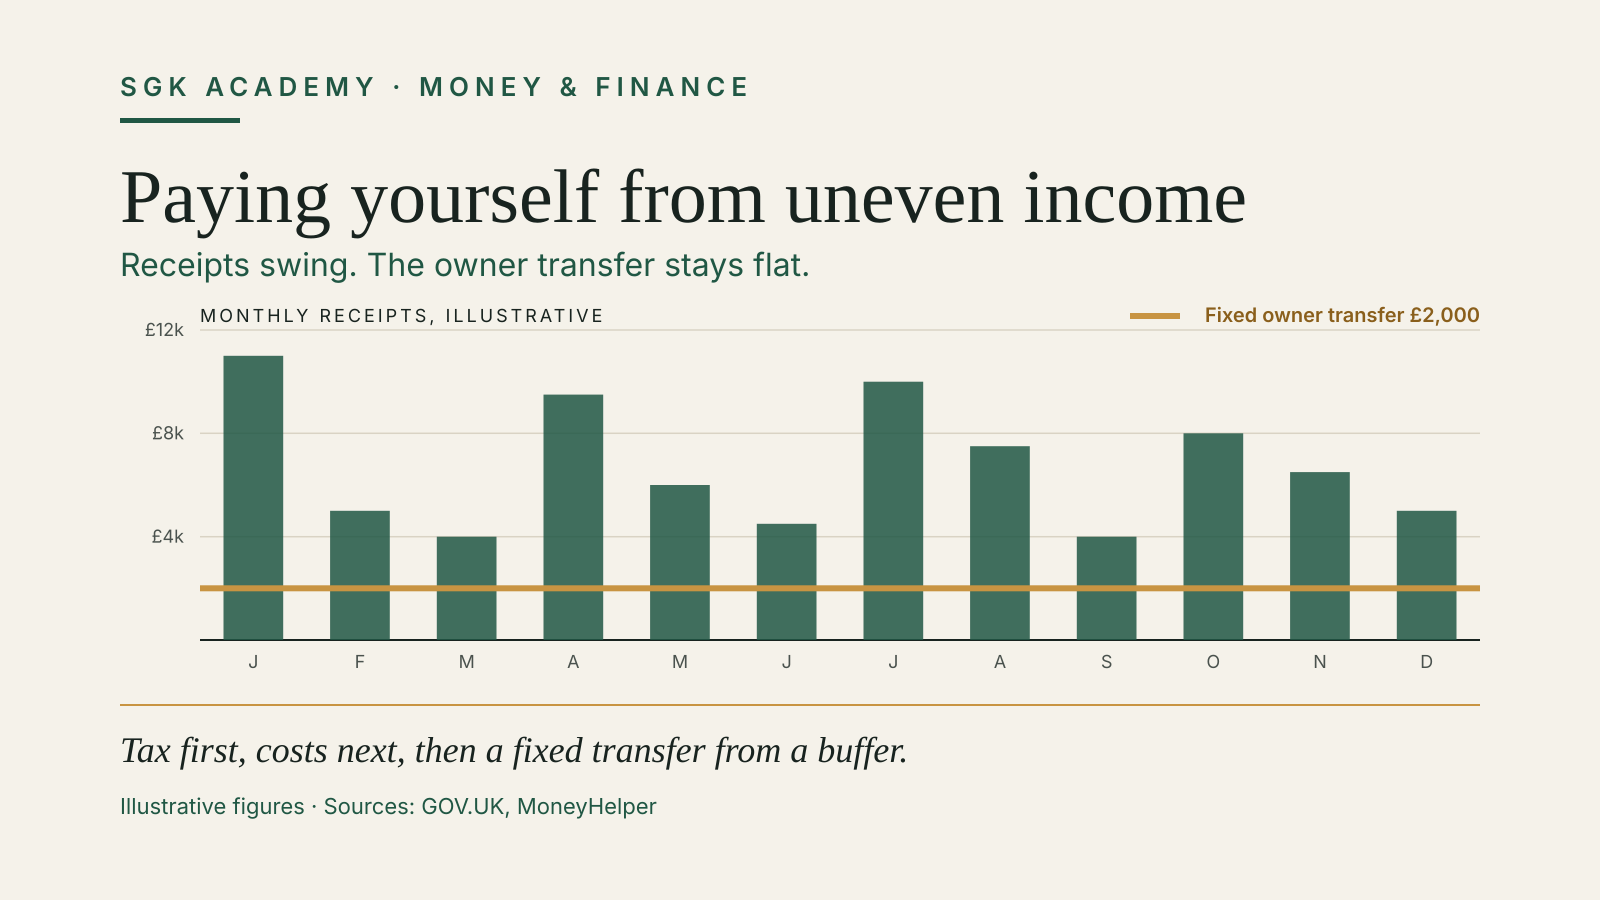
Bar chart of twelve months of illustrative business receipts swinging between £4,000 and £11,000, with a flat gold line marking a fixed £2,000 owner transfer.
cash flow ·

How to Pay Yourself From Irregular Income

Turn uneven business revenue into a steady owner transfer without draining taxes or operating cash.
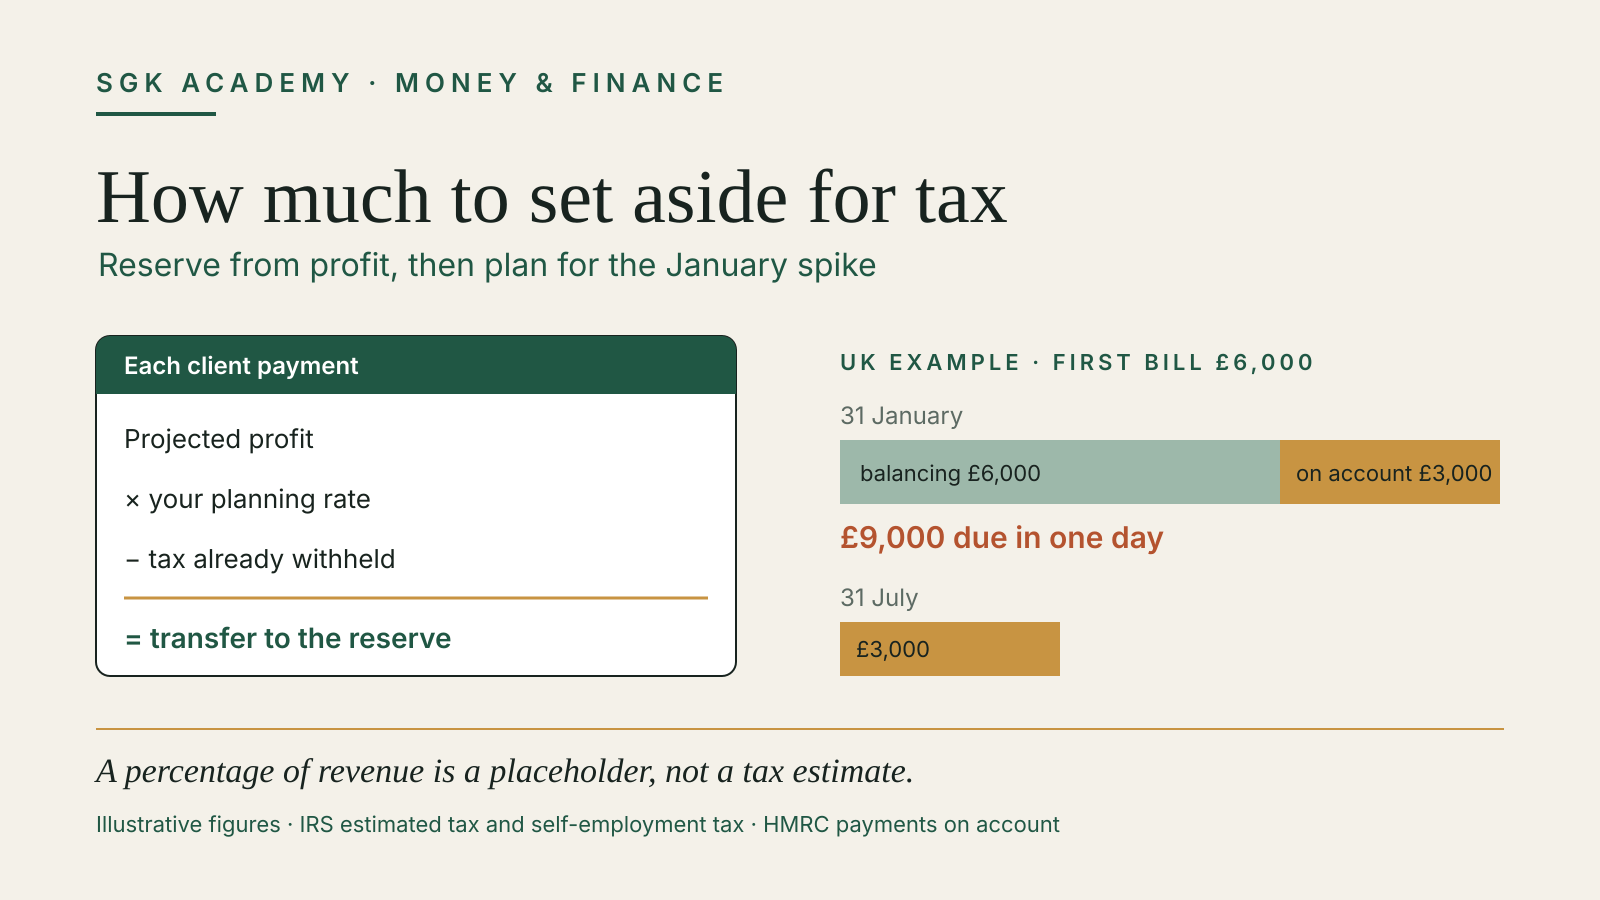
Freelancer tax reserve formula beside an illustrative UK example where a £6,000 first bill becomes £9,000 due on 31 January
freelance tax ·

How Much to Set Aside for Tax as a Freelancer

Build a freelancer tax reserve from projected profit, official payment rules and quarterly true-ups.
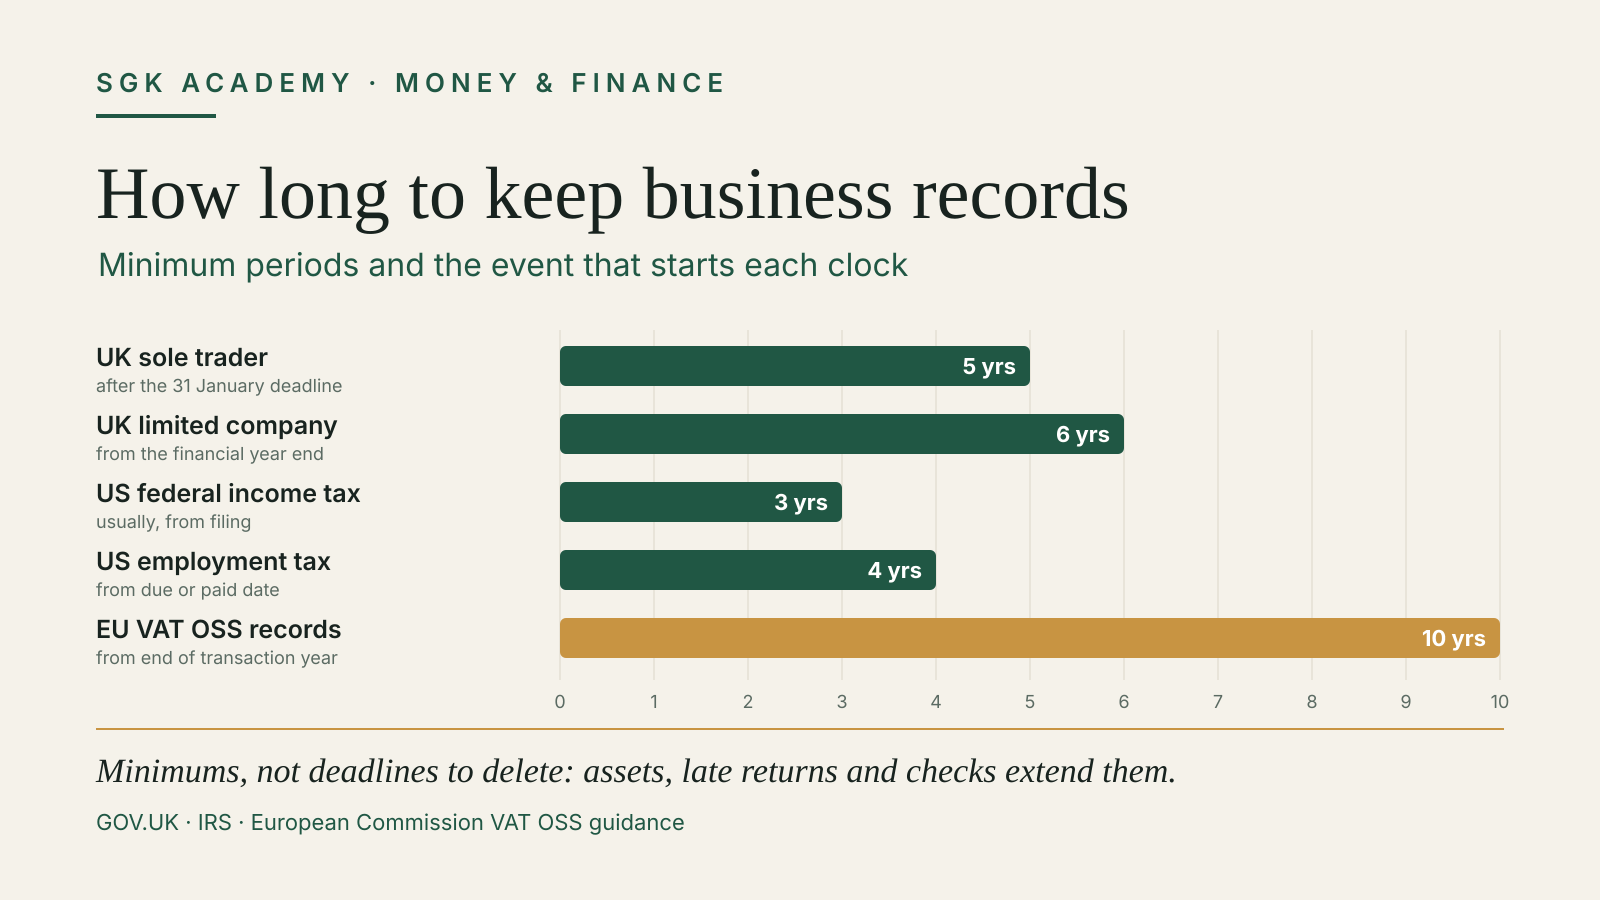
Bar chart of minimum record retention periods: UK sole trader 5 years, UK company 6 years, US federal tax 3 years, US employment tax 4 years, EU VAT OSS 10 years.
Business records ·

How Long to Keep Business Records: UK, US and EU OSS

A practical retention map for UK, US and EU VAT OSS business records, with the exceptions that extend it.
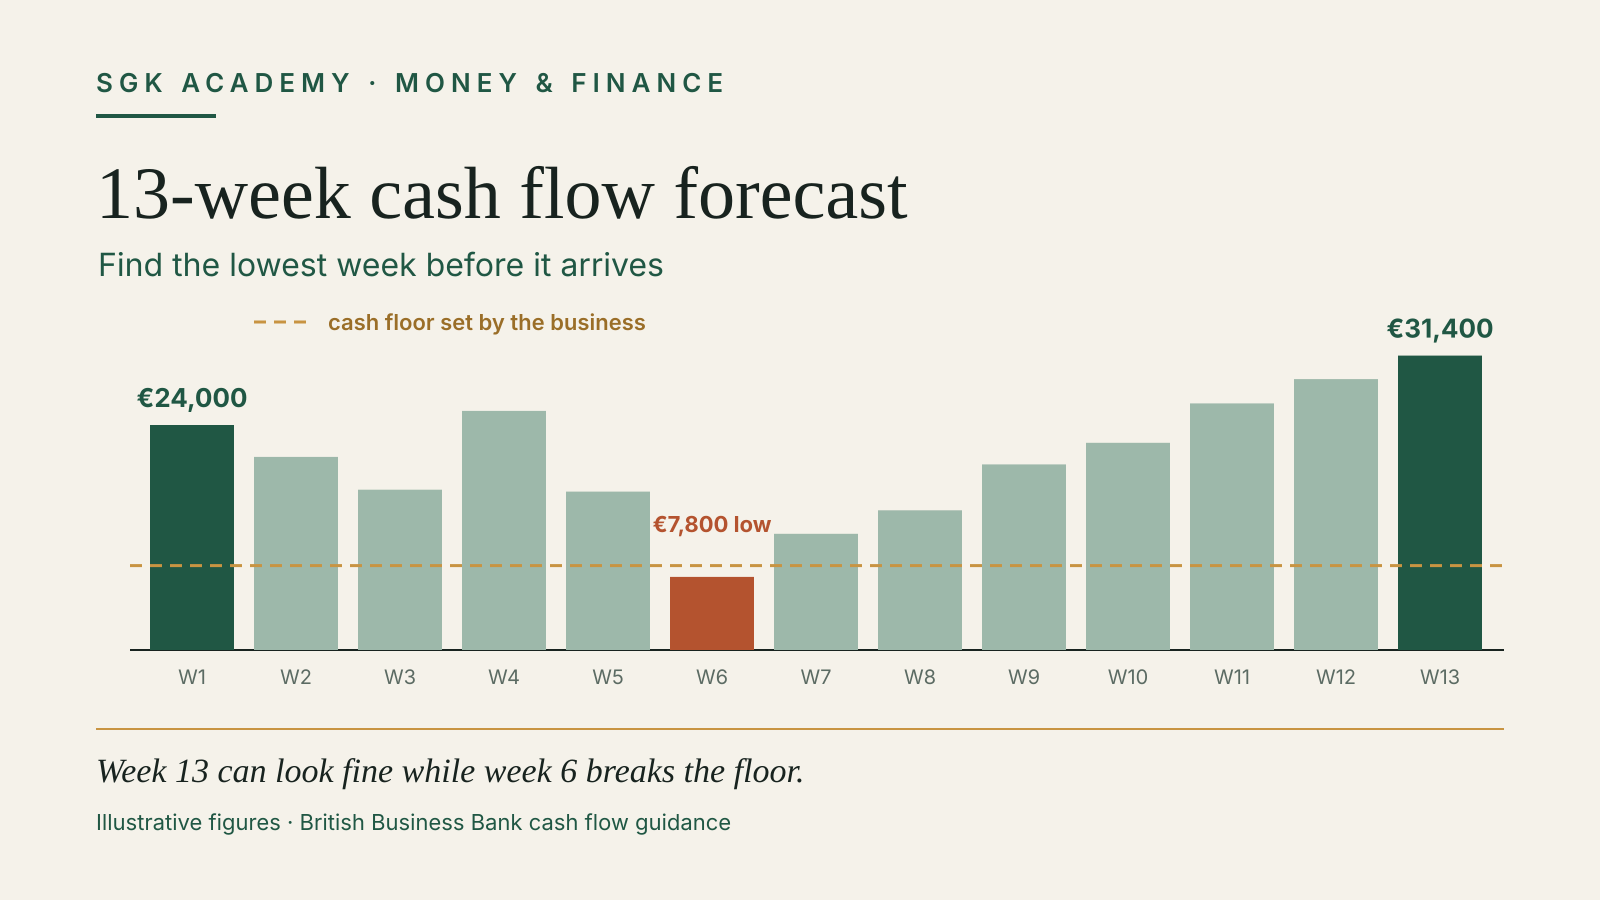
Bar chart of a 13-week cash flow forecast: opening cash of €24,000 falls to a low of €7,800 in week 6, below the cash floor, then recovers to €31,400 by week 13.
Cash flow ·

13-Week Cash Flow Forecast: A Small-Business Guide

Build a rolling 13-week cash flow forecast, find the lowest cash week and turn gaps into dated actions.
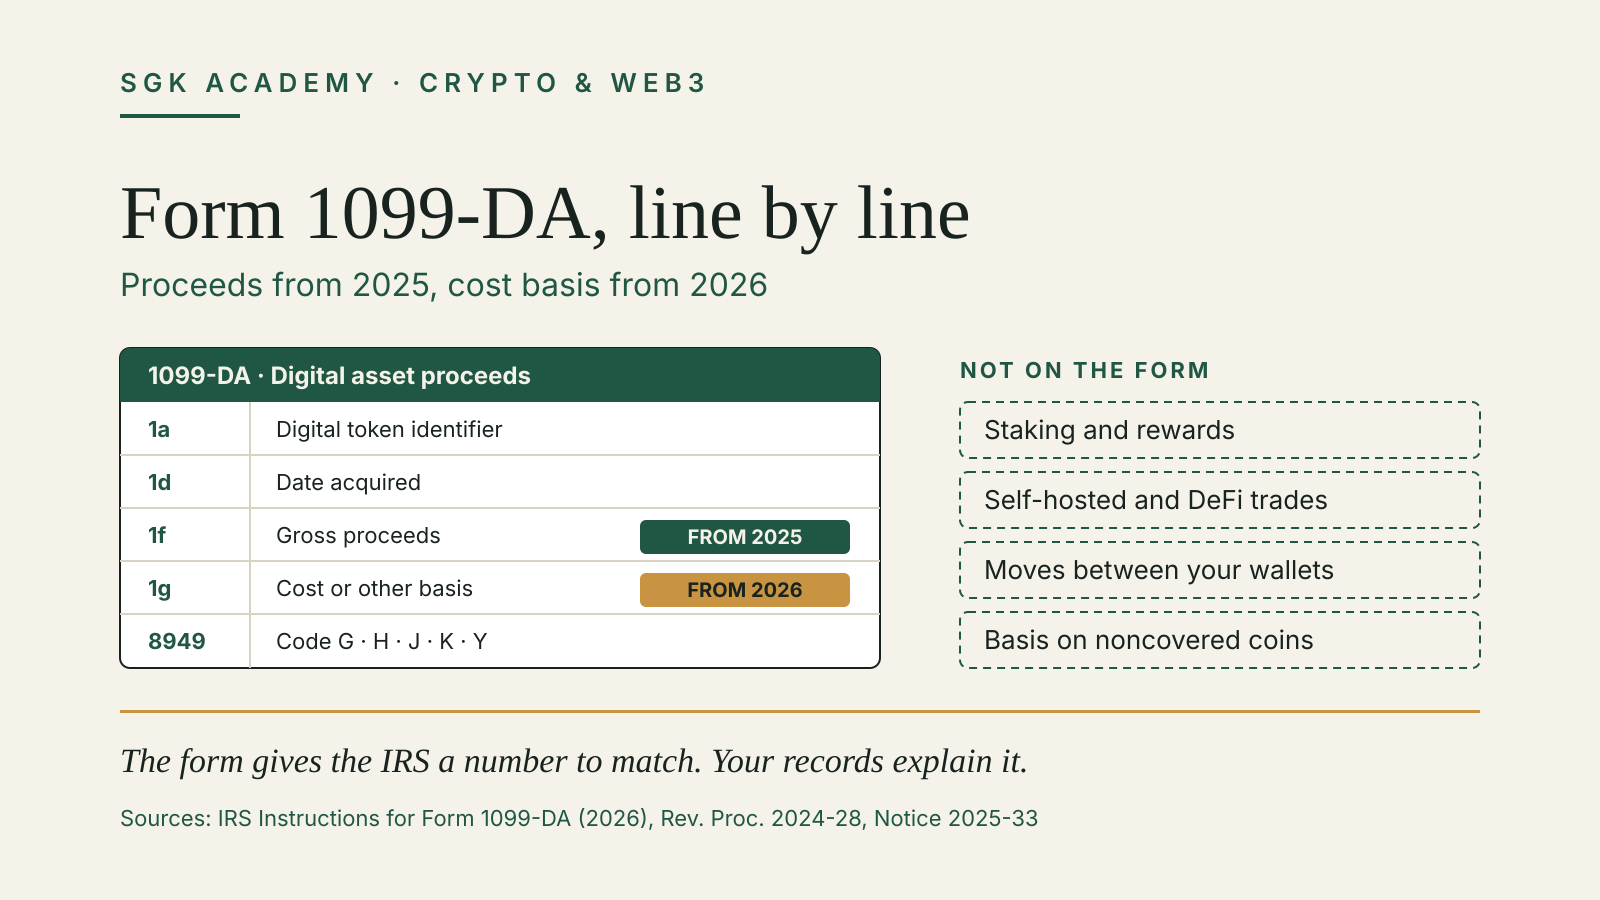
Diagram of Form 1099-DA boxes 1a, 1d, 1f and 1g, showing gross proceeds reported from 2025 and cost basis from 2026, beside items not on the form such as staking and wallet transfers
Crypto tax ·

Form 1099-DA Explained for Crypto Sellers and Founders

What Form 1099-DA shows for crypto sales from 2025, when basis appears from 2026, and how to reconcile it.
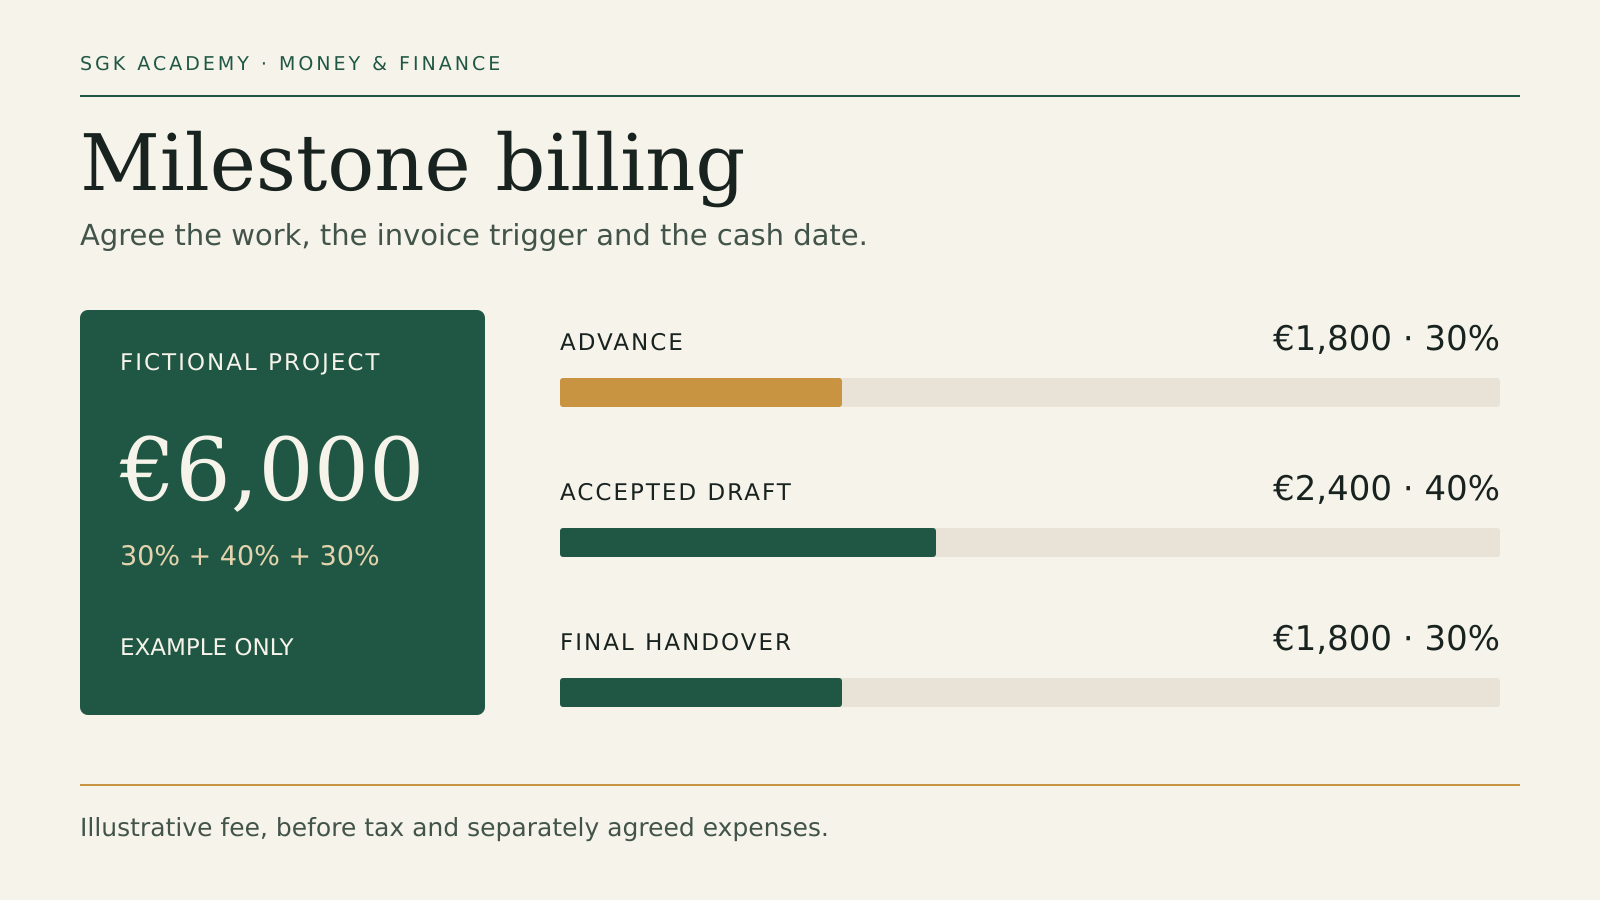
A fictional €6,000 project split into a €1,800 advance, €2,400 accepted draft and €1,800 final handover.
invoicing ·

Milestone Billing: Plan the Work and Payment Dates

A practical milestone billing plan with acceptance checks, invoice dates and a clearly labelled €6,000 example.
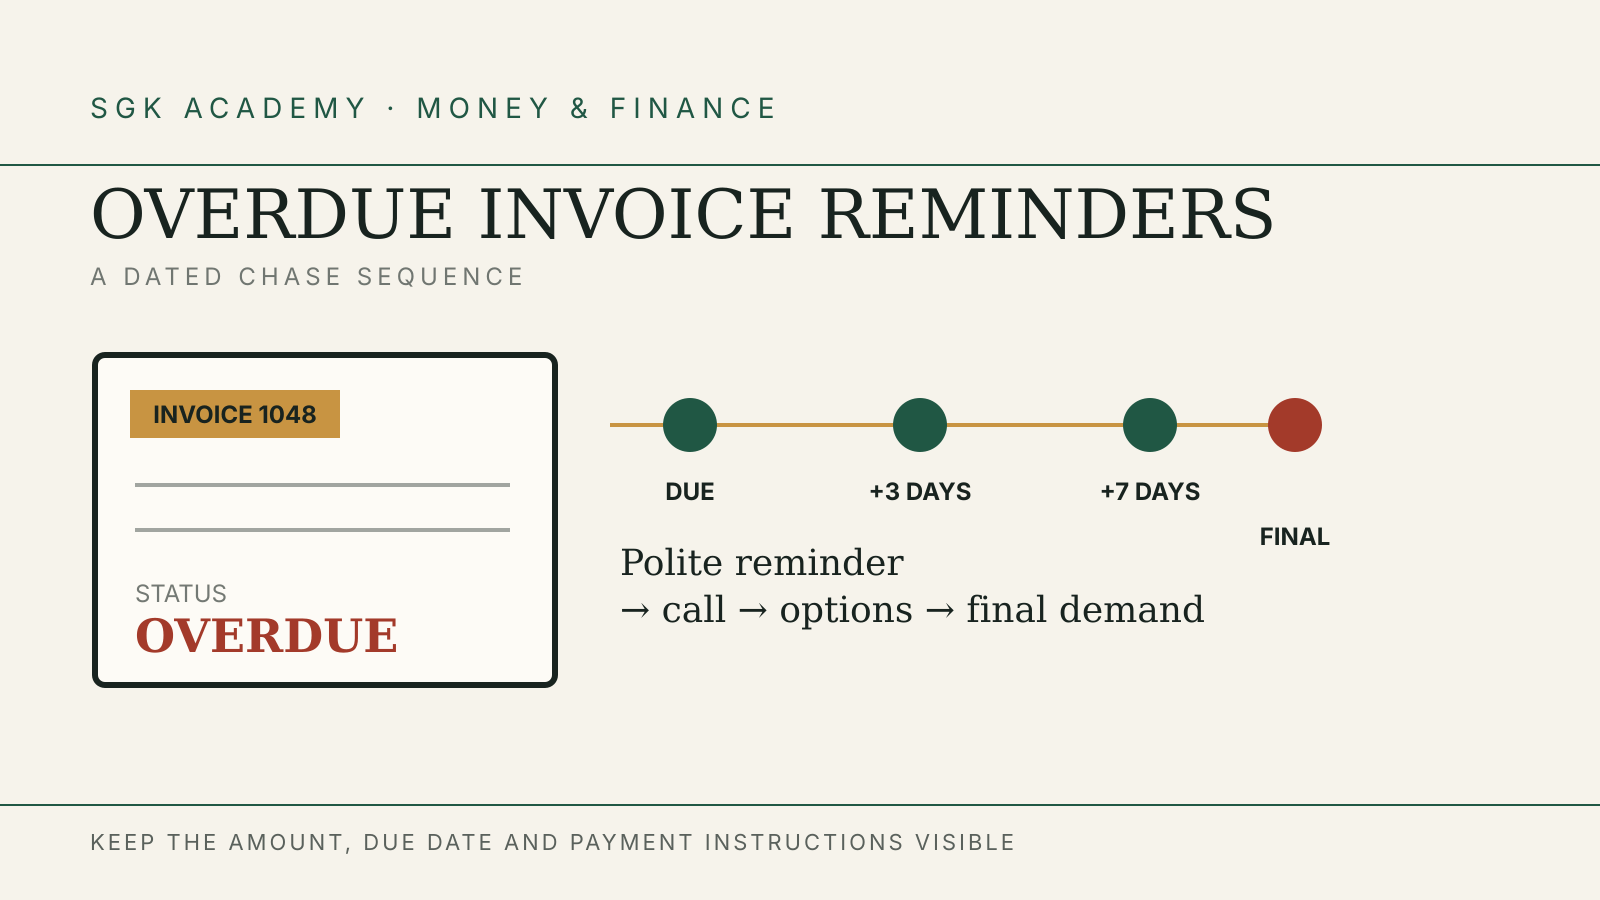
Overdue invoice marked overdue beside a reminder timeline: due date, plus 3 days, plus 7 days and final demand
invoicing ·

Overdue Invoice Reminder: A Dated Chase Sequence

A dated reminder sequence to verify an overdue invoice, chase it, offer options and escalate accurately.
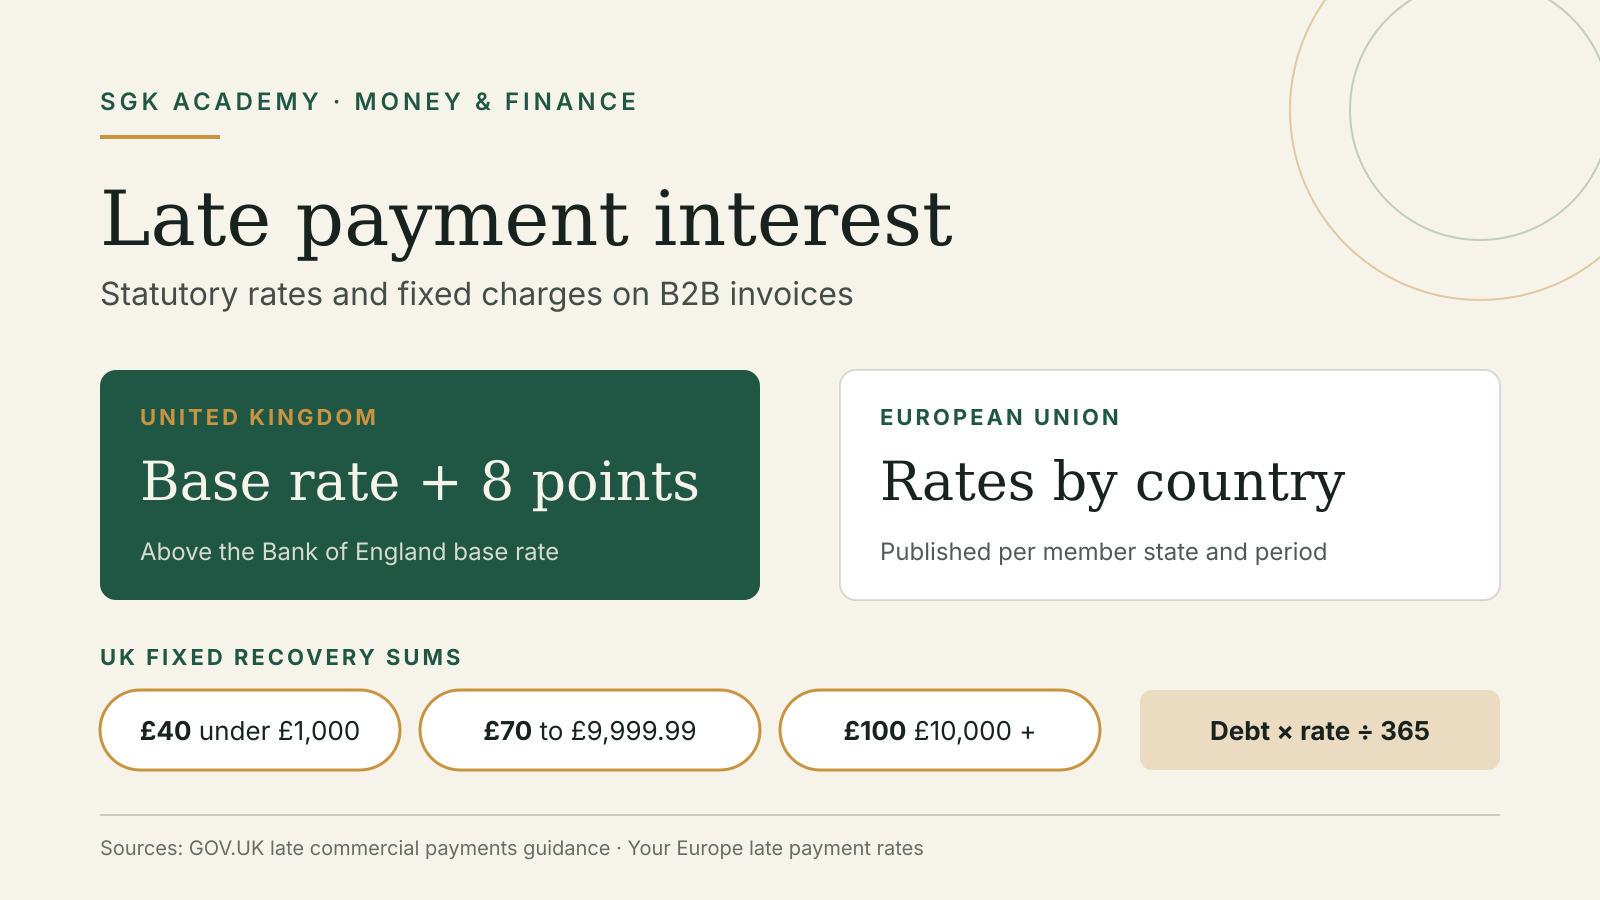
Late payment interest summary: UK statutory rate of base rate plus 8 points, EU rates set by country, UK fixed recovery sums of £40, £70 and £100, and the daily formula debt times rate divided by 365
late payments ·

Late Payment Interest on B2B Invoices: UK and EU Guide

How to calculate UK and EU late-payment interest, fixed recovery charges and the correct start date.
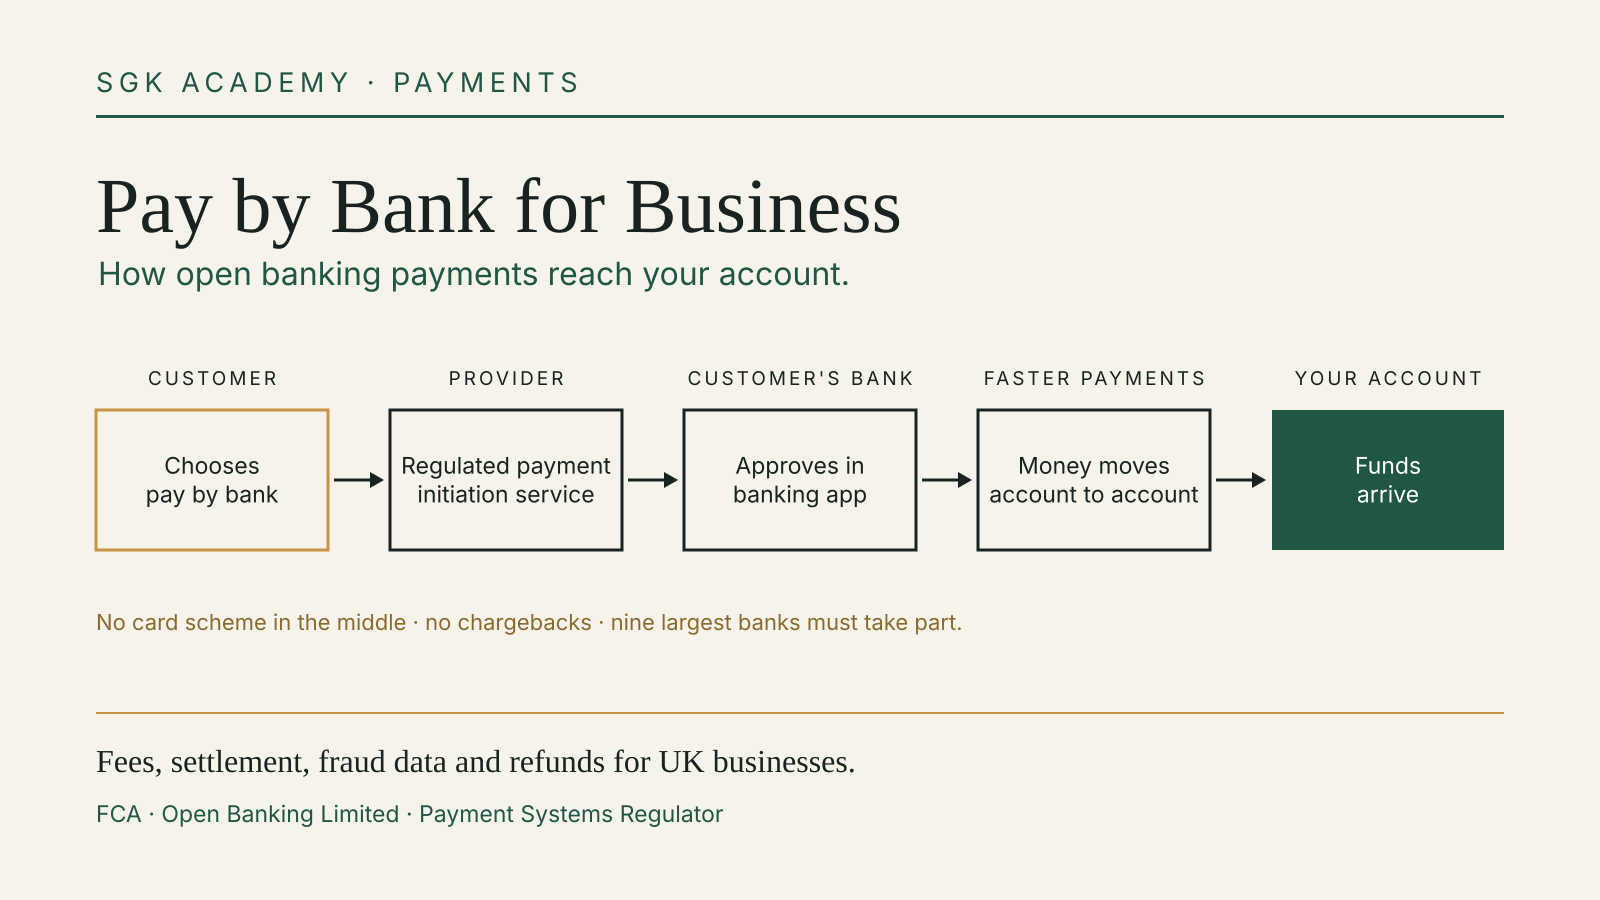
Pay by bank flow: the customer chooses pay by bank, a regulated provider initiates the payment, the customer approves it in their banking app and Faster Payments moves the funds to the business account.
Open banking ·

Pay by Bank for Business: How Open Banking Payments Work

How pay by bank works for UK businesses: open banking checkout, fees, settlement, VRPs and refunds.
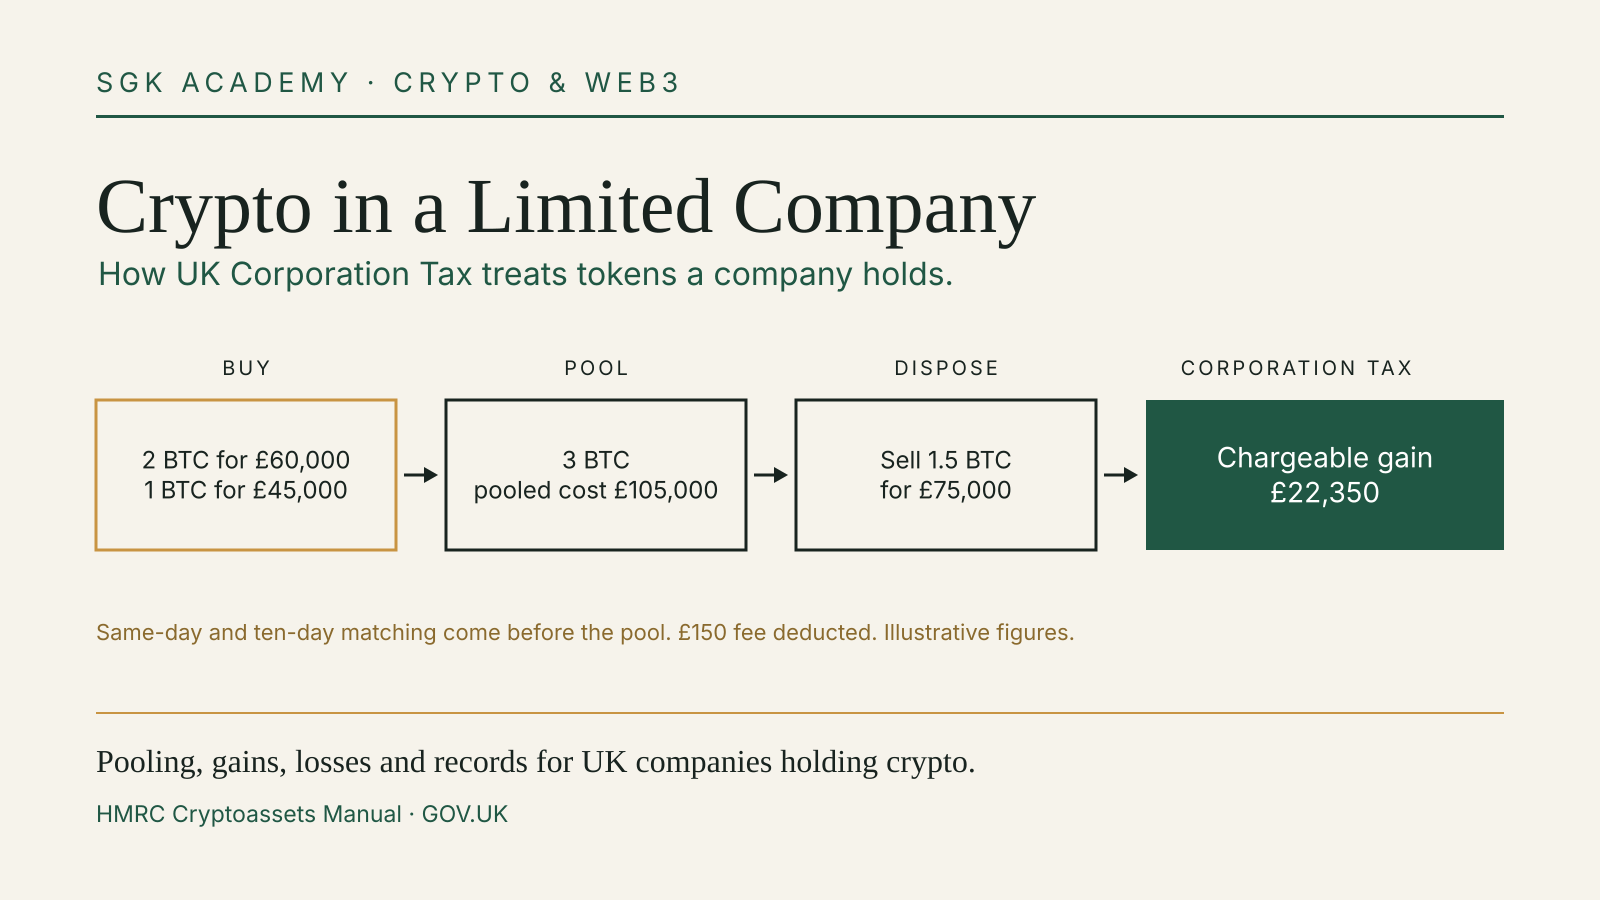
Diagram of a company buying 3 BTC for £105,000, pooling the cost, selling 1.5 BTC for £75,000 and reporting a £22,350 chargeable gain for Corporation Tax.
Crypto tax ·

Crypto in a Limited Company: How UK Corporation Tax Treats Tokens

How HMRC taxes bitcoin and other tokens held by a UK limited company, from pooling to losses.
Four marked quarterly tax dates on a green and gold calendar beside a payment record
Estimated tax ·

US Estimated Tax Payments for Self-Employed People in 2026

How self-employed people calculate, schedule and record 2026 US federal estimated tax payments.
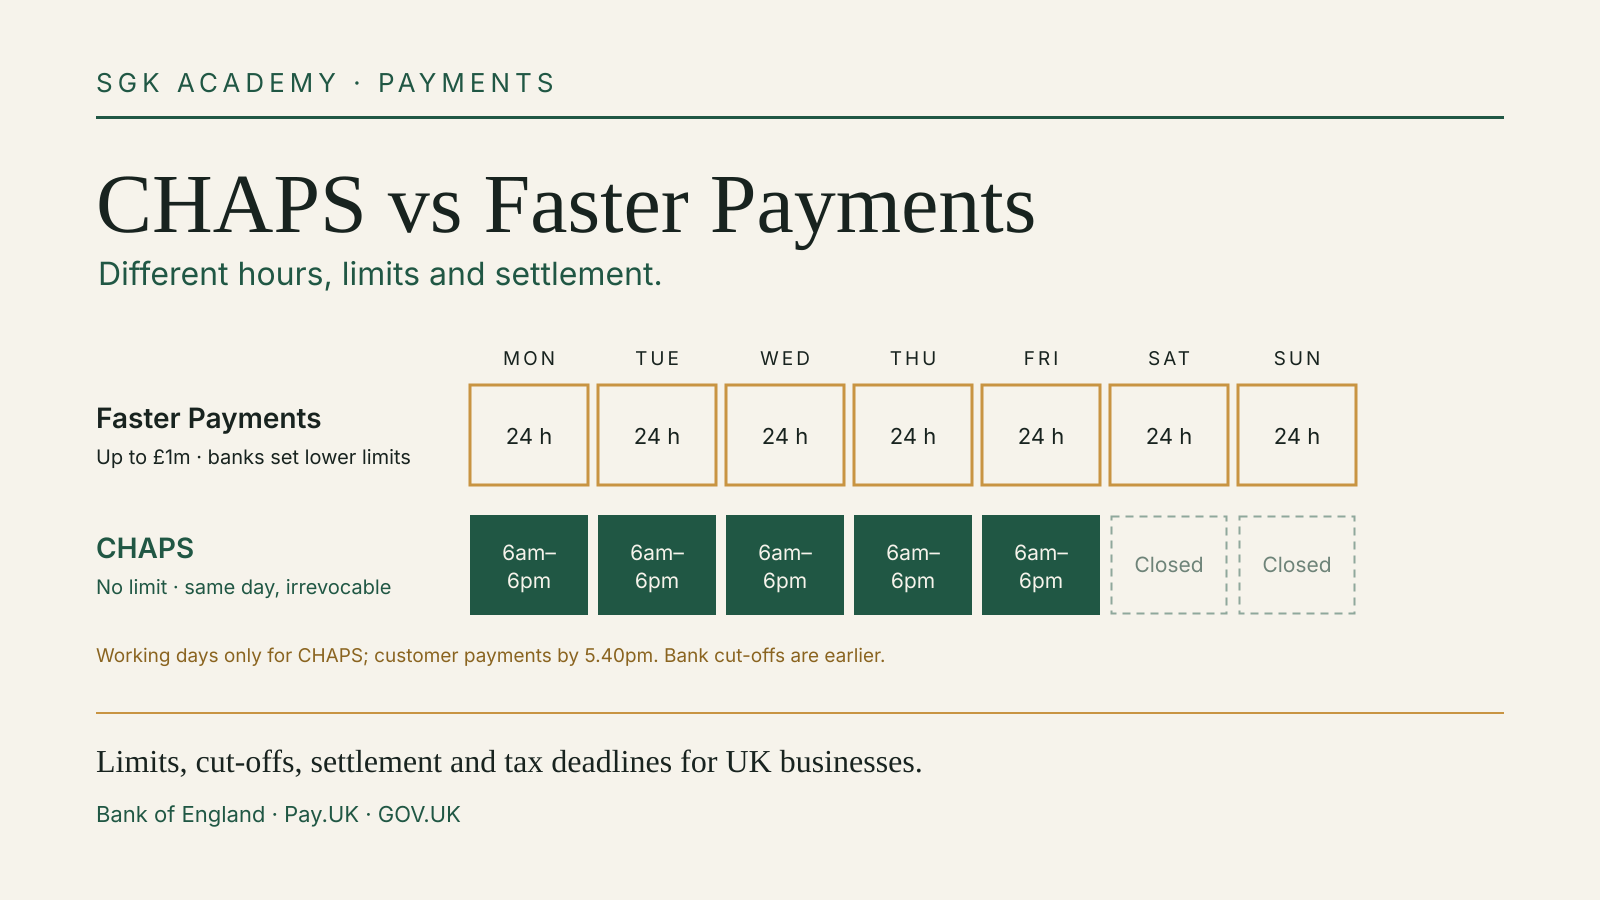
CHAPS ·

CHAPS vs Faster Payments: Which UK Transfer to Use for Business

Hours, limits, settlement and cut-offs of the two UK systems, and which to use for large or deadline payments.
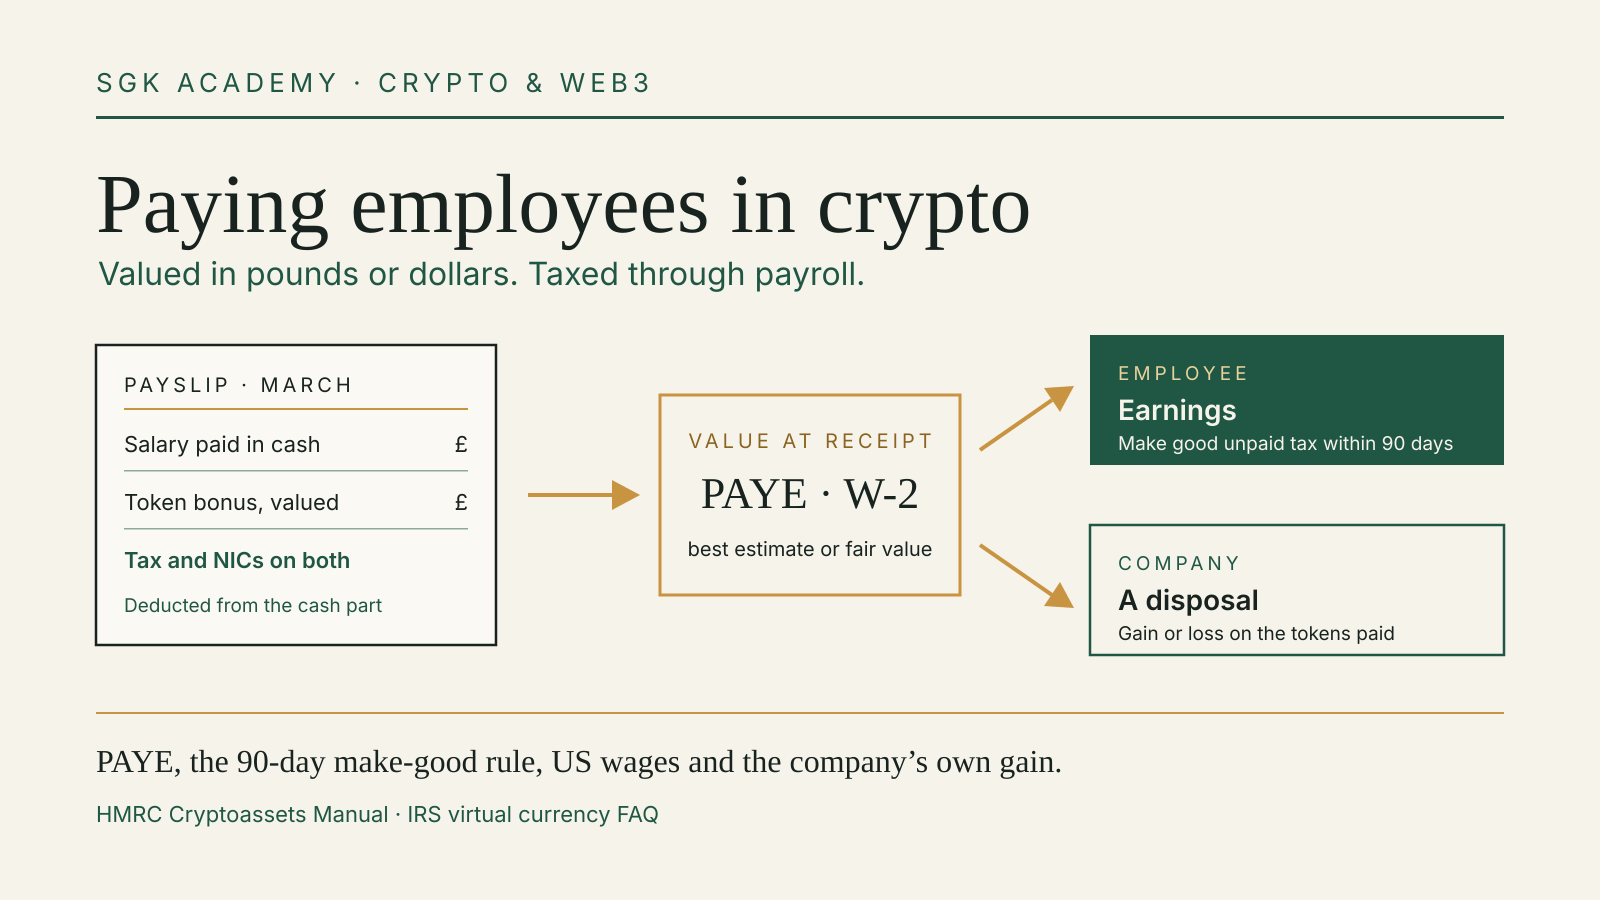
Crypto payroll ·

Paying Employees in Crypto: PAYE, Payroll Tax and Records

How PAYE, NICs, US withholding and the employer's own gain apply when staff are paid in tokens.

SGK Academy

What are you looking for?

Search a topic, product or question