
Guides: VAT

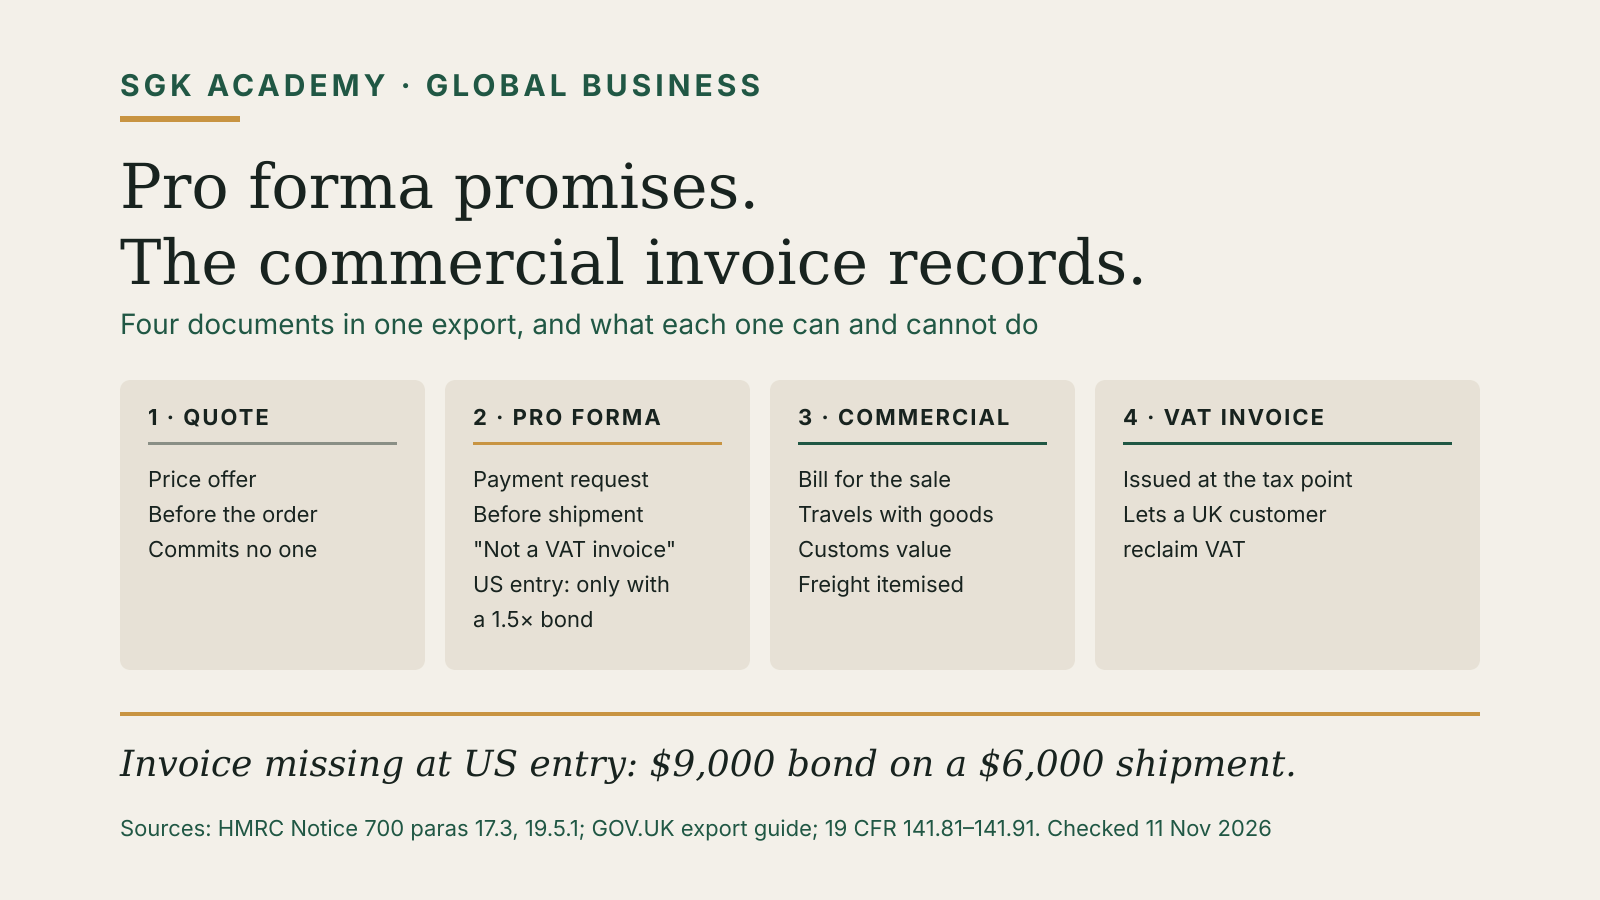
Four export documents compared: a quote is a price offer before the order; a pro forma invoice is a payment request before shipment, marked not a VAT invoice, and accepted at US entry only with a bond of 1.5 times the value; a commercial invoice is the bill for the sale that travels with the goods and sets the customs value with freight itemised; a VAT invoice is issued at the tax point and lets a UK customer reclaim VAT. Example: a missing invoice at US entry means a $9,000 bond on a $6,000 shipment.
invoicing ·

Pro Forma Invoice vs Commercial Invoice: What Each Does

A pro forma asks for payment before shipment; a commercial invoice records the sale and sets the customs value.
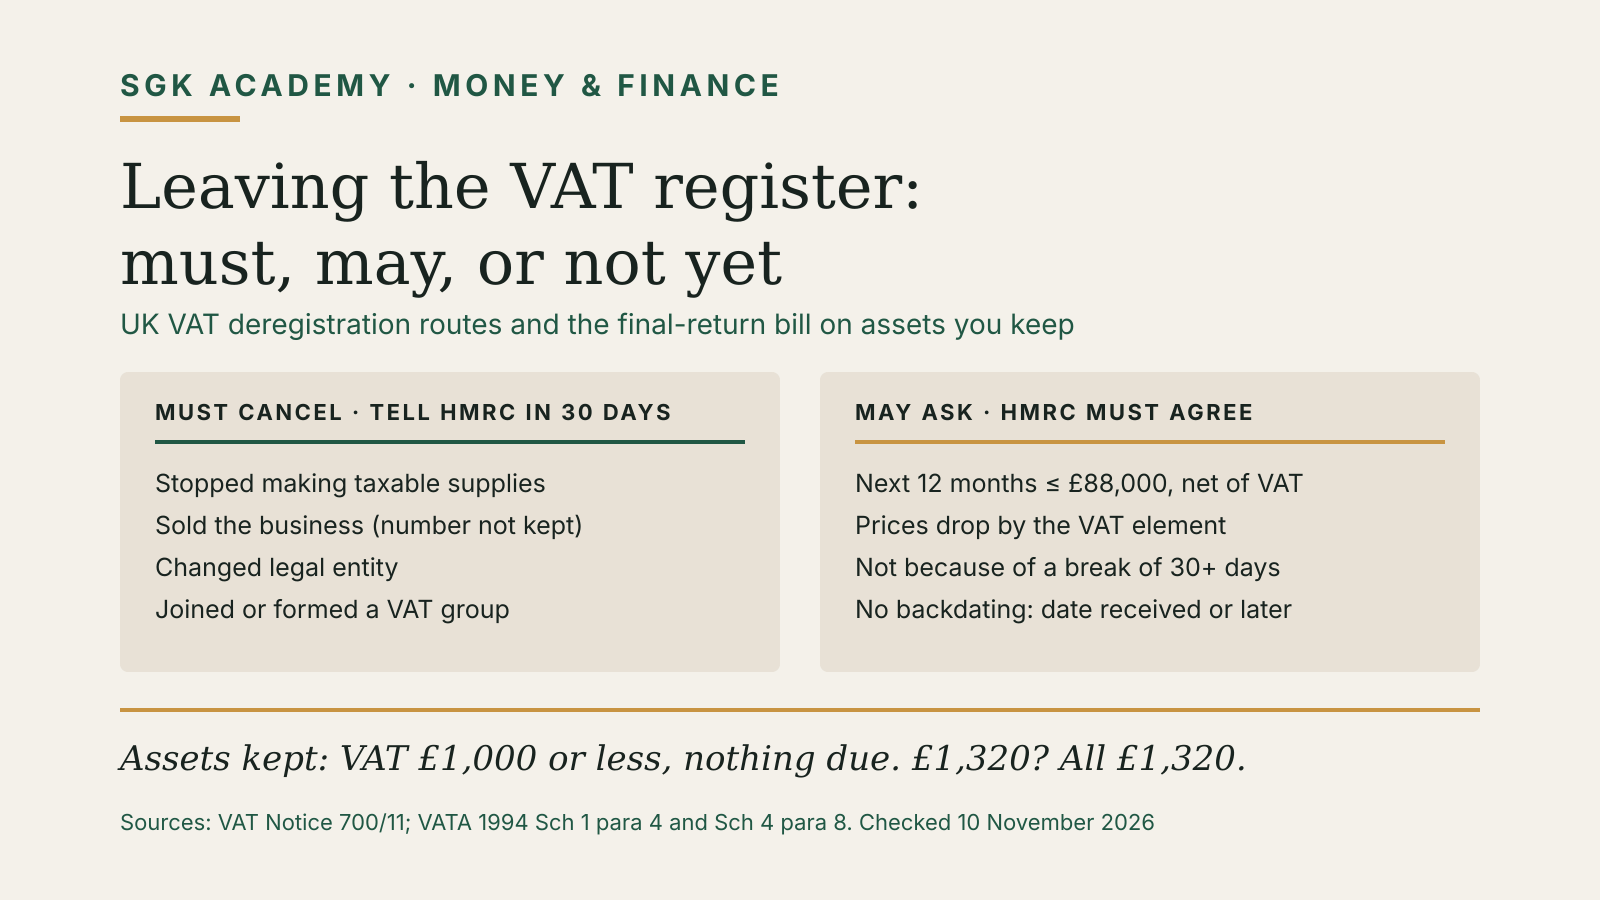
UK VAT deregistration routes compared: you must cancel and tell HMRC within 30 days if you stop making taxable supplies, sell the business without the number, change legal entity or join a VAT group; you may ask HMRC to cancel if VAT-exclusive turnover in the next 12 months will not exceed £88,000, prices drop by the VAT element, the fall is not due to a break of 30 days or more, and the date is not backdated. VAT on assets kept is nothing if £1,000 or less, otherwise all of it, for example £1,320.
VAT ·

VAT Deregistration: When You Must Cancel and When You May

When you must cancel UK VAT registration, when you may below £88,000, and the VAT due on assets you keep.
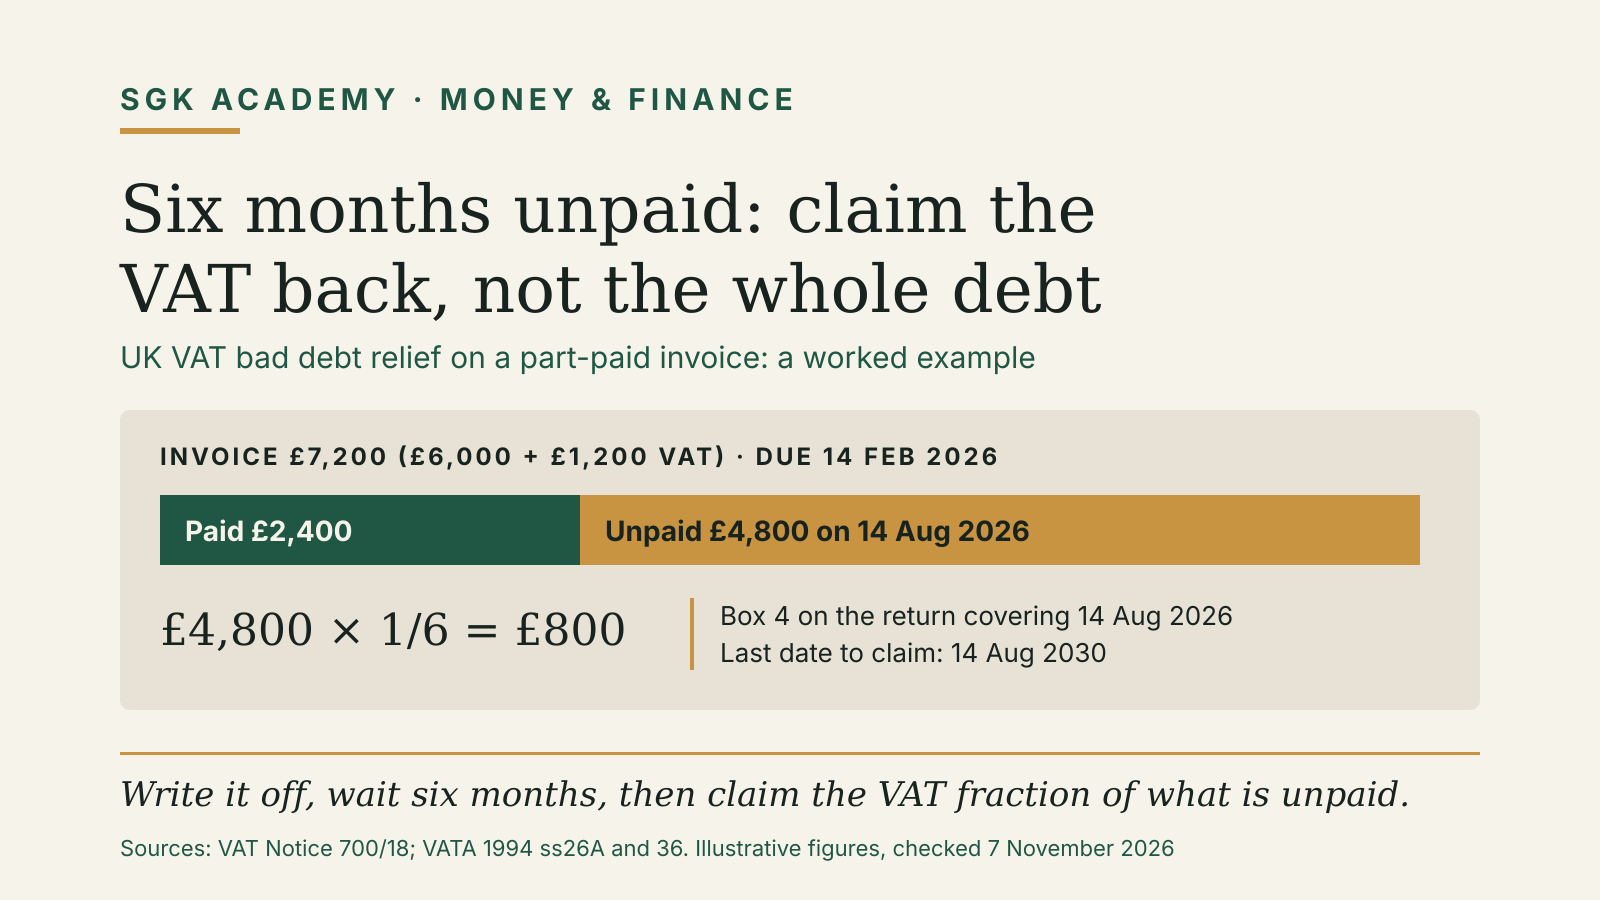
Worked example of UK VAT bad debt relief: a £7,200 invoice (£6,000 plus £1,200 VAT) due 14 February 2026, £2,400 paid and £4,800 unpaid on 14 August 2026; relief is £4,800 × 1/6 = £800, claimed in box 4 of the VAT return covering 14 August 2026, with a last claim date of 14 August 2030.
VAT ·

Bad Debt Relief VAT: Reclaiming VAT on an Unpaid Invoice

Reclaim the VAT on an unpaid invoice once it is six months overdue: conditions, VAT Return boxes and a worked example.
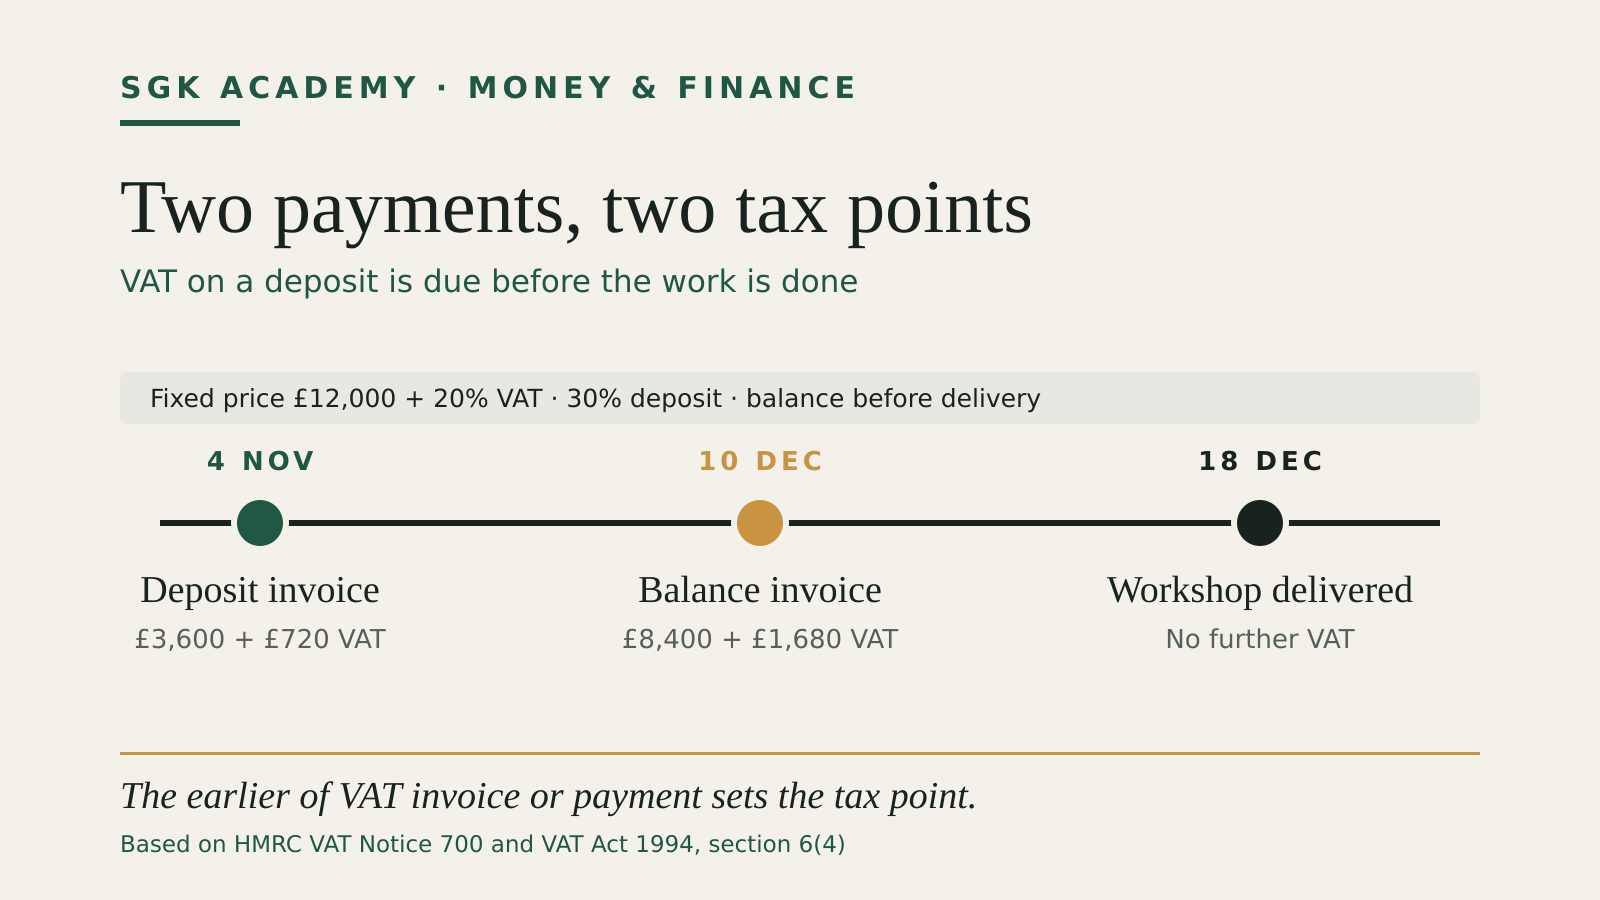
Timeline of a £12,000 project: deposit invoice on 4 November with £720 VAT, balance invoice on 10 December with £1,680 VAT, and no further VAT at delivery on 18 December
VAT ·

VAT on Deposits and Advance Payments

When a customer deposit creates a UK VAT tax point, how refundable security differs, and what to record.
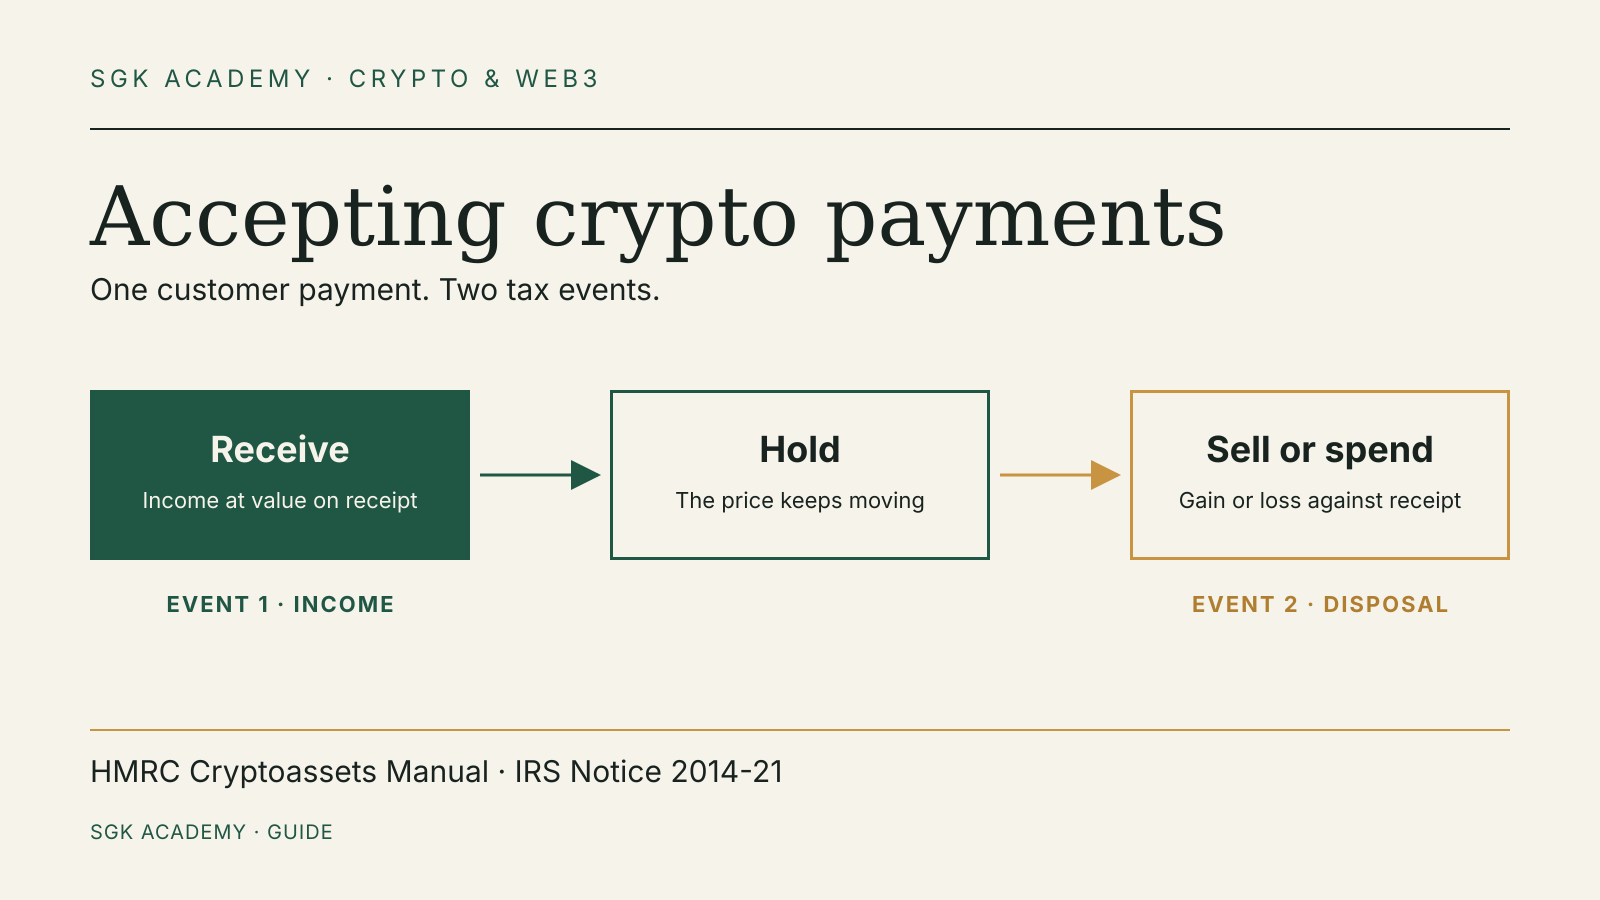
A crypto payment as three steps: receive (income at value on receipt), hold (the price keeps moving), sell or spend (gain or loss against receipt)
Crypto tax ·

Accepting Crypto Payments as a Small Business: Tax, VAT and Records

How UK and US rules treat crypto a business receives as payment, the VAT position and the records to keep.
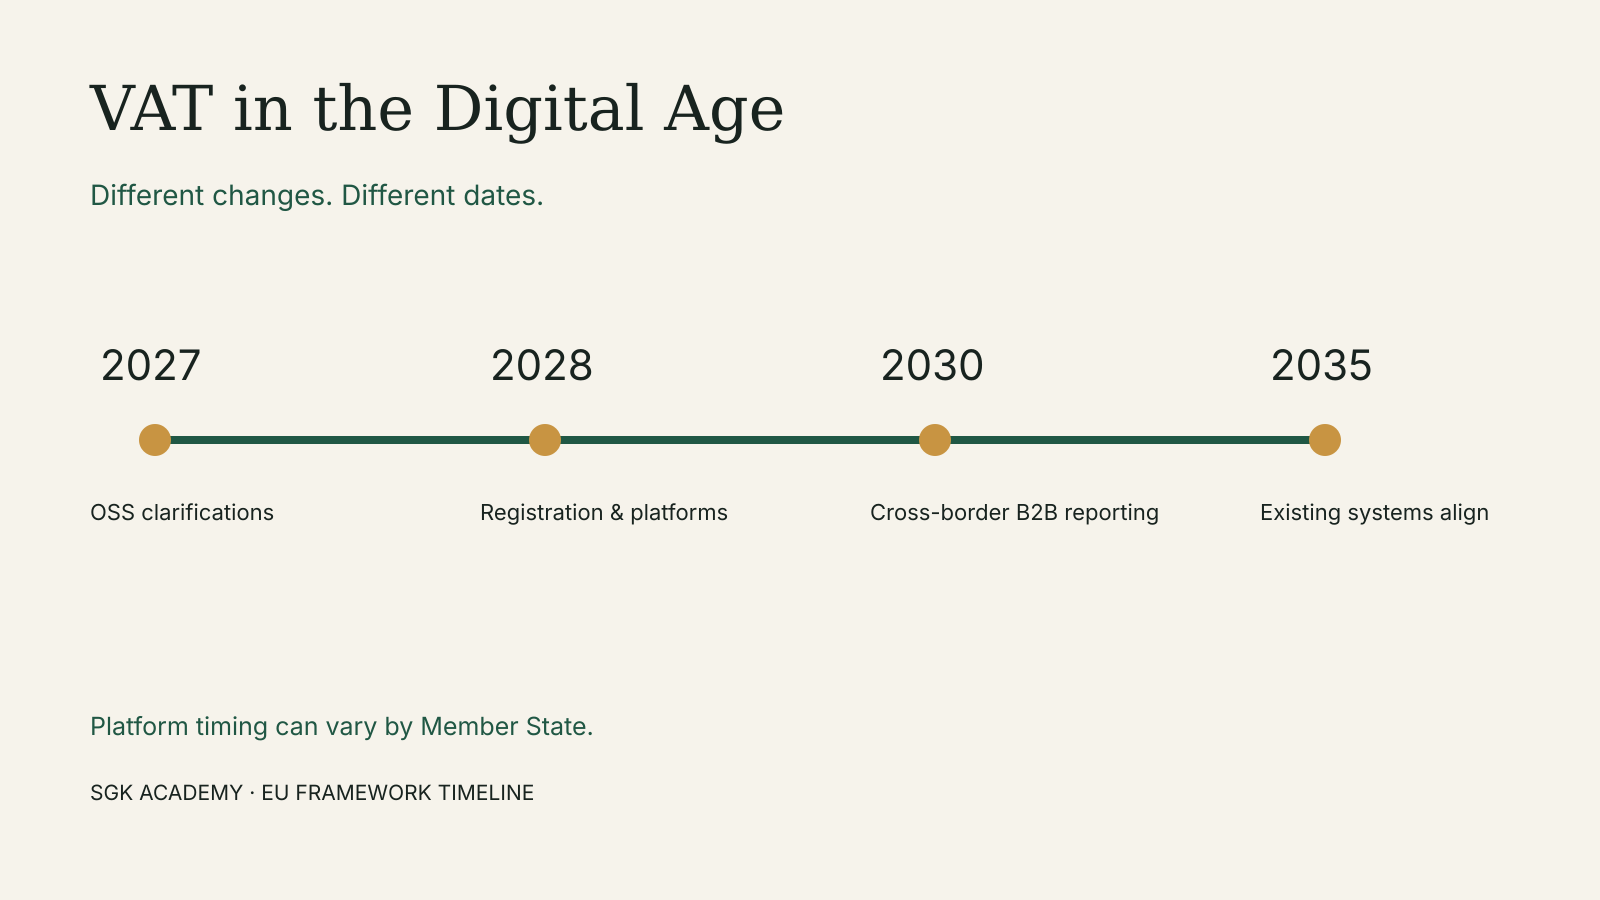
ViDA timeline: OSS changes in 2027, registration and platforms from 2028, cross-border reporting in 2030, existing systems aligning by 2035.
VAT ·

VAT in the Digital Age: what changes for small businesses from 2027

The ViDA timetable and the sales, invoice and software checks a small business can prepare.
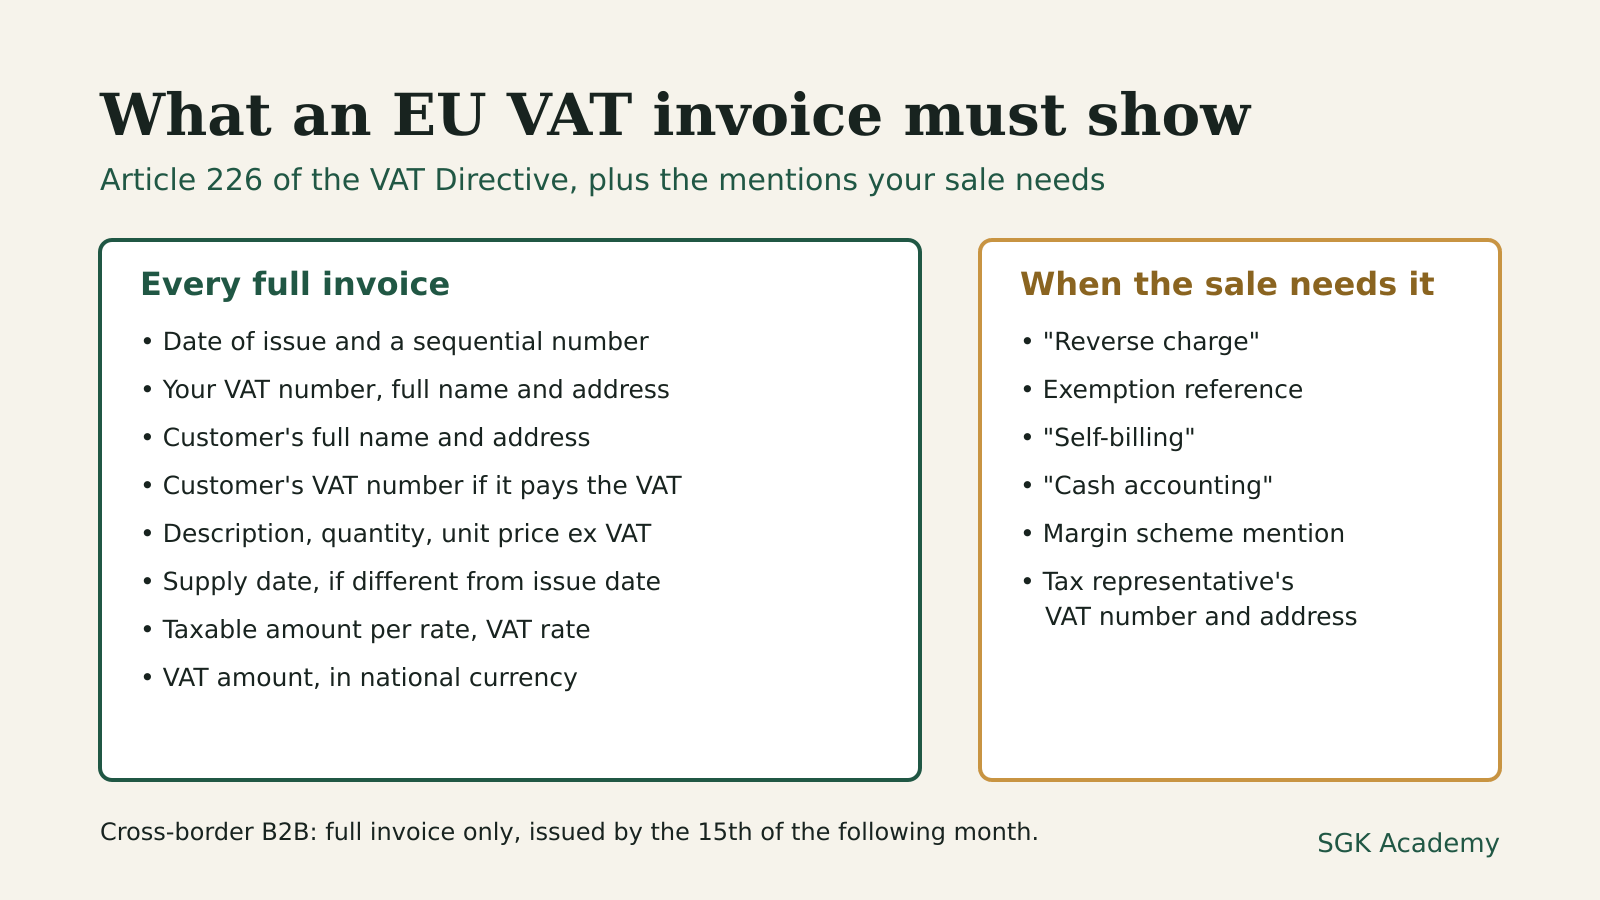
Diagram listing what every full EU VAT invoice must show (date and sequential number, both parties' names and addresses, VAT numbers, description and unit price, supply date, taxable amount per rate, VAT rate and amount in national currency) and the mentions some sales need (reverse charge, exemption reference, self-billing, cash accounting, margin scheme, tax representative).
VAT ·

VAT Invoice Requirements: What an EU Invoice Must Show

The details every EU VAT invoice needs under Article 226, the extra mentions, simplified invoices and deadlines.
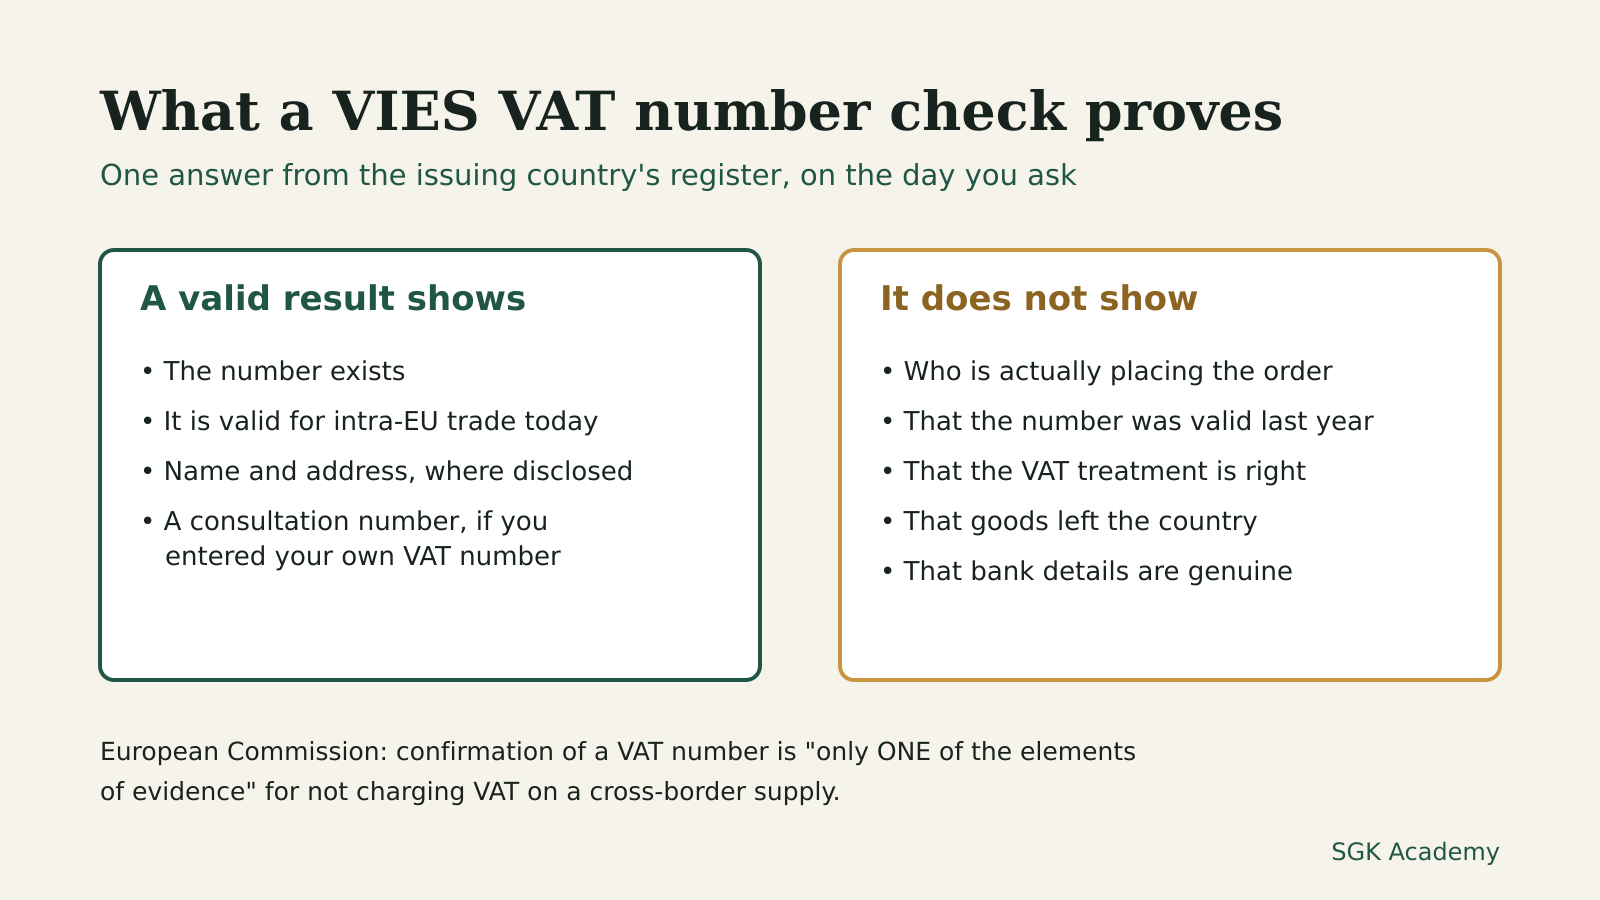
Diagram comparing what a valid VIES VAT number check shows (the number exists, is valid for intra-EU trade today, name and address where disclosed, a consultation number) with what it does not show (who places the order, past validity, correct VAT treatment, goods leaving the country, genuine bank details).
VAT ·

VIES VAT Number Check: What a Valid Result Proves

A valid VIES result lets you treat a customer as a business. How to run a check you can prove later, and its limits.
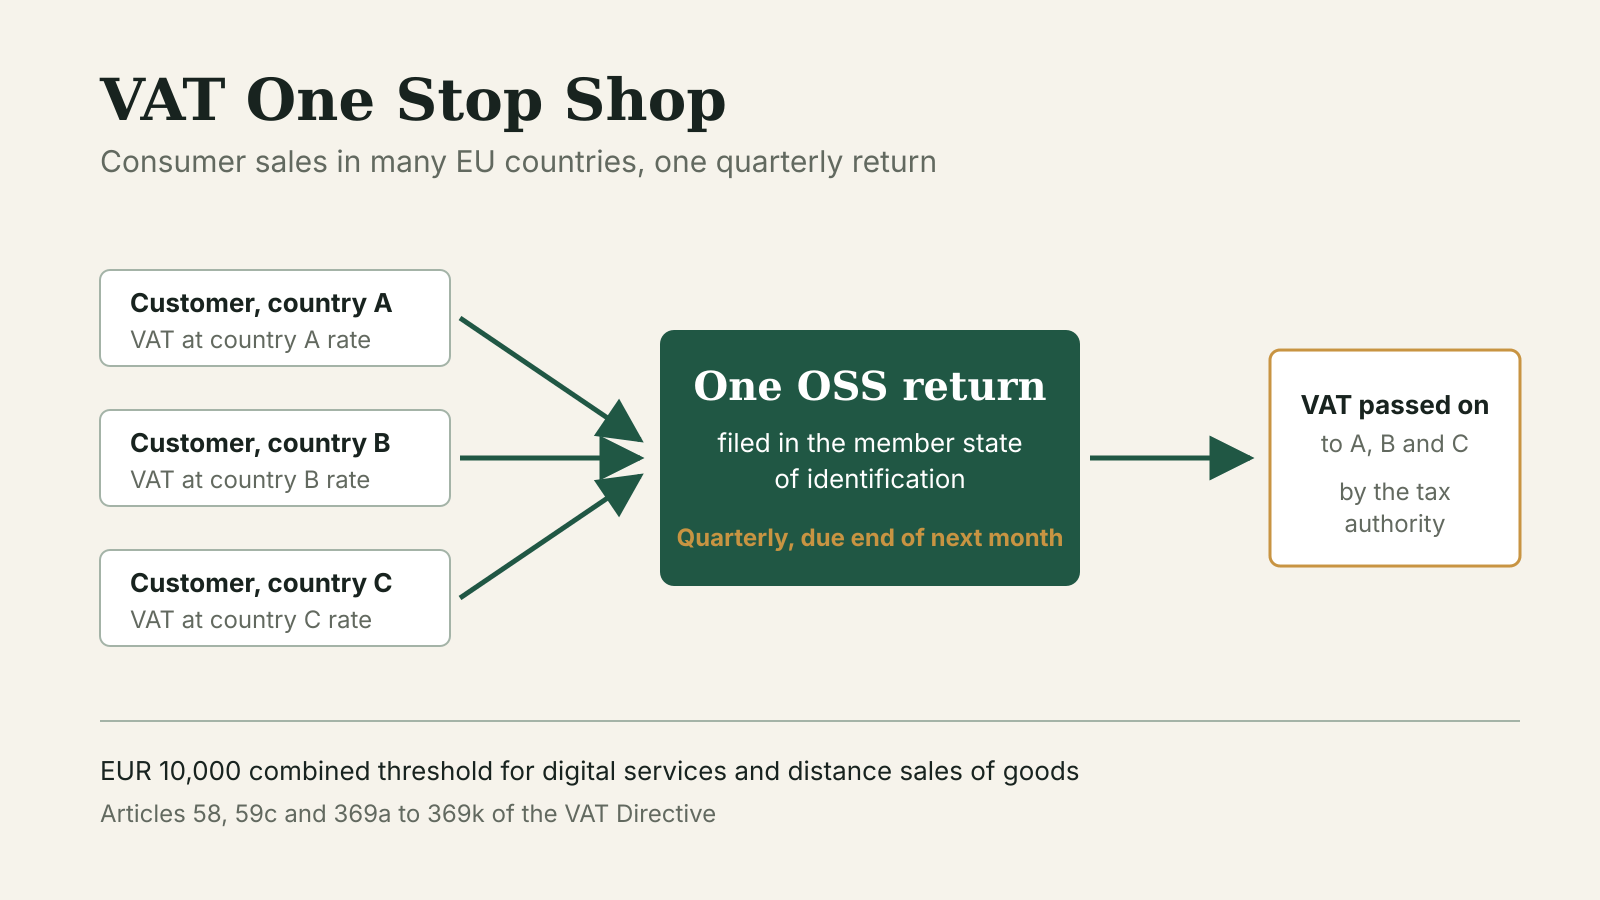
Diagram of the VAT One Stop Shop: sales to consumers in countries A, B and C, each at that country's VAT rate, go into one quarterly OSS return filed in the member state of identification, which passes the VAT on.
VAT ·

VAT One Stop Shop (OSS): One Return for EU Consumer Sales

How the EU One Stop Shop that replaced MOSS works, the EUR 10,000 threshold and what changes in 2027.
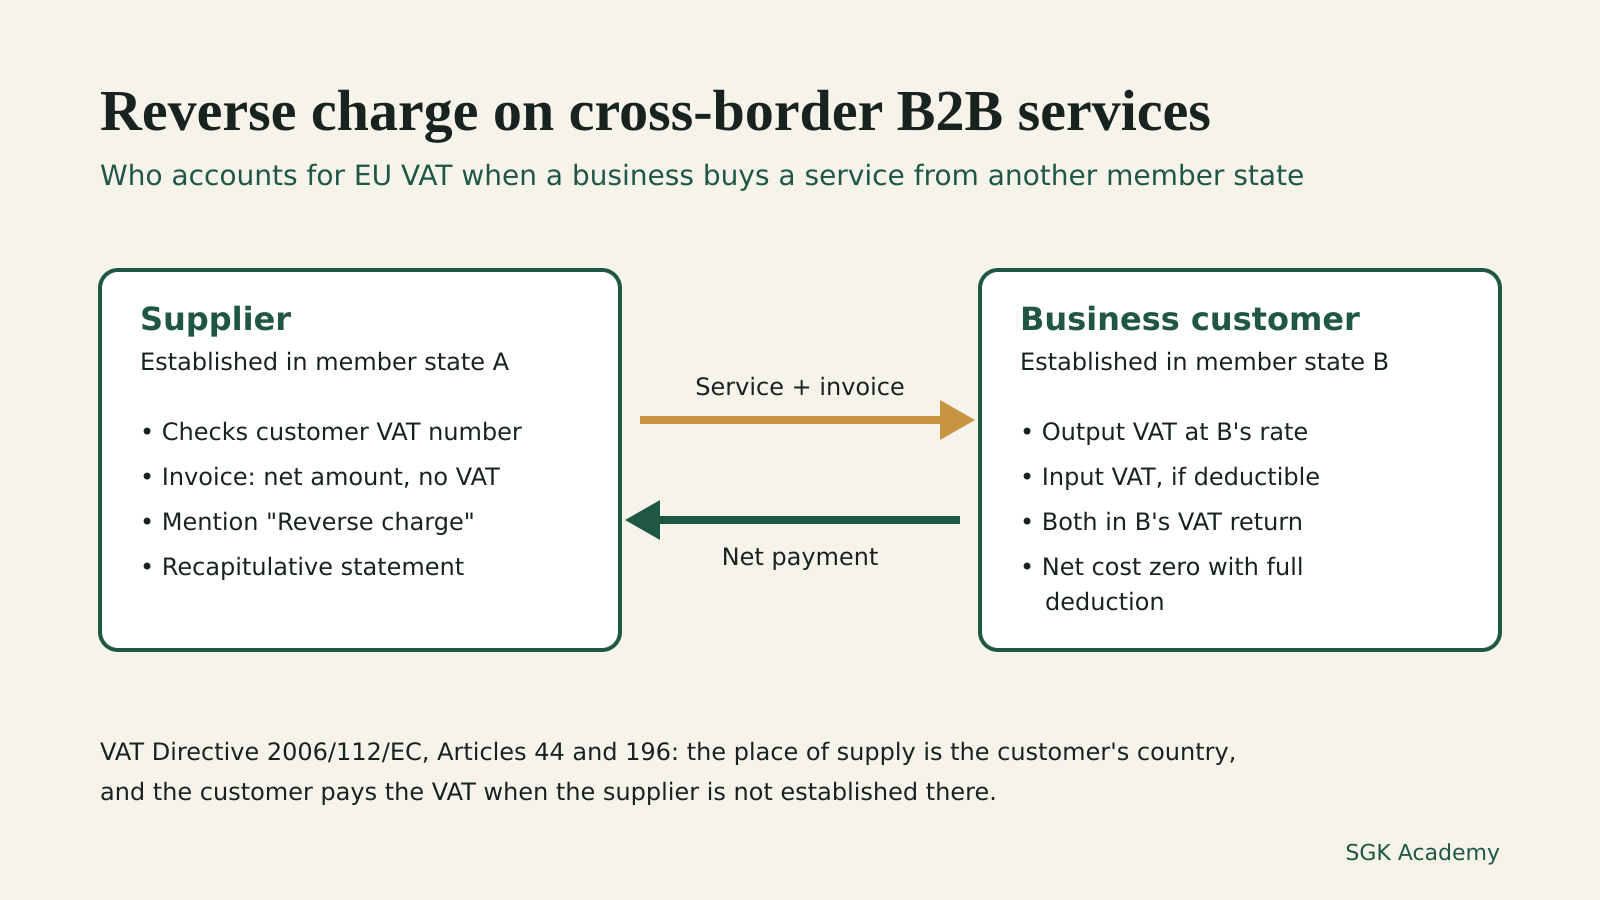
Diagram of the EU reverse charge: a supplier in member state A invoices a business customer in member state B without VAT, and the customer records output and input VAT in its own return.
VAT ·

Reverse Charge VAT on Services in the EU: Who Pays and What to Invoice

When a business buys a service from another EU country, it usually pays the VAT itself. What each side records.
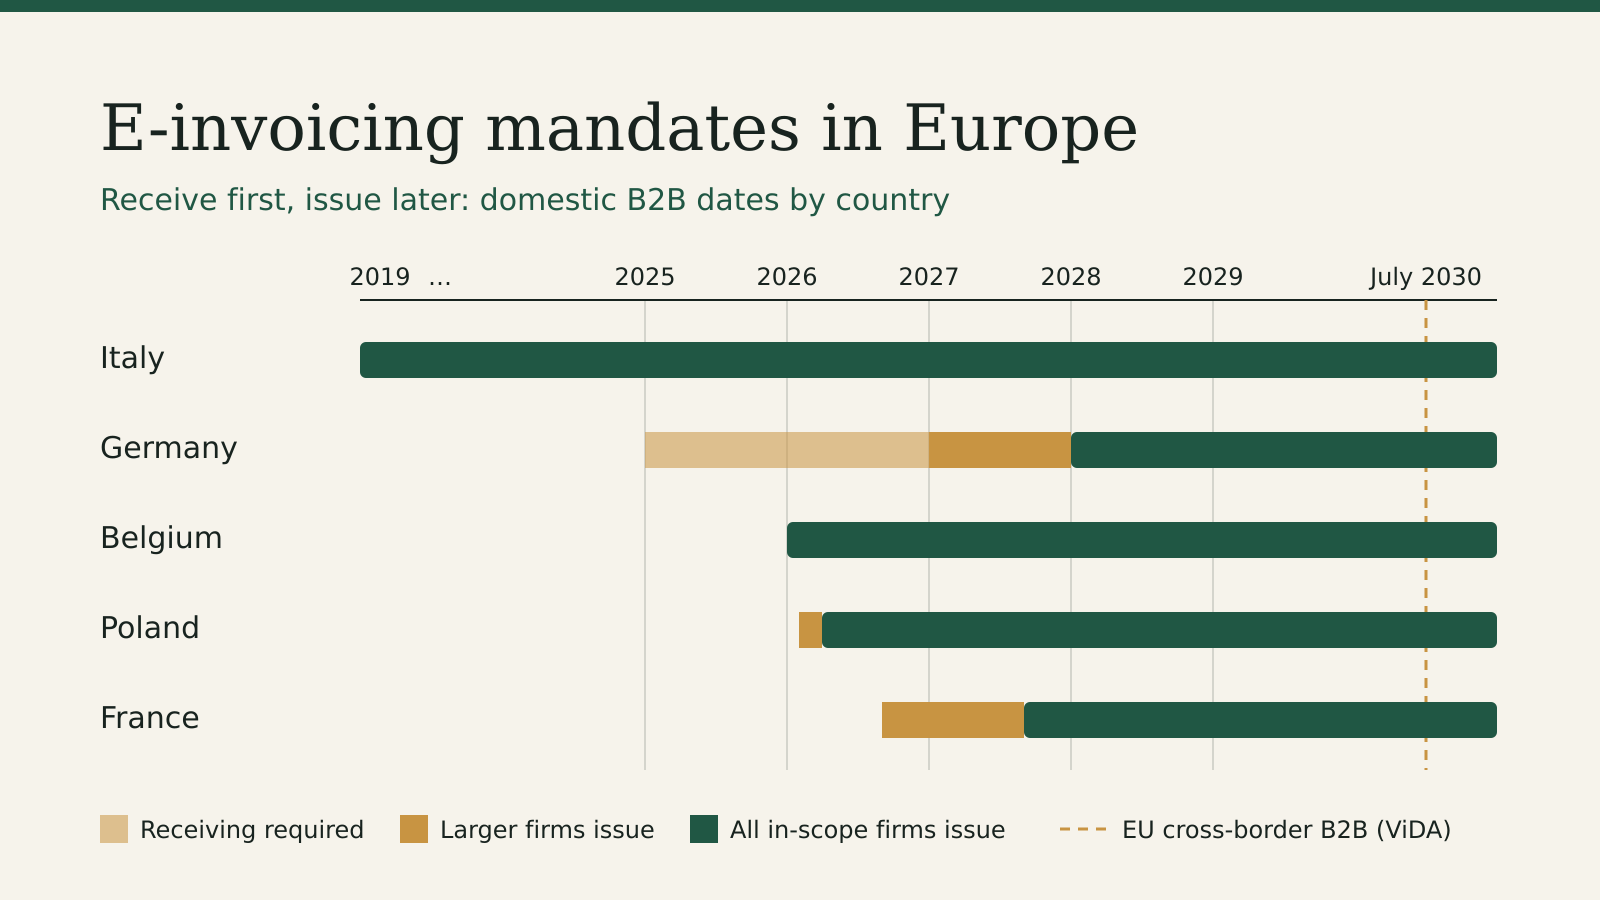
Timeline of domestic B2B e-invoicing mandates in Italy, Germany, Belgium, Poland and France, from 2019 to the EU cross-border rules in July 2030.
e-invoicing ·

E-Invoicing Mandates in Europe: Who Must Send and Receive, and When

When businesses in five EU countries must receive and issue structured B2B invoices.
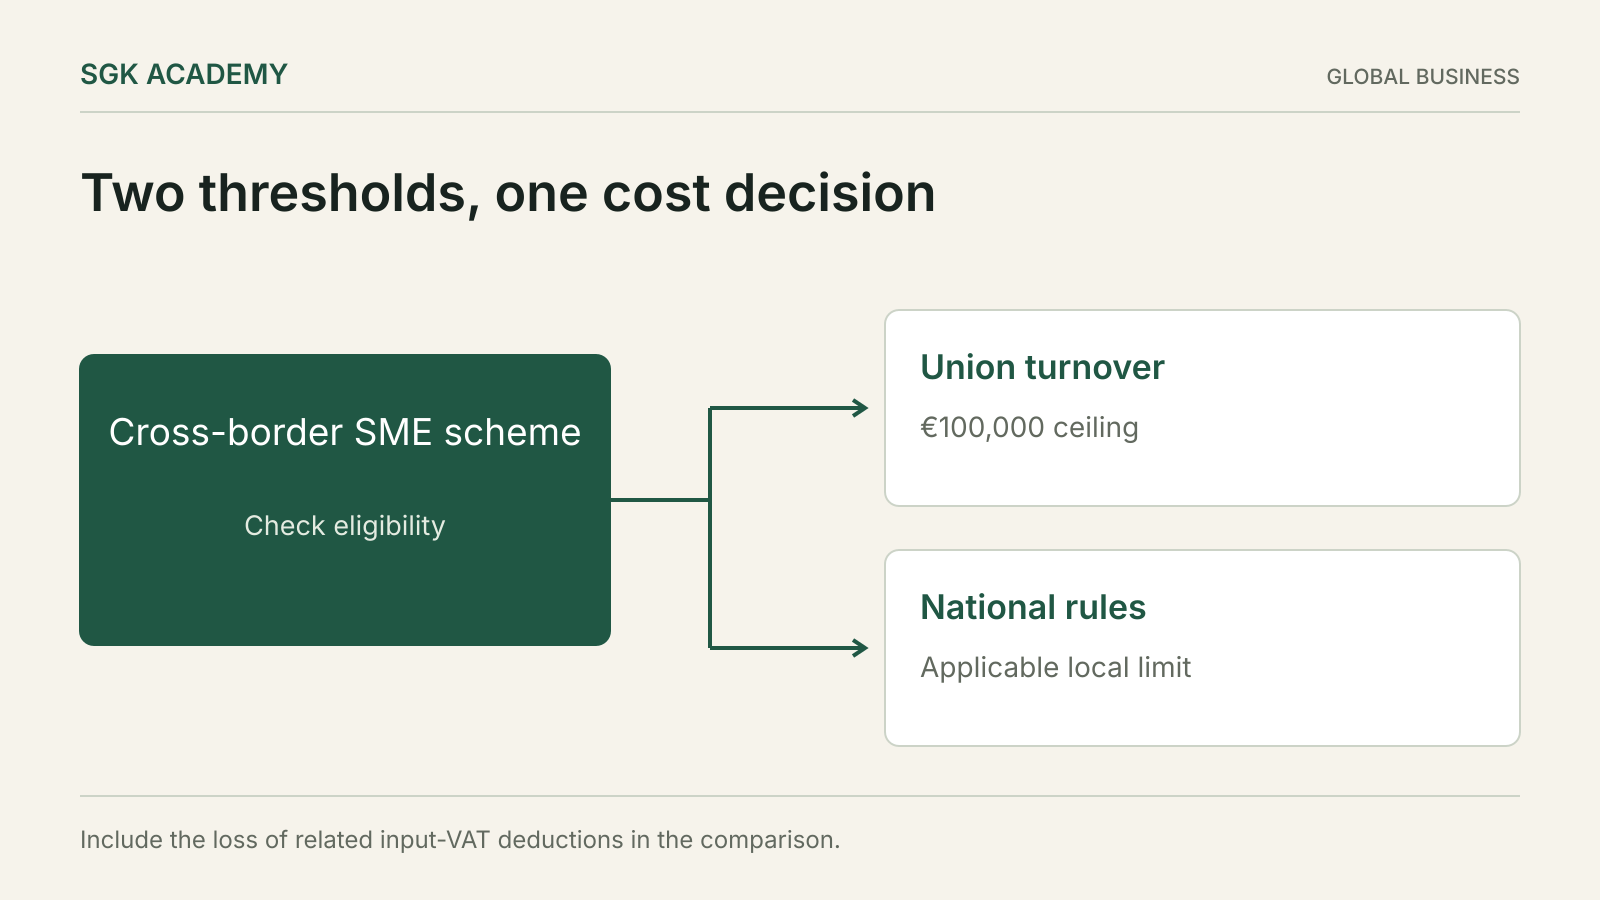
Two thresholds, one cost decision. Include the loss of related input-VAT deductions in the comparison.
VAT ·

EU SME VAT Scheme: When the Exemption Helps

Who can use the EU SME VAT scheme, the €100,000 and national limits, the EX number, and a year that crosses the limit.

SGK Academy

What are you looking for?

Search a topic, product or question