Guides: cross-border business

tax residence ·

Certificate of Tax Residence: A Practical Cross-Border Guide

How to document tax residence, claim treaty relief and avoid withholding delays.
CFC rules ·

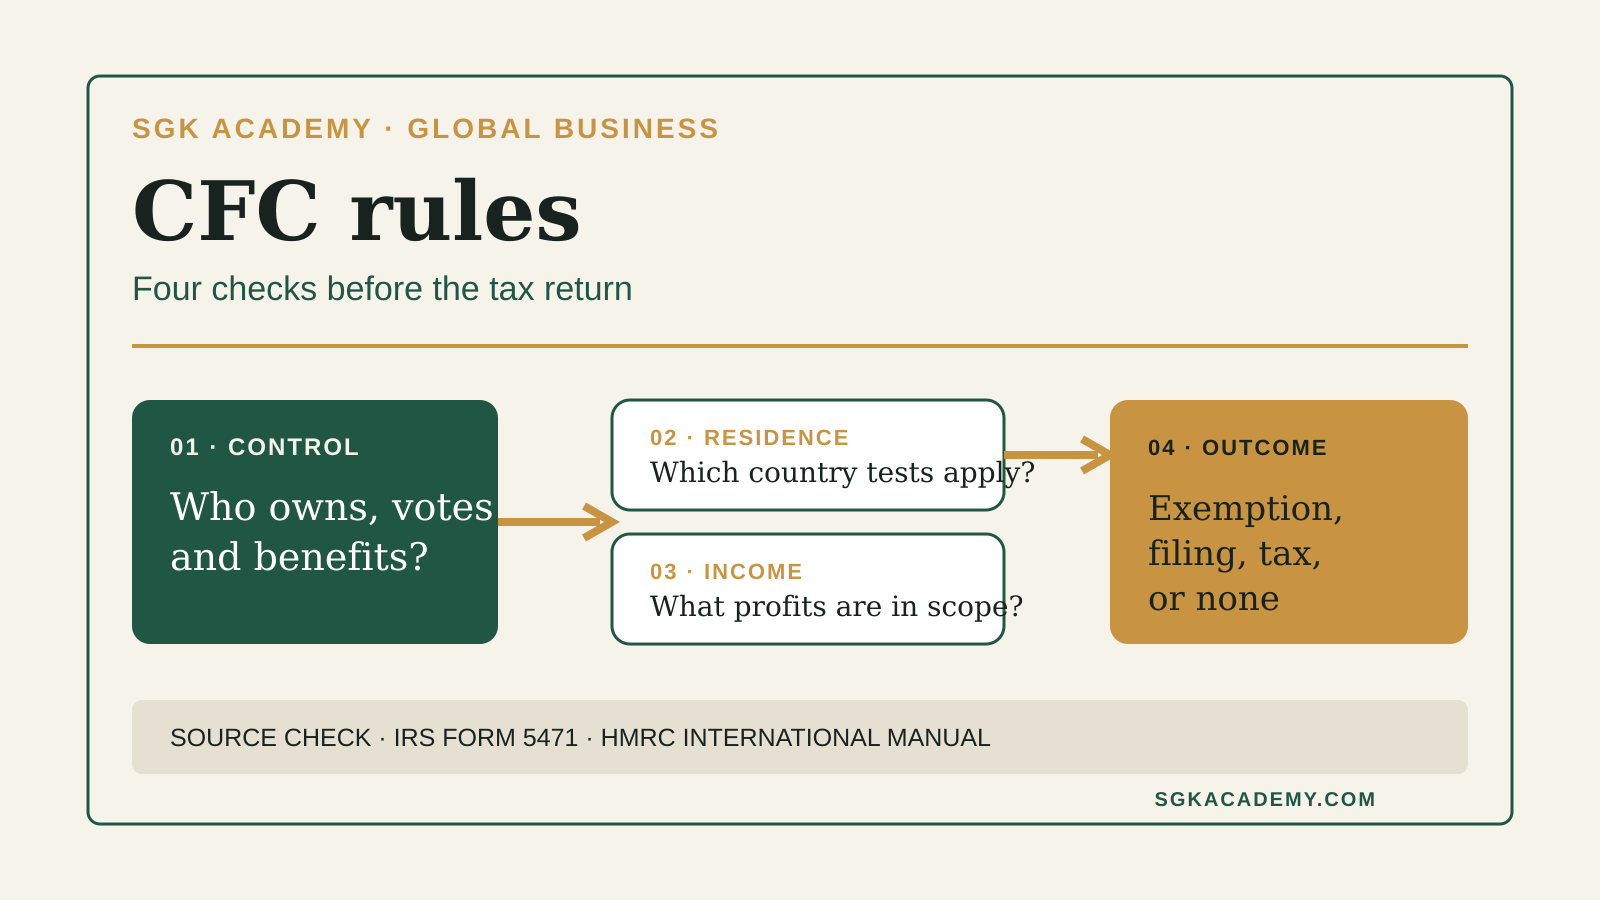
CFC Rules: A Screening Guide for Foreign Company Owners

A practical CFC rules check for ownership, residence, income, exemptions and filing duties.
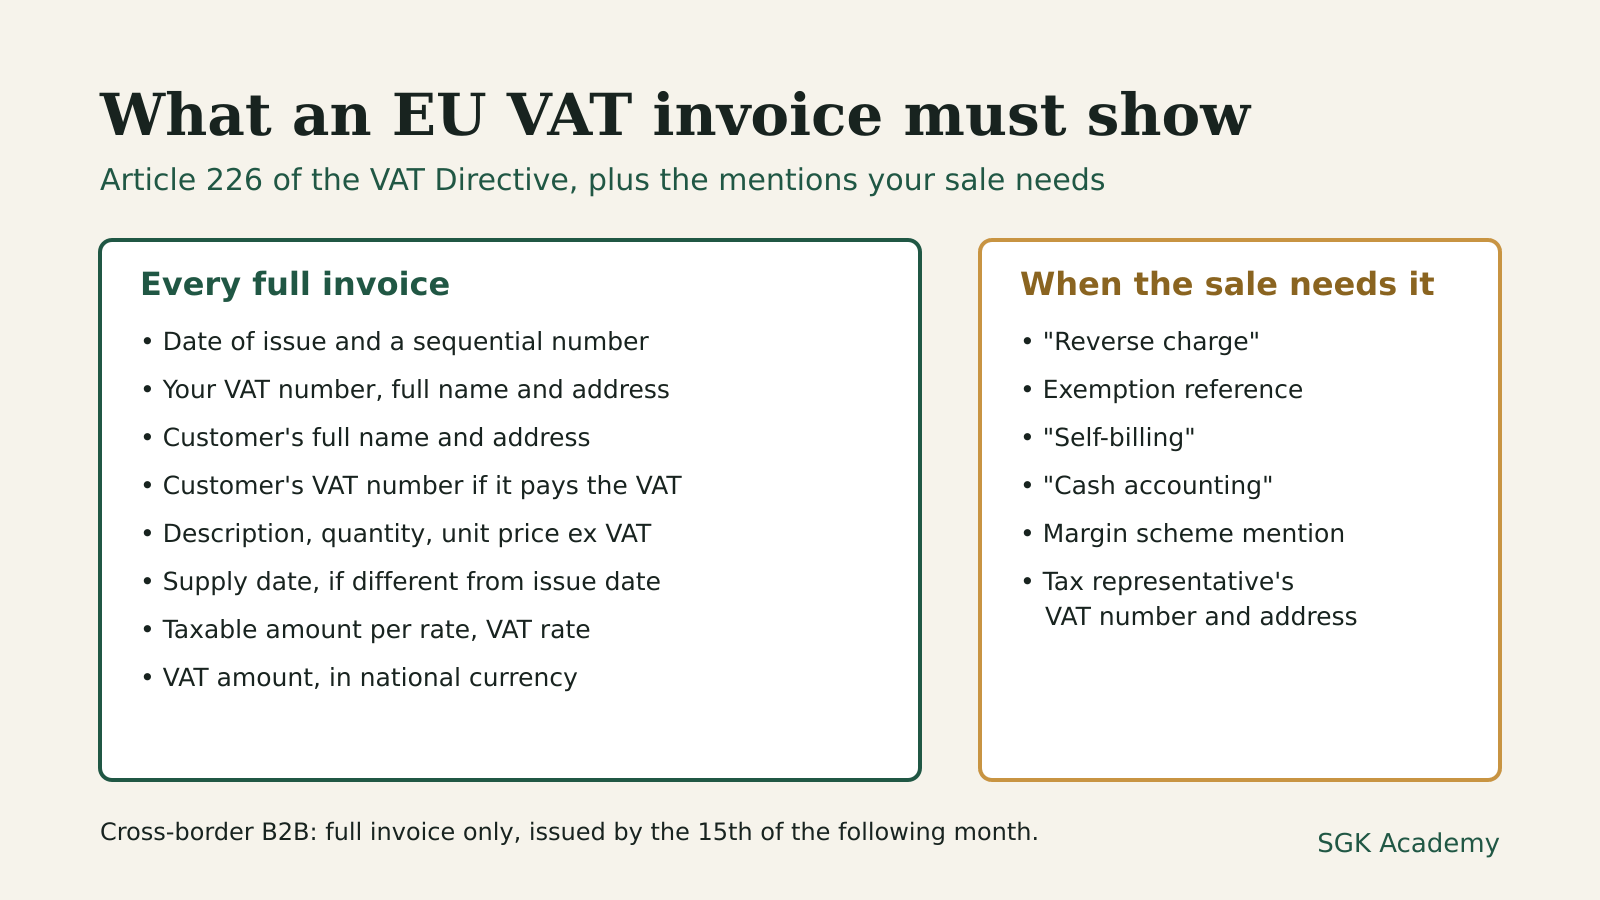
Diagram listing what every full EU VAT invoice must show (date and sequential number, both parties' names and addresses, VAT numbers, description and unit price, supply date, taxable amount per rate, VAT rate and amount in national currency) and the mentions some sales need (reverse charge, exemption reference, self-billing, cash accounting, margin scheme, tax representative).
VAT ·

VAT Invoice Requirements: What an EU Invoice Must Show

The details every EU VAT invoice needs under Article 226, the extra mentions, simplified invoices and deadlines.
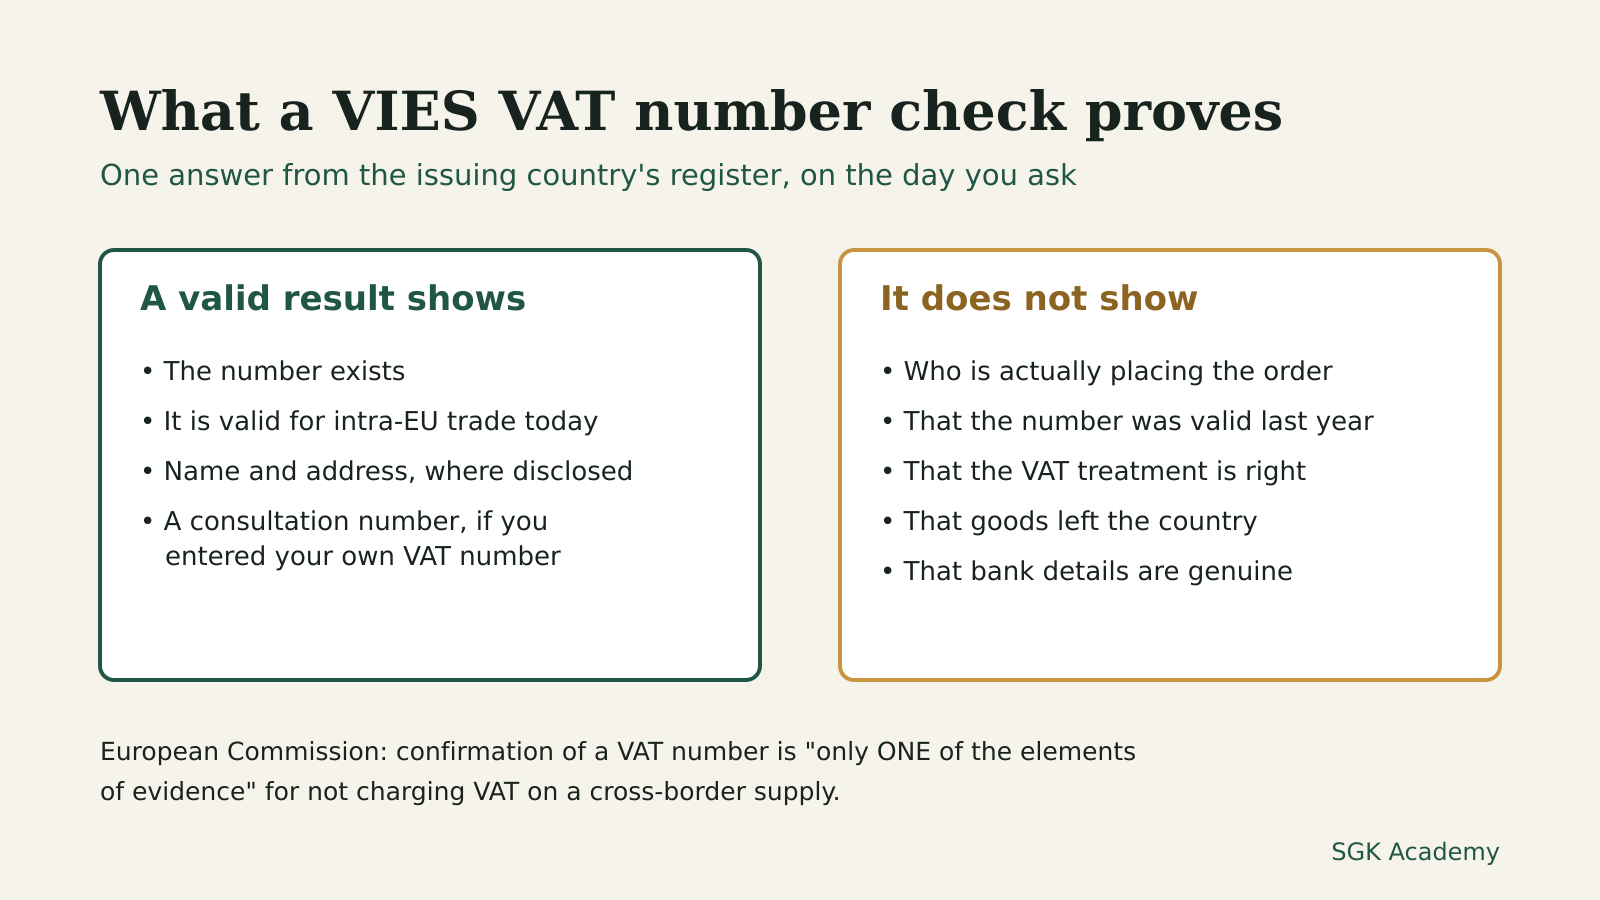
Diagram comparing what a valid VIES VAT number check shows (the number exists, is valid for intra-EU trade today, name and address where disclosed, a consultation number) with what it does not show (who places the order, past validity, correct VAT treatment, goods leaving the country, genuine bank details).
VAT ·

VIES VAT Number Check: What a Valid Result Proves

A valid VIES result lets you treat a customer as a business. How to run a check you can prove later, and its limits.
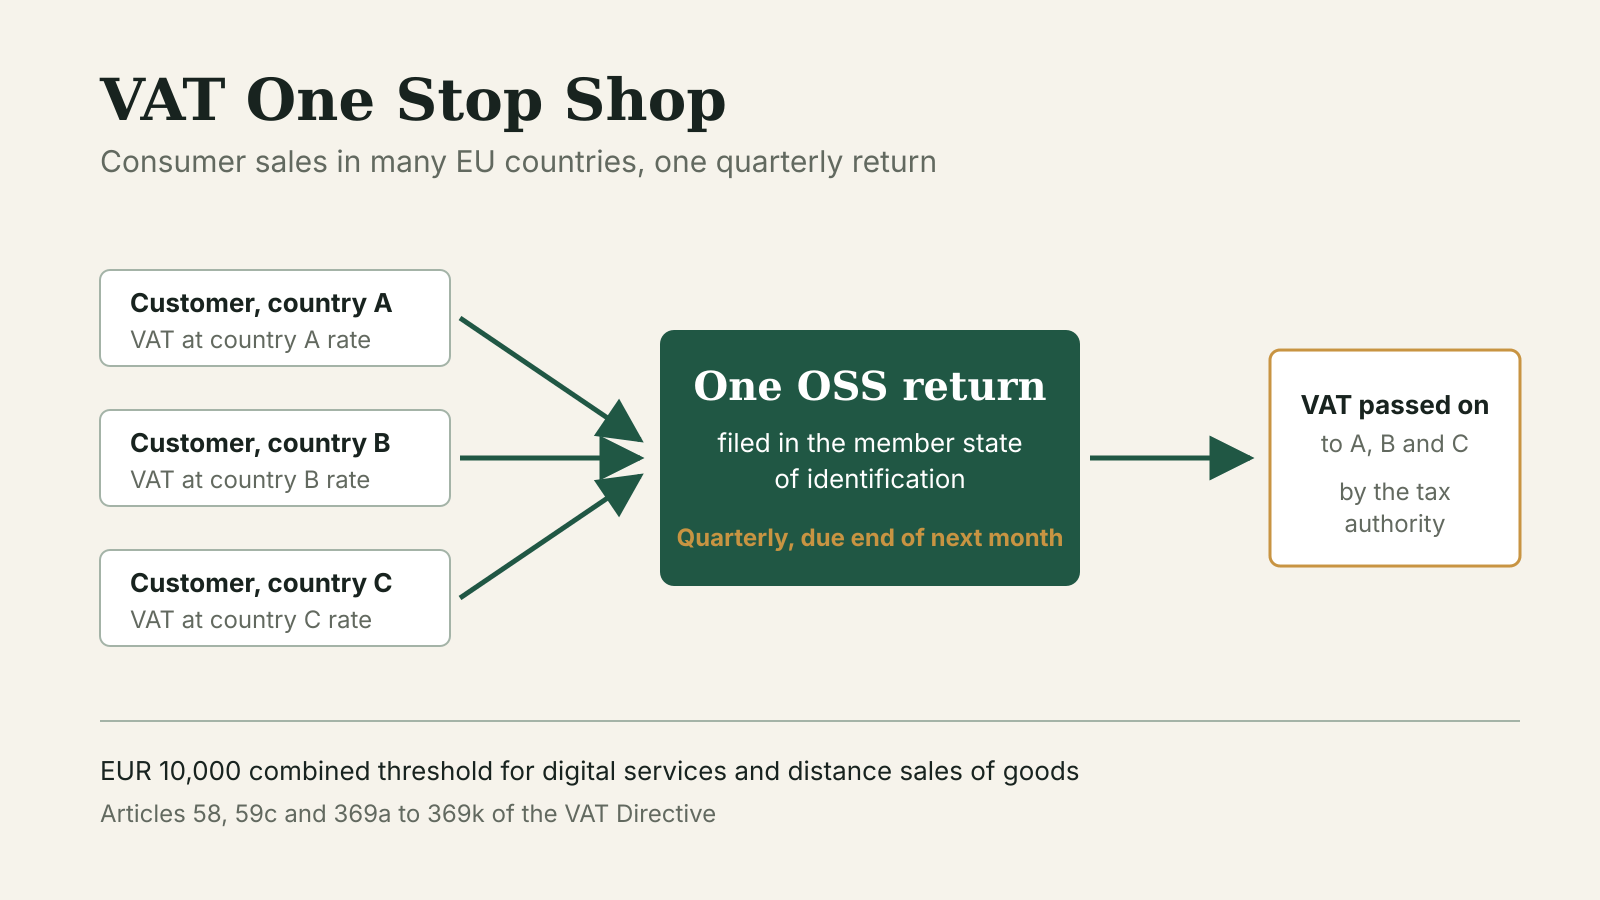
Diagram of the VAT One Stop Shop: sales to consumers in countries A, B and C, each at that country's VAT rate, go into one quarterly OSS return filed in the member state of identification, which passes the VAT on.
VAT ·

VAT One Stop Shop (OSS): One Return for EU Consumer Sales

How the EU One Stop Shop that replaced MOSS works, the EUR 10,000 threshold and what changes in 2027.
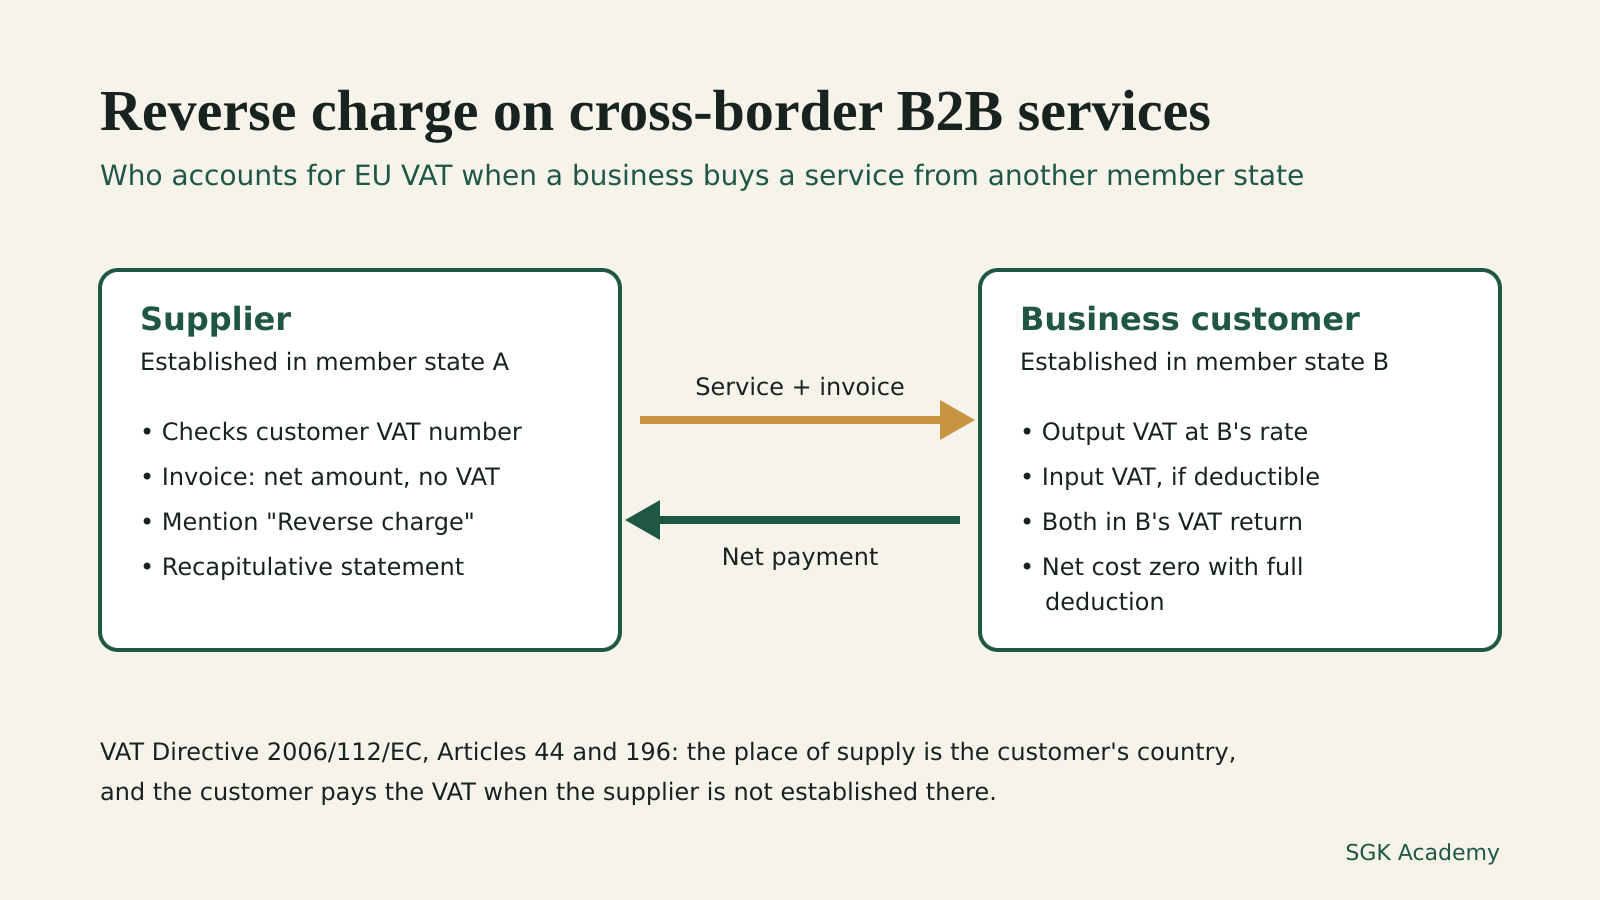
Diagram of the EU reverse charge: a supplier in member state A invoices a business customer in member state B without VAT, and the customer records output and input VAT in its own return.
VAT ·

Reverse Charge VAT on Services in the EU: Who Pays and What to Invoice

When a business buys a service from another EU country, it usually pays the VAT itself. What each side records.
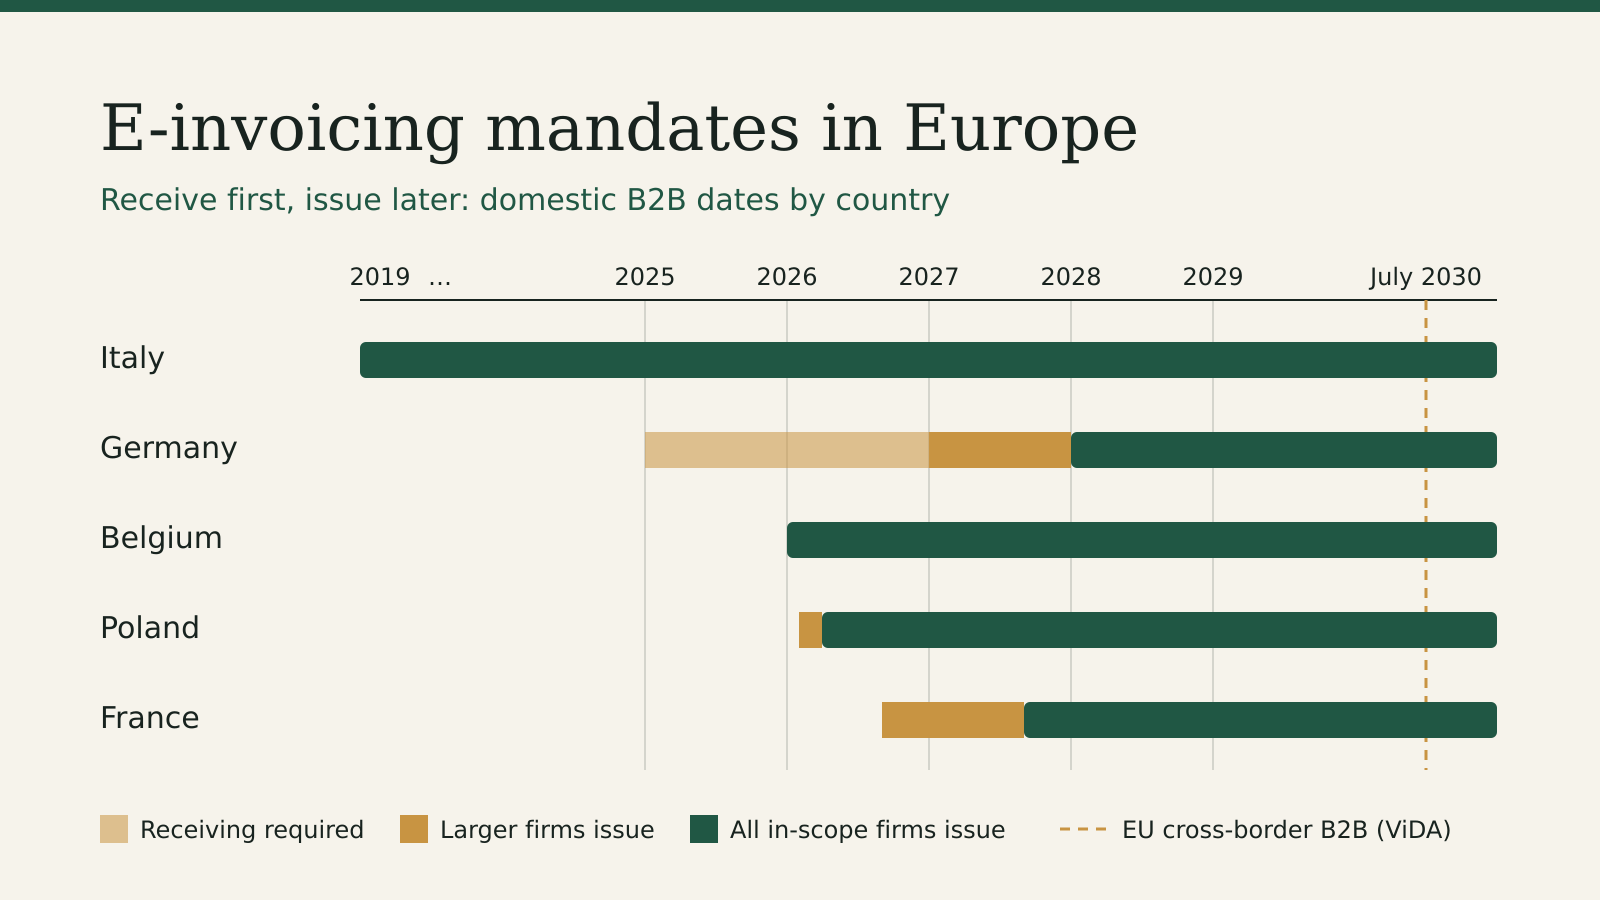
Timeline of domestic B2B e-invoicing mandates in Italy, Germany, Belgium, Poland and France, from 2019 to the EU cross-border rules in July 2030.
e-invoicing ·

E-Invoicing Mandates in Europe: Who Must Send and Receive, and When

When businesses in five EU countries must receive and issue structured B2B invoices.
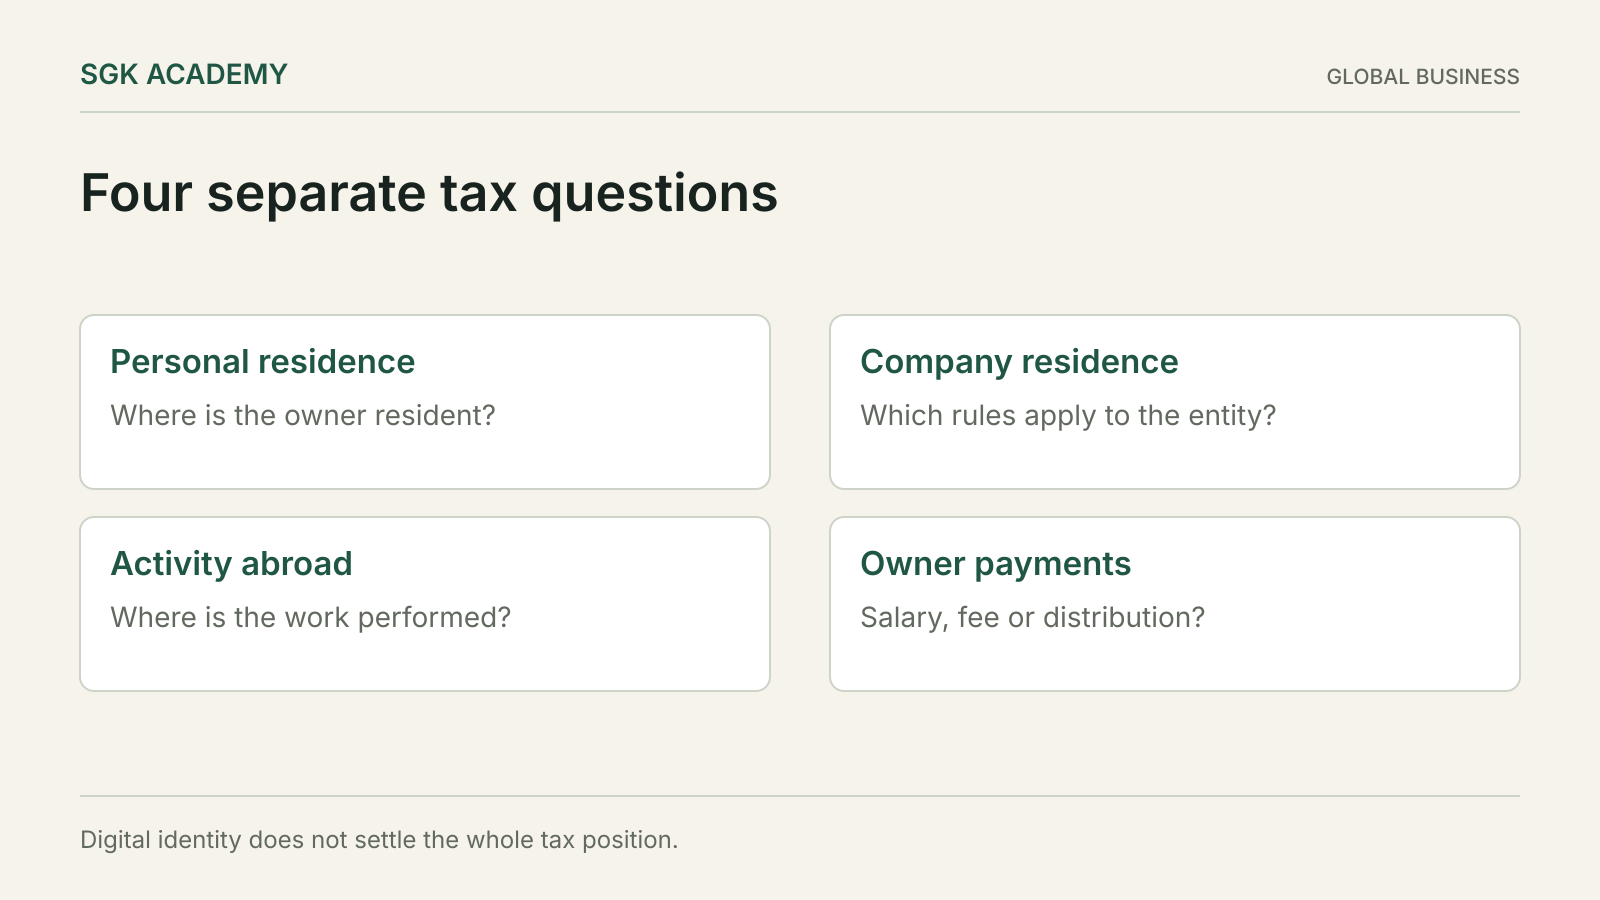
Four separate tax questions. Digital identity does not settle the whole tax position.
Estonia ·

Estonian E-Residency and Tax: Four Separate Questions

Separate digital identity, company residence, work location and personal tax obligations.
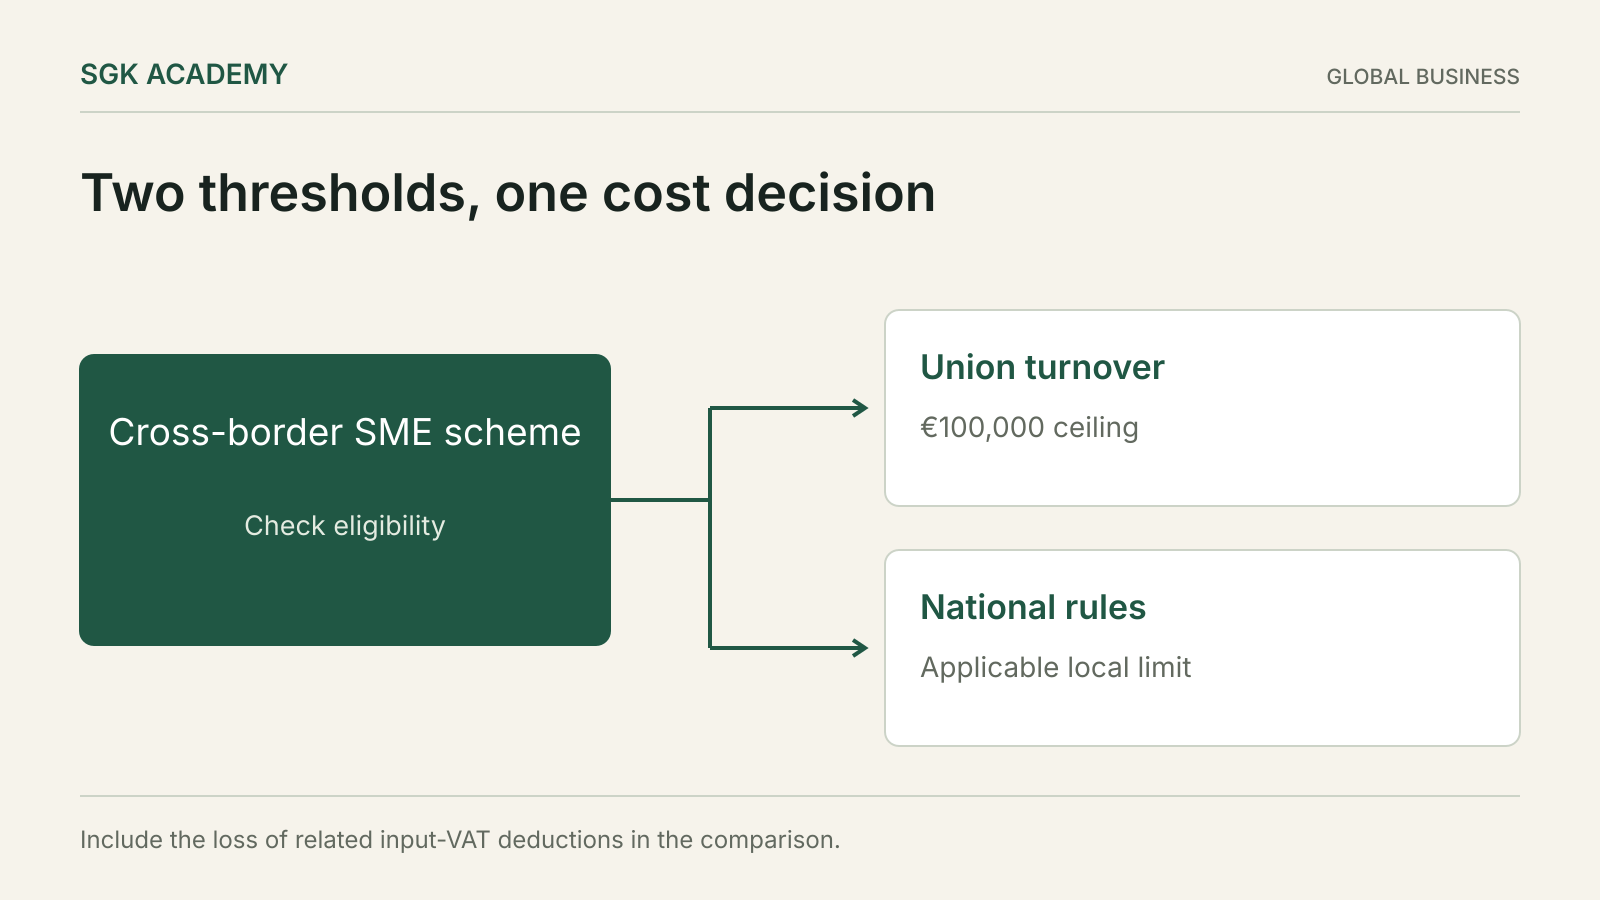
Two thresholds, one cost decision. Include the loss of related input-VAT deductions in the comparison.
VAT ·

EU SME VAT Scheme: When the Exemption Helps

Who can use the EU SME VAT scheme, the €100,000 and national limits, the EX number, and a year that crosses the limit.

SGK Academy

What are you looking for?

Search a topic, product or question